• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Society

Nicholas Chammas assesses 2012

by Nabila Rahhal December 4, 2012
written by Nabila Rahhal

In September, Executive sat down with Nicholas Chammas, head of the Lebanese Traders Association (LTA), to discuss the retail sector’s weak performance following the events this summer, from the warnings against travel to Lebanon by Gulf states, to the kidnappings of foreign visitors and the closures of the airport. Given all this, it was no surprise that the LTA was warning of a major crisis should the situation persist. For our end-of-year issue, Executive sat down with Chammas again to see what, if anything, had changed since our     last meeting. 

Since our last chat with you, the third quarter index has come out. What can you tell us about that?

The third quarter of 2012, in comparison with 2011, saw a drop of 8.5 percent in the LTA-Fransabank retail index. All sectors have been affected but in different proportions. Durable goods [such as electronics and furniture] saw a steeper decline than basic goods [such as clothes, school items, food and drink]… as they are more expensive and are one-off items, while the others are basic staples and everyday consumptions which cannot be really postponed or compressed. 

In fact, the only commodity whose purchasing percentages went up was fuel and oil [up 7 percent], because there is elasticity between the price and demand: when the price falls, the demand increases and this is what happened. Were it not for this, we would have had a double-digit drop in commercial activity. 

How do you see the rest of the year playing out?

We usually have four high points on the trade calendar: the summer season, the Adha holiday period, the Eid al-Fitr holiday period and the Christmas period. This year, three of these points were hit. 

As for the Christmas holiday period, things don’t look good so far because of regional and local tensions. Already half of the fourth quarter has been lost or wasted because of the assassination of Brigadier General Wissam al-Hassan [in October]. We are left with six weeks and if we extrapolate from an earlier period, I am not too optimistic. I hope for the best but fear the worst. If, God forbid, something negative happens in that period, then all will be lost and it will be one of the worst years for the retail sector since the [civil] war ended.

In 2013, the Beirut City Centre Mall will be opening its doors, as well as other malls outside of Beirut, such as the Cascada Mall in Bekaa. Do you think this will return some activity to the sector?

We hope so, but this is on the offer side, which is already dynamic. The offer is there, we have an oversupply even, but we need the other side of the equation, which is the demand. Once it’s there, there is no problem. The local demand is not nearly enough for the expanded offer that we have so we need the expats and the tourists. 

What do you see for the retail sector in 2013? 

There are three segments in the market, the Lebanese locals, the Lebanese expatriates and the Arab tourists, which are represented by a three-legged stool. One leg of the stool, the Arab tourists, has been lost. The second leg, the expats, has been coming more timidly to the country. So the country cannot survive without the three legs.

As for the Lebanese locals, as our report shows, there is shyness in spending and a drop in the purchasing power and disposable income of the Lebanese. So, this is why it is has been so tough. Here we need improvement across the board. We need stability and peace of mind for consumers to come back to Lebanon and spend. 

December 4, 2012 0 comments
0 FacebookTwitterPinterestEmail
Business

Q&A – Saad Andary

by Maya Sioufi December 4, 2012
written by Maya Sioufi

The public sector’s support for entrepreneurship in Lebanon has largely been timid. One public institution that is trying to be active and encourage the country’s enterprising youth is Banque du Liban (BDL), Lebanon’s central bank. BDL has been organizing conferences and launched an online platform in 2011 dedicated to entrepreneurs, but it has failed to gain momentum so far. Saad Andary, vice-governor of Lebanon’s central bank, says BDL has not given up, however, as fostering young talent is essential for the local economy. Executive sat with Andary to discuss BDL’s support for Lebanese talent. 

How will supporting entrepreneurs in Lebanon help spur the local economy?

Lebanon is a mercantile economy and it cannot continue forever like this because we are shedding a lot of talent year in, year out, as we can’t find them jobs. I am trying to reinvent the economy. What we can do here is build on the potential strengths of the economy, that we are a service-based society with human resources, a number of first-class universities and first-class academics. There is a mismatching in human resources so we have to build an economy that matches the talent, since it already exists. The economy should provide jobs for these talents, in medicine, educational services and financial services; in other words, in knowledge-based sectors. 

What is the aim of the online entrepreneurs’ platform launched by the central bank?

We started working on the platform in 2009 and it was launched in 2011. Our aim is to get people to talk to each other. We are working on it. It is not gaining enough momentum though. We are currently speaking to entrepreneurs to help us revamp and redirect the website. We are doing things that are not the norm, not the way the government would expect you to behave. 

Why is the central bank taking the initiative to support entrepreneurs in Lebanon?

As the central bank, it is not our mandate to do this. There is no evidence on the entrepreneurs’ platform that the central bank is behind it. We are the invisible hand that is motivating people to work because it will alienate people in high offices and in the ministries that the central bank is doing things they should be doing and have not bothered to do all these years. I used to go to them [to request their support] but they said they did not have the budget for it. 

What is the central bank doing to help entrepreneurs secure funding?

Young people are always confronted with difficulty in finding funds. Banks won’t fund startups. They fund you if you have already started up, are already established and have guarantees and collateral. So we have to work on creating a capital market capable of providing equity financing, not just debt financing. We have a new financial market authority that has been instituted recently, presided over by the governor of the central bank [Riad Salameh] but it is still early days. Meanwhile, we are working on a project with the World Bank for equity funding. If you go to people who have equity in times of insecurity, they will hold back from deploying their capital. We have to start somewhere so we negotiated with the World Bank for a $30 million loan, which we will transform into equity. 

Where do you stand on the launch of this fund?

We are finalizing it now. It needs approval by Parliament and maybe should be ready in a couple of months. The fund will invest in Lebanese talent in a knowledge-based sector with up to $500,000 per project. Kafalat [the government institution supporting small and medium enterprises in Lebanon by providing loan guarantees] will run it through a holding company. We think it is original and exciting and if we succeed, we can replicate it in the region. 

What do you want from the government?

Before 2009, there was no entrepreneurship ecosystem. Many Lebanese came back from Silicon Valley, from London, from all over and found that the ecosystem is beginning to fall in place. What encouraged them to come back? I don’t know. Maybe our website? Your articles? I am hopeful. You can feel the buzz around you, the energy. We are trying to direct the energy, hopefully with the support of the government, but we don’t want direct intervention from the government nor do we want money or budgetary funds. We just want support to provide such or such a service. 

Do you expect the long overdue electronic signature draft law to pass soon? 

This law is ready. It is in Parliament now in its final stages. It is being discussed in committees… and should be implemented soon. 

How about other laws such as the competition law, also essential to be passed to support entrepreneurs in Lebanon?  

I think what is more essential than the passing of laws is the Investment Development Authority of Lebanon (IDAL) playing a more pivotal role. Ideally we should not be seen doing any of the [aforementioned] things that we have done. It should be the role of IDAL, but they have not done what their equivalent in Turkey has done. IDAL should have a vision and should be the focal point for all investors that are in Lebanon or coming into Lebanon. The prime minister and his office should support it directly; similar to what is done in Turkey. When encountering problems to bring in investments, IDAL could circumvent the red tape confronted when working with a number of ministers, because who is the head of the ministries? The prime minister, and he is best placed to solve any problems that might pop up. 

How about universities — what can they do to support the entrepreneurship ecosystem?

At the conferences we organized for entrepreneurs, we used to invite universities and we were happy to see that universities built on ideas that we discussed. The École Supérieure des Affaires started offering a masters [degree] in entrepreneurship. The dean of business at the Beirut Arab University implemented an institute for entrepreneurs. The American University of Beirut launched a center. 

What is needed for a startup to succeed in Lebanon?  

You need two things to succeed in Lebanon: one is to have an idea that could work and survive in Lebanon, and the other is for the company to operate in international markets. Lebanon is too small to survive on its own; that’s why its youth are struggling. 

What advice would you give to entrepreneurs in Lebanon? 

My advice is that we have to get started, not to waste time thinking about impediments. Get started, plunge in, feel the pain. If you fail, try again. Go for it. 

December 4, 2012 0 comments
0 FacebookTwitterPinterestEmail
Economics & Policy

Downsizing on the dollar

by Paul Cochrane December 4, 2012
written by Paul Cochrane

It has been a year most car dealerships would not like to see repeated. The economic downturn, inflation, high gas prices and political uncertainty have taken their toll on sales, with only a handful of dealers meeting, yet alone surpassing, their sales projections. In short, the automotive sector is yet another segment of the Lebanese economy that can be considered to be in ‘crisis mode’.

At first glance there would seem little cause for concern, with sales stronger than last year’s. In the first four months of 2012, 10,169 new passenger cars were sold, an increase of 12 percent on the same period in 2011, according to figures from the Automobile Importers Association (AIA). While sales slowed down over the summer, by the end of August sales were still up, by 7.6 percent on 2011, and up 2.1 percent on 2010, indicating that unit sales in 2012 would reach the benchmark figure set in 2008 of more than 30,000 new cars sold in one year. As of the end of October, overall sales had reached 29,198 units, up 6.28 percent on the previous year.

“Overall sales of new cars are very close to last year in terms of volume, although it’s not real growth,” said Nabil Bazerji, dealer for Suzuki, Lancia and Maserati, given that these statistics are for volumes, not turnover or dealership profits.

And it is turnover that is giving dealers headaches when they crunch the numbers, as 2012 has proved for the fourth year running that Lebanese are increasingly opting for small cars, with cars under $11,000 now accounting for an estimated 90 percent of all sales according to the AIA. This is important as, while selling a car is arguably, well, selling a car, the difference in margins between a vehicle with a $10,000 price tag and one twice or treble the price is huge, being around just $500 for a compact model; when you consider a dealership’s overheads, advertising campaigns and so on, that profit disappears about as fast as a liter of gas in a Hummer. As one dealer remarked off-the-record, “A mobile phone retailer has a higher margin on a mobile than we do on compact models.”

So, while volumes may be marginally better than last year, it is the smaller cars that are propping up the figures and making the sector seem falsely buoyant.
“There is a crisis when the market is up 6 percent but the luxury sector is down by over 10 percent,” said Pierre Heneine, financial manager at Bassoul-Heneine, dealer for Renault and Dacia. “Consumer confidence has been down for the past two to three years, and is down every month; why would you buy a luxury car?”

Unsurprisingly then, it is the brands with compact models that are having the best sales, and this has resulted in a kind of oligopoly, with seven brands accounting for three-quarters of sales, despite 70 brands being available on the market. Kia, Hyundai and Nissan are the top three sellers, with the Koreans brands accounting for 45.1 percent of the market and Nissan with 15.9 percent, followed by Toyota, Chevrolet, Renault and Volkswagen with a collective 15.46 percent.

“The Koreans have taken over the Toyota empire. Elsewhere in the world Koreans have risen, but they haven’t taken the same share like here,” said Marwan Naffi, general manager of Gabriel Abou Adal and Partners, distributor of Volvo. Kia has 27.2 percent of the Lebanese market, with 7,962 units sold as of the end of October, making Lebanon the only country in the world where Kia is the top-selling brand. Hyundai trails close behind with 17.91 percent of the market, at 5,230 units sold. For Renault, it has been “their best year since 1975,” said Heneine, with sales up 9.67 percent, with 1,066 units sold, and Dacia up 23.81 percent, with 338 cars sold.

Chinese brands have also had a bumper year, up 85 percent on 2011 with 308 cars sold, although accounting for just 1.18 percent of the market. Geely, which entered the market in June and is represented by Rasamny Automotive Industries — also the dealer for Hyundai — sold 143 cars in less than three months, signaling strong demand for low-priced models and raising questions whether Chinese brands could, in the near future, be the next usurper after the Koreans. After all, it was European car designers that turned around Korean brands, and Geely, for instance, has acquired Volvo, from which it is expected to benefit from Swedish design and technology expertise.

A perfect market

The dearth of public transport has driven demand for small vehicles as city run-arounds, and the transport ministry’s plan to introduce 250 public buses in the near future is not likely to dent sales of compacts until a more nationwide plan is, if ever, implemented. High fuel prices are pushing compact sales further, averaging more than $20 for 20 liters this year, and this has also had an impact on used car sales, down 17 percent on 2011 as of September, a trend compounded by dealerships pushing three to five-year warranties and service deals on new wheels. “People are asking about fuel efficiency. With the minimum wage $500 a month, people have no choice but to opt for a small car,” said Dayala Dagher, Natco, distributor of Kia.

There may also be a correlation between the surge in sales of compact cars, the drop in used cars sales and the loss of cheap smuggled fuel from Syria due to the conflict there, a supply loss which has been offset by Lebanon’s imports of oil and mineral fuels surging 89 percent in the first half of the year relative to 2011, to $3.2 billion, according to Bank Byblos data.


Losing the middle ground

Dampened economic sentiment in general has clearly impacted car sales, certainly in the above-$20,000 price bracket, and it has been a bad year for luxury car sales. “There is a crisis in the automotive sector and it is affecting the mid-class car segment, at $25,000 to $90,000, which was the core of the business,” said Bazerji. “Does it mean the middle class is poorer? If so, it is very dangerous for the economy of the country.”

The former cars of choice for Lebanese, German luxury brands such as BMW and Mercedes, while still enjoying relatively good sales, have seen sales of used models plummet; consumers are not just downgrading to cheaper Korean compact models, but sedans and sports models as well.

“Kia can now not be viewed as solely low cost, as people are upping their budgets. Before it was only $10,000 for a Kia, now it is $20,000 to $40,000 plus,” said Dagher. “And mentalities are changing. Former Peugeot, VW and BMW drivers are now switching to Kia as the quality and design has improved.”
In a market where dealers are seeking just a slither of a pie dominated by seven brands, this has resulted in price wars between mid-range and luxury brands, even to the detriment of brand equity. “There is competition in the luxury segment and it is affecting margins. And when a car sells for $55,000 and is then reduced to $38,000, what happens to the resale value and the brand equity?” said Cesar Aoun, general manager of Gargour and Fils, distributor of Mercedes, Smart, Jeep, Chrysler and Dodge. “The other school says ‘introduce the new model at $55,000 and then increase the price, as the customer will be happier as it is more of an investment’. It is like Rolex’s policy to increase prices by 10 to 15 percent every year, and why their watches still have value.”

Sales of Mercedes are down 7.95 percent, as of October, on the previous year, with 567 units sold in 2012, and Jaguar sales are down 18.8 percent, although BMW sales are up 43 percent on last year, to 567 units, attributed primarily to the release of the new 3 Series models.

In commercial sales, it has not been as bad a year as for passenger cars, with sales up 9.29 percent on 2011, from 1,743 units to 1,905 units. Renault-Dacia is this year’s number one in this segment, collaring 23 percent of the market.
Over in the rental sector, things have been far from rosy, due to a dearth of tourists. “It was killer this summer, with no business with rental companies whereas usually it’s a boost,” said Farid Homsi, general manager of IMPEX, distributor for GM, Chevrolet, Cadillac, Hummer and Isuzu.

No-show motor show

In such a downbeat environment, dealers were putting their hopes on a successful Beirut Motor Show in November to raise the sector’s profile, sell more units and offset a lackluster summer. But at a time when the dealers needed every boost they could get, it was decided in September to cancel the show due to political instability. The move has been criticized by dealerships, and some members of the AIA internally conceded in early October that the decision was perhaps not the right one.

“The downturn could’ve been countered if the motor show had not been canceled,” said Bazerji. “My point of view is it was a big mistake. Not only a mistake, a shame because we are not respecting an agenda of having this show every two years. When you’ve an agenda you follow it, whether it is a success or a flop.”

He added that, “Unfortunately the 2010 motor show was 6 years behind the last one, and while I accept 2006 was canceled, a force majeur, but other cancellations? …It is in a period of crisis that a motor show would be of use to the sector.”

Abou Adal’s Naffi also thinks it was a bad idea to cancel in the current doom and gloom. “It was a very bad idea not have the show, as it was needed to change the mood of the people,” he said. “The public have 1,001 things to worry about so we should’ve had the motor show as it would have changed the situation for 10 days and given us a strong sales hook, as the show has the highest traffic of all exhibitions in Lebanon with over 100,000 visitors.”
But other dealers think the costs of being at the show were economically unjustifiable and worth canceling. “In the two months leading up to the show everyone is waiting for it, so people don’t buy, and for two months afterwards you sell, maybe 3 to 5 percent more, but it is expensive to be there,” said Heneine.

“October started well but definitely since the assassination [of intelligence chief Wissam al-Hassan] things have been pretty slow,” said Homsi. “You feel consumers are a bit uncomfortable; we’ve had many potential buyers postpone.  October’s sales were down by 2.21 percent on the same month in 2011, with European and Japanese brands particularly feeling the downturn, slumping by 2.97 percent and 19.63 percent respectively on October 2011.
“You can’t forecast the rest of the year and the market is very much day-to-day,” said Homsi. “I think the last few months of the year will not be that easy and the figures will not be that strong.

Rough roads ahead

The outlook for next year is as unpredictable as sales for the last two months of the year, and there is no crystal ball into which dealers can look. The AIA has projected that the number of imported and registered new and used cars will have dropped to 70,000 in 2012, from 74,000 units in 2011, and 92,000 units in 2010.

“This market is unpredictable,” said Bazerji. “If the situation doesn’t deteriorate further, 2013 will be equal to this year, but it is directly linked to politics and the regional situation.” However, the economic forecast for next year is not overly promising, and there is also not likely to be a fall in oil prices. This is likely to ensure continued strong sales of smaller vehicles and the further marginalization of brands that don’t have compact cars in their line-ups. Dealers are, however, upping marketing campaigns, offering special deals, and opening new showrooms to encourage potential buyers to stop sitting on their wallets.
Dealers are also forecasting that the current market dominance by the Koreans will fade, especially if the Korean won appreciates relative to the Japanese yen. “I think the market is cyclical, and over the next four years people will move back to the European and Japanese heritage brands,” said Heneine. “And I think the trend for buying new small cars will lead to consumers shifting upwards to new, mid-range cars in the B and C segments, between $15,000 to $17,000. But for this to happen we need stability in the country and more consumer confidence.”

In the meantime, dealerships are opposed to a government plan to reintroduce diesel passenger cars, not only because of health hazards — the World Health Organization recently listed diesel as a carcinogen — but also due to the havoc caused in the market when the state changed diesel laws a decade ago, which dealers do not want to see repeated.  Dealerships are even more opposed to a plan to raise value added tax (VAT) by 50 percent on imported cars, from 10 percent to 15 percent. According to the AIA, this will lead to a 30 percent drop in car sales and an aggregate drop of $182 million in government revenues from customs duties, VAT and car registration fees. While the government estimates the VAT rise will lead to an additional $60 million in related tax revenues from imported cars, the AIA estimates that the net loss in government revenues from the VAT rise will reach $122 million in 2013.

“It is the wrong time to do this. The luxury market is down by 10 percent, so if VAT is increased by 50 percent it will completely kill the premium and luxury market,” said Heneine. “If VAT increases, we will have to think about our future strategies, and we won’t be hiring anymore staff.”

Instead of imposing the tax, the AIA is calling for the government to enforce the collection of unpaid road-usage fees, which are estimated at $56 million a year. According to the AIA, 829,000 registered cars, or 64 percent of total registered cars in Lebanon, pay road tax every year while 36 percent, or 467,000 registered cars, do not.

December 4, 2012 0 comments
0 FacebookTwitterPinterestEmail
Real Estate

Building regardless

by Thomas Schellen December 3, 2012
written by Thomas Schellen

Screech! Honk! And a few polite words. That is what it takes for the 40-ton dump truck on a busy intersection at noontime in the middle of Beirut’s Ashrafieh district to make cars give him enough space to squeeze a left turn onto the district artery, Independence Avenue. Neither the narrow side street from which the trucker emerged with a load of sand and rock, nor the main street, is suited for heavy vehicles. But a fleet of his colleagues will repeat the exercise every 20 or 30 minutes throughout the day, and not only on this one sunny November day. They are hauling excavated soil from a massive construction site on the southern slope of the Ashrafieh hill over the course of several weeks, so that the foundations for another multi-story apartment block can soon be poured.

The project where these lorries are loaded is not the only hyperactive property excavation in Ashrafieh in the fourth quarter of 2012, not by a long shot. Other earth removal motorcades are operating on other sites all throughout the busy district. Construction is ongoing along the district’s perimeter, at its very center and highest point, and on many of the narrow streets in between.

Projects are digging deeper and building higher than ever before, with residential towers reaching 20, 30 and even more than 40 floors into the urban sky. Around the 600-meter-short Omar Haimari Street, which marks the district’s highest stretch, just 40 steps away from Independence Ave, three massive developments are under way, including the 43-story Sky Gate, which, at only half its final height as November ended, was already visibly redefining the Ashrafieh skyline. It, and what is slated to be the even taller SAMA Tower that is reaching toward its 195-meter target height just west down Independence Avenue, are but two of a tide of projects altering the Beirut cityscape, and the fabric of suburban areas and the countryside around the capital, in profound and unprecedented ways.

The numbers don’t tally

At the changeover from 2012 to 2013, Ashrafieh is only one of many hotspots of construction activity; other hardcore development areas are the central district managed by urban renewal company Solidere, and parts of the ring road around the Beirut Municipality territory where some trash lands spotted with ugly commercial structures have been discovered by developers. Outside of the capital and immediate suburbia, residential clusters in the Metn region and leisure areas higher up the mountainous surrounds are flush with projects.   
What makes this fin-de-2012 image of high-gear development activity a puzzling picture is that it is being splashed across the small Lebanese canvas at a time when all indicators on real estate are, at face value, negative.

According to indicators compiled in the Bank Audi third-quarter economic report on Lebanon, cement deliveries, the number of real estate sales transactions and issuances of building permits were all down in the first three quarters of 2012. Property sales fell 9.2 percent for the nine-month period from a year ago, and contracted by an even higher 11.4 percent when comparing just the third quarter of 2012 with the same period in 2011.

The eight-month figures on cement deliveries were down to 3.4 million tons in 2012 from 3.7 million tons in 2011, and in square meters (sqm) worth of construction permits, issuance contracted to 10.7 million sqm 2012 from 12.4 million sqm in the first nine months of 2011. This constitutes drops of 7.9 percent on cement and 14.3 percent on licensed floor space. When factoring in the drop in property transaction numbers, the trio of real estate sector indicators shows, at least in theory, downturns on completed, ongoing and planned projects.

The caveat here is that these numbers are likely not entirely accurate. Property registrations are often delayed for purposes of tax avoidance and building permits don’t always translate into the same actual built-up area. Even cement figures have been suspected to be muddied by grey exports.

However, while developers and intermediaries in the real estate industry almost uniformly say that the situation must not be called a crisis, developers tell Executive that the slowdown in their activity in 2012 is real and the outlook for 2013 is muted.

Sales developments for the real estate projects of MENA Capital (which focused traditionally on the high end of the luxury market in prime areas of Beirut and whose largest project is Sky Gate) were negative in 2012 and 2011, confides Nabil Sawabini, the company’s chief executive. “The cumulative value of sales has been declining in the past two years; we sold more in 2010 than in [each of] 2011 and 12,” he says. Nonetheless, units in Sky Gate are about two-thirds sold, he adds.

Georges Chehwane, chief executive of developer Plus Properties, and of communications media and real estate conglomerate Plus Group, says regional uncertainty contributes to the slowdown, but adds that, “the main part is the large number of units that [have been] in the market since 2009, as there is a gap between the yearly demand and the yearly offer of supply. This is the main problem today in addition to the political situation in which people are not buying.”

The current real estate market confronts investors with a state of uncertainty, says Houssam Batal, chief executive of developer Prime Projects. “It is not very clear to say where [the market] will go. There is a feeling that there will be an oversupply in many product types. The main thing that is affecting the market right now is the political situation and instability, and the grey outlook related to Syria and to domestic issues that we have. The investors are worried about the dangers of bigger problems to come.”

Sadly for buyers, this does not mean that property bargains are going to abound next year.

“Demand has decreased, the economy is in a difficult situation and the future is somewhat blurred but prices for apartments and real estate, especially in prime areas, have remained stable and have increased in some cases. It is a weird economic picture,” says Ziad Maalouf, chief executive of Capstone Investment Group, a financial firm whose activities include real estate development.
Zardman, a developer that is fairly fresh in the market and claims to have seen moderate sales growth in 2011 and 2012 against market trends, also sees prices as moving sideways. “We have two sides to our business, addressing the middle class in the Metn region and the higher end market in Ashrafieh,” Makram Zard, the general manager of Zardman, tells Executive. “The Metn region was extremely good this year. Ashrafieh is doing well. I don’t think… that prices are dropping but sales are not quite as good as last year.”

Less for more

Maalouf’s and Zard’s assessment of unwavering prices fits with what other developers say, and statistics show that the cumulative value of property sales in Lebanon this year, despite the contraction in transaction volume, was up from last year. Correspondingly, the average value per transaction is the indicator that in 2012 showed the most pronounced gain for the year-to-date.

At $6.3 billion, the total value of the nine-month tally of registered property transactions was up 4.8 percent, but the average value per transaction increased 15.4 percent year-on-year to $120,000 from $104,000 for the January to September period, according to government figures cited by Bank Audi in mid-November.

The trend of price inelasticity is long-term. Although demand for real estate had been slowing since late 2010, expectations for lower prices harbored by property seekers had been disappointed even back then, according to Maalouf. “I have heard of a lot of people since 2009 and 2008 who had been delaying the purchase of an apartment in the hope of buying the same apartment later at a lower price. But this has not happened,” he explains.

At the junction of 2012 and 2013, the real estate market in Lebanon is a buyer’s market in terms of choice and options in up-market locations as long as a buyer has cash-stuffed pockets or a high and growing income. In terms of pricing, it is not a buyer’s market at all.

The market for the most important development resource, land, is also not a buyer’s dream. To the contrary, developers are faced with a very hard seller’s market, Maalouf adds. “Land prices have actually increased, despite everything. The weird thing is that expectations of land owners do not reflect realities. This is a catch for developers,” he explains. “On one hand you have buyers who see the prices for real estate as high and on the other hand you have land owners who have unrealistic expectations.”


Why so buoyant?

The reasons why even the oversupply of Lebanese properties does not generate much downward pressures on prices in the market for residential units are complicated.

One key factor is financial. Many developers in Lebanon self-finance, and the absence of funding pressure allows the economic self-interest of many developers to keep focused on achieving the maximal rate of return that they fixated about when embarking on their project. Developers in this category typically wait out the market if bid prices are below their expectation and can do so because they have no lending officers breathing down their necks.

Development activity may even be a one-off business for many and they base their profit modeling on building cost and land pricing, often adding in an upward revaluation of the plot during the development process — a reevaluation that, according to Zardman’s Zard, can be far higher than the amount that the interest component in a land financing agreement would represent.

Applying standard models where project companies are financed by equity from investors and by debt, or source revenues via off-plan sales, makes the developers more sensitive to market trends. This leads to more client-responsive pricing behavior and also supports rational adjustments of development activity, such as switching to more moderate unit sizes. According to Zard, developers like him — whose land value calculation in unit sales prices is based on land cost at purchase plus regular interest — transfer land value gains early on to the customer. “This is one of the reasons why our sales have been excellent when compared with the market,” he claims.   

Oft-quoted rationalizations why property prices in Lebanon would not follow cyclical patterns that are familiar from other markets are the high density of the population, the small surface territory of the nation (167th among 249 countries and territories in the world by land size), and the even smaller size of land accessible for development. According to Chehwane, roughly half of the national territory is off limits for property development because of terrain conditions, agricultural usage and ownership by religious orders.

Weighing in on the demand side of the equation are not only the young families living in the country but also the outsized theoretical buyer pool of the so-called Lebanese diaspora, which comprises millions of Lebanon-born and descendent citizens of countries in South and North America, Oceania, Europe and Africa. The second notable source of external demand is from Gulf buyers. “The Lebanese market for real estate is very dependent on Lebanese living outside the country and also on foreigners,” says MENA Capital’s Sawabini.

Brand it, baby

Younger Lebanese who have acquired sufficient means to buy an apartment in the high-priced Ashrafieh market, by laboring as expatriate managers in Dubai or Riyadh, may be less attached than earlier generations to traditional ties of kin in their residential choices but they also display strong patterns of selectivity in property buying. It is the location and the “prestigious address” that matters greatly to them, according to Zard.

This means that developers are paying increasing attention to building a reputation and brand identity for their pricey towers.

Branding a project and defending this brand against copycatting is also crucial in differentiating a project, says Ayad Nasser, owner and chief executive of developer Loft Investments. “In Lebanon, 99 percent of the projects look the same,” says Nasser. “The entire market is focused on the 99 percent of the population [who buy those types of properties]. I am not marketing to a percentage. I am marketing to people who have that drive to live in a different project.”

The differentiation of his projects is not by location but by concept and design, services and quality, he claims, and in that space “it is very important to have a brand today. ”

Counting urbanity

But before discussing the future potentials of some branding or non-branding concepts on Lebanese real estate, or musing on the ironies of cement blocks bearing names such as ‘pretty house’ or ‘xyz gardens’, some much more elementary points call for clarification. Such as, how many floors of concrete are being cast presently in areas like Downtown Beirut or Ashrafieh? How many and what sizes of units are going to drop into the Lebanese market in 2013?
Prime Projects’ Batal, a university-trained professional in real estate, answers the question on the incoming supply by saying, “There are data reports suggesting that supply is broadening versus demand but I don’t know if these reports are reliable and accurate,” adding that he has no numbers on how many projects were going up in Ashrafieh in November 2012.

He is not alone. Loft Investments’ Nasser, who says his track record of delivery includes 270 apartments since he started out with a single suburban unit in 1994, is not convinced by market research or price comparisons. “I never consult statistics; I never do a marketing plan, nothing. We just feel it. I am very confident about my clientele. I have in my portfolio different clients who became friends and I know that 10 percent of those people will be my clients, so while I am buying the land [for a new project], I call them,” he says.

Nasser admits that he does not even know the asking prices in developments going up next to his projects, but he affirms on the other hand that Lebanon’s developers “need to assess the market and the government needs to put some rules.”

Both market assessment and better rules are points that Plus Properties’ Chehwane sees as paramount necessities. He is one of the players pushing actively for realizing a professional association of developers, which he envisions to have as its core activity the compilation and publication of sector data.

Chehwane adds that there are no statistics on the real property development situation in key areas such as Ashrafieh. When asked what he believes to be the number of projects and units under development in this very district, he answers , “100 projects, at least. I believe [Ashrafieh has] around 3,000 units today under construction.”

It is futile to query either public officials or private developers for an accurate number on buildings under construction in Beirut today. So to garner at least some idea of the actual number, Executive reverted to good ol’ fashioned journalism — a pad, a pen and pounding the pavement in a random part of Ashrafieh.

Within less than ten minutes walk on one trajectory only, ascending from the Hospital Dieu area toward Sioufi Gardens, Executive found six residential projects in progress, of which one looked ready for handover (14 stories), two 12-story ones were in advanced stages of construction and should be ready for occupancy in 2013, one was a six-story shell that was frozen and the two largest sites were in the excavation phase. One of these two will have 28 stories with 43 flats of 320 to 540 sqm. The other will comprise office, commercial and residential units in two towers of eight and 11 floors.

Next was a check of the cobweb of narrow passages and bumpy streets between this project site and Alfred Naccache Street. This little quarter revealed another five projects and one plot that looked ready for the start of excavation. The largest site here was an apartment complex nearing completion with four segments ranging from 13 to 20 stories. On the eastside of Alfred Naccache Street, three more new multi-story buildings added to the ongoing development tally of this southeastern corner of Ashrafieh, in an area fully coverable on foot within 15 minutes. 

Expanding the random walk of Ashrafieh to a wider grid, Chehwane’s estimation of at least 100 ongoing projects doesn’t actually look far off the mark; if anything, it is an underestimation.

Bigger fish to fry

One has to note here that getting better data is a strategic need for developers; however, it is not an existential problem for the property makers. Their concerns and hopes lie elsewhere. The most important factor influencing Lebanese real estate now is Syria, says Capstone’s Maalouf. “If there is regime change in Syria tomorrow, I think this will have very positive spillovers on the market here. I foresee a boom [under such circumstances] simply because the confidence in the Lebanese real estate sector is going to be regained.”

For his part, Chehwane sees only temporary worries in the current oversupply with units. “The moment that we will have a positive atmosphere and positive situation, 50 percent of the stock that is available in the market will be sold. We need one year like 2006 before the war or 2008 before the crisis, and you will have a very good situation,” he enthuses.

From another, more public perspective, development takes on a different angle. Only reviewing the last five years, the cumulative square meter figure for building permits issued between January and August of each year comes to 39.85 million sqm. That is an addition of roughly 10 square meters per resident of Lebanon in a very short time, in a country that already feels stuffed with concrete buildings.   

Despite developers chiming the marketable tune that land is scarce and unaffordable for them, it can be predicted that another tide of private real estate growth will happen, quite likely within a decade at most when considering the activity cycles of the past 10 years.

Factor that in and it becomes over-evident how urgently the Beirut metro area and the country as a whole need to achieve some crucial changes of behavior: Lebanon needs planning. It needs development norms and standards that are sustainable and applied universally. It needs infrastructure, namely infrastructure that is adequate and steers growth in directions that make sense for the future. Public and private property represent the spine and skeleton of Lebanon’s future living quality. The spine has to be straightened out.
 

December 3, 2012 0 comments
0 FacebookTwitterPinterestEmail
Comment

Entering subsistence

by Jihad Yazigi December 3, 2012
written by Jihad Yazigi

One of the main questions surrounding the Syrian uprising at the beginning of 2012 was if and when an economic collapse would occur. As the year draws to a close, the question has instead become whether one can still talk of “a” Syrian economy as such.

What remains of the country’s formal economy has seriously deteriorated throughout the year. Business activity significantly contracted and although the government has released no estimates, gross domestic product is believed to have fallen by at least 25 percent in the first nine months of 2012.  Disintegrating distribution and supply networks, a government increase in energy prices and a hike in the cost of imported items all combined to gradually increase the inflation rate; the consumer price index was up by 40 percent on an annual basis by August.

The Syrian pound, after having resisted all forms of pressure relatively well in 2011, lost ground. From a rate of 60 to the dollar at the beginning of the year, the exchange rate fell to over 80 pounds by mid-November 2012.

An important development has been the expansion of the violence to Aleppo during the summer, a city that had largely remained outside the popular uprising until then. Aleppo is Syria’s largest city by population, but also the country’s main manufacturing hub as well as a major trading and distribution center for agricultural products. The unrest in the city led, among other things, to the closure of its industrial city with some 600 factories suspending production.

However, while observers continue to monitor most formal indicators — such as inflation and the currency rates — as a means to measure investor sentiments, in practice most of the country’s economy now falls outside these numbers.

The expansion of violence and the varying degrees of state control over large sways of Syria have profoundly transformed its economy to the extent that one can now talk of a war economy, the creation of new business networks and the development of various new forms of trade, including smuggling, looting and kidnapping.

Some areas of the country are still firmly under state control and as such continue to be provided by regular government services — these include the provinces of Latakia, Tartous and Suweida as well as the central parts of Damascus. In these parts of the country the supply of products continues at relatively normal levels, although prices have skyrocketed.

Other areas have little left of the state, such as the rural parts of Aleppo, Idlib, Hama, Homs and Daraa. Meanwhile, the cities of Aleppo and Der-ez-Zour are under constant bombardment and have almost no business activity to speak of, while the northeast of the country is growing increasingly autonomous in the management of its day-to-day affairs. Looting is common in areas where inhabitants have fled; smuggling to and from neighboring countries has exploded as the government’s control over its borders weakened, customs tariffs increased and formal international banking transactions are at a standstill; kidnapping for ransom is widespread.

As the autumn pushed on, the government finally began to express more openly its concerns for the near future. In a well-publicized statement, the deputy prime minister in charge of economic affairs, Qadri Jamil, said in September that in the absence of a political solution to the crisis gripping the country, the economy was heading towards “a stroke” by the end of the year. Jamil was forced to retract his statement a few days later, but the damage was done. 

Meanwhile, in early October, the Minister of Agriculture Subhi al-Abdallah encouraged his fellow citizens to “grow whatever they could grow and raise whatever animal or chicken they could raise.” Abdallah’s words echoed a prevailing sentiment in Syria: slowly but surely, the economy was moving towards subsistence mode. 

The depth of distress in the economy, reflected in these statements, points to the major challenges ahead for Syria’s future decision makers. Syria may manage to rebuild relatively quickly its physical infrastructure, but it will require a very significant redefinition of economic policy, an overhaul of existing business and trade ties and a formalization of much of its economic activity before the country truly recovers from the devastation it is facing.


Jihad Yazigi is editor-in-chief of The Syria Report


December 3, 2012 0 comments
0 FacebookTwitterPinterestEmail
Comment

No end to injustice

by Ahmed Moor December 3, 2012
written by Ahmed Moor

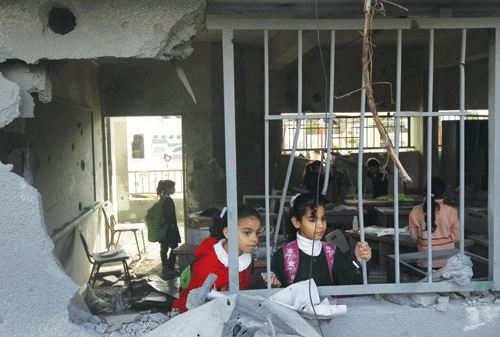
For the Palestinians the passage of time offers little reprieve. While their circumstances have changed this past year, they have only changed for the worse. Israel has systematically worked to isolate them and hem them into smaller spaces. Governments worldwide seem prepared to accept their continued deprivation and Israel’s steroidal apartheid. The latest salvo between Palestinians in the Gaza Strip and Israel ended with more than 150 dead Palestinians, the majority of whom were civilians, and five Israelis killed. The conflict is deepening. 

Some analysts continue to insist that there is a two-state blueprint that is workable for the Palestinians and Israelis. In fact, reality has moved sharply away from any such accommodation. The settlements in the West Bank and around Jerusalem have altered the ‘reality on the ground’ in irreversible ways. Jerusalem is being ethnically cleansed. Palestine has been colonized into nothing. That’s the reality.

At this stage it is worth evaluating what the overall Israeli policy in Jerusalem and the West Bank appears to be. While decision-making in Israel appears to be driven by short-term considerations, there is a long-term outlook, and it is becoming more evident daily. Nir Barkat, the Jewish Israeli mayor of West Jerusalem, has been very effective at restricting the growth of Palestinian neighborhoods in occupied East Jerusalem. In some cases, public works projects are cynically announced with the object of forestalling Palestinian development. For instance, a large tract of private Palestinian land near the neighborhood of Silwan has recently been designated as “state property”. The Jerusalem municipality has declared that a park will be constructed on the site, a claim that some observers regard as a pretext for continued Israeli colonization of East Jerusalem. 

In Jerusalem, Palestinian life is so circumscribed that many of the city’s indigenous residents are forced to live elsewhere. The lack of development in Palestinian neighborhoods along with the refusal to grant building permits work to drive the Judaization of the city. 

Processes in the West Bank follow the dominant Jerusalem strategy. More than 60 percent of that occupied territory, the Oslo process’s “Areas B and C”, is off-limits to Palestinians. They are not granted building permits in their rural villages — a policy that forces many people into the Palestinian Authority (PA) administered “Area A”. In other words, a West Bank version of ‘bantustanization’ — the apartheid-era South African policy dividing up the territory of black inhabitants — is developing with few impediments. 

Essentially then, the Israeli strategy is to Judaize Jerusalem through ethnic cleansing while doing the same to Areas B and C of the West Bank. The “Gaza solution” — isolating Palestinians in shrinking cantons — is being adapted to the particular geography of the other Palestinian territories.

Historically, the PA leadership has demonstrated its profound impotence in the face of persistent Israeli apartheid and occupation. But that may be changing.

President Mahmoud Abbas’ decision to seek a status upgrade at the United Nations on November 29 is the most concrete challenge the PA has posed to the Israelis in years. In fact, the move poses a serious threat to the Israeli leadership because it could provide the Palestinians with access to international adjudicatory bodies. In particular, the International Criminal Court could be called upon to intervene in cases where sufficient evidence of Israeli crimes exists. Analysts have speculated that the Israeli decision to attack Gaza in November is linked in part to the Palestinian Authority’s decision to petition the United Nations for upgraded status. The Israeli elections in January and the fact that the other three Knesset elections this past decade were all preceded by massive military operations against Palestinian areas provides additional context for understanding the extent of the airstrikes. 

The context of the attacks in Gaza — indeed, the broader context of what’s happening to the Palestinians — has changed. The Middle East is no longer ruled by programmable autocrats. Egypt and Turkey in particular may produce a ceasefire in the short term and a change in European policy — if not American policy — in the long term. Egypt and Turkey succeeded in enhancing their diplomatic clout after brokering a ceasefire between Hamas fighters and the Israeli government; that trend is likely a sustainable one.

It is far too early to know what the different constellation of powers in the Middle East means for the Palestinians in the long term. As for the short term, the safest assumption is that 2013 will bring no real change; apartheid and arbitrary war are the twin governors of the Palestinian territories. The Palestinians will continue to suffer into the near future.  


Ahmed Moor is a master of public policy candidate at the Harvard University Kennedy School of Government

December 3, 2012 0 comments
0 FacebookTwitterPinterestEmail
Comment

One pharaoh for another

by Dalia Rabie December 3, 2012
written by Dalia Rabie

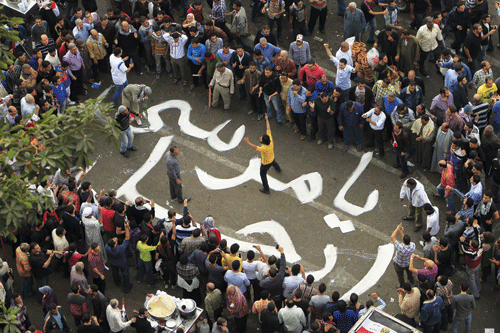
It seemed to many that President Mohammed Morsi was paving the way for his own dictatorship at the end of November when he issued a game-changing constitutional declaration radically expanding his authority, and further deepening the divide in an already polarized society. 

The seven-article declaration effectively immunized all presidential decisions from formal oversight, whether parliamentary or judicial. Following the declaration, Muslim Brotherhood offices around the country were ransacked and thousands flocked to Tahrir Square denouncing the move, while others rallied at the presidential palace in support of Morsi. As Executive went to print, both Morsi supporters in the Muslim Brotherhood and opposition figures were rallying Egyptians to the streets for mass protests.

What Morsi’s detractors see is a power grab, with articles in the declaration ominously reminiscent of deposed President Hosni Mubarak’s notorious emergency law under which arbitrary arrests were common on the pretense of protecting national security. Morsi supporters say his declaration is a necessary measure to protect the revolution and preserve national stability. 

Either way, it caps off a year beset by turmoil. The unrest of 2011 continued straight into 2012 when, on February 1, fans of the Al Masry football club attacked fans of the rival Al Ahly club in Port Said Stadium, killing 74 and injuring thousands. Accusations abounded that the security services had been complicit in the massacre. Anger amplified towards the then de-facto rulers of the country, the Supreme Council of the Armed Forces (SCAF), triggering a vicious cycle of public protests and violent repression, which resulted in at least 11 further deaths. 

The country then shifted attention to the first free election for a head of state since the end of Mubarak’s 30-year autocratic rule. The Presidential Elections Committee, however, disqualified some of the most prominent candidates mid-campaign, spurring another round of protests that left at least 10 dead when Salafi candidate Hazem Salah Abu Ismail was barred from running.

SCAF then weighed in, dissolving parliament — based on a Supreme Constitutional Court ruling that the 2011 parliamentary elections were unconstitutional — and then issuing a constitutional declaration broadening its powers and stripping the president’s office of much of its executive authority, only hours before the preliminary election results were announced. Somewhere in the middle of all this, Mubarak ‘awoke’ from a questionable coma to begin serving a life sentence in prison. All this, on top of an ailing economy, lax security and widening fractures between the country’s different factions. 

Sadly, hopes of seeing old regime elements purged from Egypt’s different institutions after Morsi took the presidential oath were short-lived. While among his first orders of business was to replace Hussein Tantawi, head of the armed forces, and the chief of staff, Sami Anan, as well as to cancel SCAF’s constitutional declaration, these ‘bold moves’ were seen by many as the outcome of closed-door deals guaranteeing SCAF’s ‘safe exit’.

Morsi has since faced a series of domestic crises — the most painful of which was a bus crash south of Cairo that took the lives of 49 schoolchildren in early November — to which he was generally seen to have reacted poorly, and he has largely failed to live up to the ambitious 100-day program he set for himself. 

Even some of the most basic human rights and standards of transparency, which were expected to take hold after the revolution and set the new Egypt apart from its predecessor, still seem out of reach. Human rights groups criticize the current government’s unwillingness to abandon repressive tools and guarantee citizen rights in the draft constitution. A report prepared by El Nadim Center for the Rehabilitation of Victims of Violence, assessing Morsi’s first 100-days in office, says that arbitrary arrests, torture and ill-treatment of citizens continued unabated. 

Morsi’s recent declaration, however, does reopen investigations into the crimes against protesters last year. This, on top of foreign policy successes — most notably helping to broker the ceasefire which ended Israel’s recent assault on Gaza — are among the new president’s few shining achievements in the eyes of Egyptians. Thus, with the second anniversary of the January 25 Revolution approaching, many wonder whether the shadow of another pharaoh looms over Egypt. With little positive change materializing on the ground, the same chants will likely echo through Tahrir Square in future months, with people still demanding “bread, freedom and social justice.”


Dalia Rabie is a Cairo-based journalist


December 3, 2012 0 comments
0 FacebookTwitterPinterestEmail
Economics & Policy

Powering the grid

by Georges Pierre Sassine December 3, 2012
written by Georges Pierre Sassine

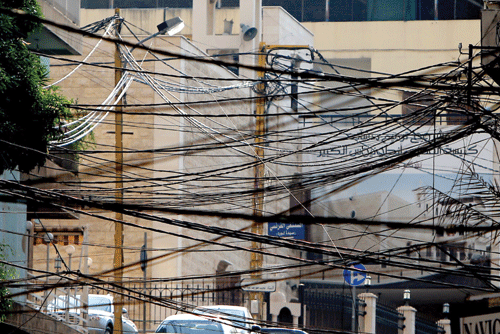
Rolling blackouts have become a symbol of the political crisis affecting the Lebanese government. According to the World Bank, Lebanese citizens incur on average 220 interruptions of electricity per year, which is the worst performance in the Middle East.

Today, electricity production stands at around 1,500 megawatts (MW) while demand exceeds 2,400MW at peak times, resulting in rationing cuts from between 3 to 20 hours a day, depending on where you are in Lebanon. Although the government signed a $360 million deal to lease electricity-generating barges from a Turkish company in July, which is expected to generate 270 MW, this will mainly offset losses as restoration works are carried out on existing power plants. 

Building a few facilities to bolster generation capacity should not be too challenging, knowing that China builds plants at the rate of one per month. Instead the problem lies in the sector’s governing system: Lebanon’s electricity sector is dominated by the state-owned Électricité du Liban (EDL), which has thus far proven inept in addressing the country’s energy shortfall. 

Moving forward, solutions to Lebanon’s electricity crisis are constrained by a limited government budget, a heavily subsidized electricity sector, low collection of electricity bills, an ageing infrastructure, human resources challenges and various interest groups resisting change.

Politicians are discussing various options, including different models of privatization and even the decentralization of Lebanon’s power generation. The fundamental debate drills down to two key questions. The first is a choice of regulation versus deregulation, which addresses the degree of government involvement in Lebanon’s electricity sector. The second is whether electricity generation should be centralized or decentralized.

These choices are in line with the debates occurring today in the global energy system. As such Lebanese policymakers can learn from the successes of others and adapt them to local conditions.

Regulation versus deregulation

The electricity sector’s restructuring has featured on the Lebanese government’s agenda since 1998 when a revised electricity law emphasizing privatization was first proposed. Following that an electricity decree was passed by parliament in 2002, more than 60 consultant reports were prepared, and the Council of Ministers, Lebanon’s cabinet, adopted different policies in 2002, 2006 and 2010. But very little progress was made on implementing any of these initiatives due to disagreements across the political spectrum around privatization. Some believe that utilities are the business of the government, while others argue for different forms of private sector involvement — spanning from full privatization to various models of public-private partnerships.

The truth is that in Lebanon some form of private sector participation is inevitable. More than 20 percent of the country’s electricity needs are already covered by private generation. Due to crippling public debt, the Lebanese government cannot single-handedly provide the required investment to reform the sector. Complicating matters, any plans to directly privatize EDL would be difficult to implement in the short to medium term, as private investors would be reluctant to invest before operational and managerial capacities are improved.

As Lebanese policymakers continue their deliberations, they seem to be drawing little from other countries’ experiences. The fact is that the electricity industry in many countries has seen a movement from heavy state involvement towards a greater reliance on market processes. The main rationale being that competitive markets raise investments, improve efficiencies and lower electricity prices.

However, the evidence on the success of electricity reform is mixed. In countries such as the UK, Australia and Chile, liberalization reduced electricity prices by as much as 35 percent. Yet, deregulation caused, for example, Sweden’s electricity prices to spike to one of the highest in Europe. The key lesson is that deregulation’s success depends on proper design and implementation of competition laws. Getting market structure right at the opening of new power markets is crucial for the success of any electricity reform; this requires a deep understanding of sophisticated regulation and market dynamics in order to be effective.

Thus, as Lebanese policymakers consider various options for private sector involvement they need to understand the requirements to properly design and implement such a transition. Failure could lead to deteriorating electricity provision and higher prices.

Centralization versus decentralization

Another proposal put forward by Lebanese politicians suggests a decentralized electricity sector. The Ministry of Energy and Water would cede control to regions or municipalities. Supporters of such an initiative believe it will help tackle corruption, reduce political bickering and improve governance. However, this raises political sensitivities as some fear that regional electricity production could lead to political decentralization and, in a worst-case scenario, to the countries’ undeclared partition.

In a centrally planned system, electricity is produced at large generation facilities, transmitted and distributed to millions of consumers over large geographic areas. It achieves economies of scale, and has been successful in providing consumers with a continuous and reliable flow of electricity. However, today the trend is reversing. Priorities have shifted, and the conditions that created centralized systems no longer hold true.

Renewables and distributed technologies emerged and are becoming more cost competitive, while policymakers’ concerns are increasingly focused on climate change and energy security challenges. This has driven energy planners in the EU and other nations to consider the transition from centralized to decentralized energy systems.

However, decentralized energy systems do not come without their challenges. Technical and engineering challenges abound when integrating large shares of distributed generation into the grid, and could adversely impact the protection and safety of the electric network.

Scoping the map, degrees of decentralization vary from country to country. Brazil has a strong centralized electricity system, whereas Canada’s is decentralized. India and Australia are currently transitioning from a decentralized to centralized structure. There is no unanimity on a universal model. Each provides different benefits and challenges, and needs to be assessed within the local context. In Lebanon, however, the motivation behind decentralization remains solely political and fails to account for technical, economic, environmental and energy security dimensions.

In its current form, Lebanon’s electricity sector already has some components of a hybrid centralized and decentralized model. EDL provides only 75 percent of the country’s electricity needs through six large, centrally controlled power plants; the rest is supplied through a network of small-scale backup generators. The only loophole is that these private generators are technically illegal and as such are not integrated into a wider regulated system.

A pragmatic approach would entail the Lebanese government leveraging the existing infrastructure of private generators across the country and adopting a policy of cooperation and coordination in the medium term, recognizing its inability to fully cover Lebanon’s electricity needs overnight.

In the longer run, a hybrid system combining the best attributes of both the centralized and decentralized structures is possible. It is a matter of finding the appropriate mix that best suits Lebanon and the political will to implement it.
In conclusion, some form of private sector participation in Lebanon’s electricity sector is inevitable under government oversight. But the success of public-private partnerships will be heavily linked to the design and implementation of competition laws. This is particularly pertinent in Lebanon considering existing draft anti-trust and competition laws have been left unimplemented for years on government shelves.

A realistic approach would also require the government to synchronize and leverage existing private generators.

This is a stopgap solution until the most suitable mix of central and decentralized structure for Lebanon is agreed upon. However, this proposal and any other attempt to reform Lebanon’s electricity sector can only be meaningful in the presence of strong political will.
 
Georges Pierre Sassine is an energy policy expert and holds a master's degree in public policy from Harvard University's John F. Kennedy School of Government. He writes about Lebanon's public policy issues at www.georgesassine.com

December 3, 2012 0 comments
0 FacebookTwitterPinterestEmail
Finance

The uncomfortable gaze of Uncle Sam

by Maya Sioufi December 3, 2012
written by Maya Sioufi

Lebanese banks had their fair share of challenges to deal with in 2012 : a stagnant economy; the ongoing turmoil in neighboring Syria; increased scrutiny from the United States; increased regulatory requirements; America’s upcoming Foreign Account Tax Compliance Act (FATCA); the anti-Iranian lobby urging foreign institutions to drop their holdings of Lebanese debt; cyber attacks on Lebanese bank accounts, and the list goes on.

These challenges have not left the sector unscathed. Deposits and assets of the sector, while still up in 2012, are growing nowhere near the rates enjoyed a few years ago. End-of-year profits are expected to drop in 2012 with several general managers expecting falls at double-digit rates.

The big nasty

First and foremost on bankers’ list of concerns is the ongoing unrest in Syria and its spillover into Lebanon and its economy. There are currently seven Lebanese banks present in Syria with total assets standing at $5.2 billion as of the end of June 2012, though this amounts to a meager 3 percent of Lebanese banks’ balance sheets. Profits generated from these Syrian affiliates stood at $30 million for the first six months of the year, just below 4 percent of the total sector profits. To stay on the safe side, banks allocated $293 million in collective provisions — held against unidentified losses on a portfolio of loans — in the first nine months of 2012, after allocating $232 million in 2011. “Our profits in Syria are allocated as provisions; there are no contributions from Syria to our earnings,” says Freddie Baz, chief financial officer of Bank Audi.

But the impact of Syria’s ongoing chaos on Lebanese banks goes beyond their presence inside Syria. With international sanctions placed on Syria, US regulators have kept a close eye on Lebanese banks to ensure they don’t become a funnel for Syrian cash. Officials from the US treasury have visited Lebanon on numerous occasions in 2012: US Deputy Secretary of the Treasury Neal Wolin met with Lebanese government officials in September and David Cohen, the Treasury’s under secretary for terrorism and financial intelligence, warned banks back in May to be extra cautious when dealing with Syrian transactions, saying, “We want to be as careful as possible that the regime, its cronies and its allies that may be trying to shield their assets might not be able to do so.”

Several experts Executive spoke to said they believe that the international scrutiny imposed on the banks is excessive. “I believe the business of banking is changing dramatically; we investigate deposits rigorously as if in a police state,” says Anwar Jammal, chairman of Jammal Trust Bank. “A lot of US and European banks have made far bigger mistakes and gotten away with a slap on the wrist, keeping in mind that to err is only human.”

He adds that his bank has just finished implementing a new anti-money-laundering software program that makes the 17 different ways of spelling the name ‘Mohammad’ into one word. “If you spell it in one way or one of the 17 different ways, it will tell you it is ‘Mohammad’,” explains Jammal.

“There was an accident or two in Lebanon but the scrutiny is exaggerated,” says Rami el-Nemr, chairman of First National Bank.  “There were lots of rumors; it became the talk of the town. I think it was not fair for the banks.”

FATCA fears

For a segment of the Lebanese population, this scrutiny is bound to get personal. The upcoming FATCA requires all foreign institutions to disclose the holdings of their clients with a US nationality, or face paying hefty penalties; this has already led several local banks to lose business. “We have already lost some clients but we have to deal with FATCA and Lebanese banks have to deal with it too,” says Jean Riachi, chairman of FFA Private Bank. The total number of Lebanese Americans with accounts in Lebanon is hard to come by, but several chairmen of Lebanese banks say it is a small percentage of total accounts — “definitely single digit,” according to Saad Azhari, chairman of Blom Bank.

A sigh of relief came in October when the implementation of FATCA was delayed by a year, until January 2014, giving foreign banks additional time to set up the software and teams necessary to comply. And comply they must. With two thirds of the sector’s balance sheet in dollar deposits, “the US rule is ‘my dollar, my rule’; you want to deal with the US dollar, you have to abide by my rule,” says Bank Audi’s Baz.

Online exposure

The compliance department is not the only one receiving more bank resources. The information technology (IT) department has seen its budget buffed up in order to deal with a different type of threat: a cyber one. In August, a cyber virus dubbed ‘Gauss’ attacked bank accounts in the Middle East. Kaspersky Lab, a Moscow-based IT security vendor, discovered the virus and claimed it began operating in September 2011, attacking some 2,500 machines in the Middle East, of which 1,600 were in Lebanon. “It is a lot more destructive than war,” says Jammal. “It has the ability to wreck havoc around the world. It mushrooms and it is something that is very serious and we take it very seriously.”
It’s been a rough ride for banks in 2012 with challenges continuing to pile up. The prospects for 2013 don’t look much rosier with the Syrian horizon still unclear, and with “a lot more open issues in the region; if I had to hierarchize what does not make me sleep at night, it’s the Israeli threats on Iran which can generate a hell of a lot of problems everywhere,” says Baz.

The banks, having survived Lebanon’s history marked with strife and unrest, are accustomed to dealing with challenges, and know how and when to reinforce the fortress.

“Given the resilience of the Lebanese people, the banking sector will come through ok, inshallah,” says Pik Yee Foong, chief executive of Standard Chartered Bank Lebanon. 

December 3, 2012 0 comments
0 FacebookTwitterPinterestEmail
Comment

The Islamic divide

by Moe Ali Nayel December 3, 2012
written by Moe Ali Nayel


It has been a year of dreaming dangerously for some Lebanese Sunnis who see the perpetually impending downfall of Syrian President Bashar al-Assad as an opportunity to reassert their historical dominance over the country’s Shia.

February’s escalation of the long-running feud between pro-Assad Alawites and anti-Assad Sunnis in Tripoli set a polarizing tone for 2012; tensions spilled south with anti-Hezbollah Salafis protesting in Saida. This came almost concurrently with former Prime Minister Saad Hariri’s self-imposed exile from Lebanon. Hariri, leader of the country’s largest Sunni political party, the Future Movement, first announced his departure was for personal safety; later he tweeted that he was busy managing his overseas businesses.

Hariri’s departure left a vacuum and a new Sunni personality soon emerged: Sheikh Ahmad al-Assir, whose posters have been slowly replacing Hariri’s in Sunni strongholds across Lebanon. A Salafist preacher, Assir first garnered widespread media coverage in March by staging a rally in Downtown Beirut, giving him a national platform for his extremist, anti-Shia sectarian rhetoric — a stark contrast to Hariri’s more ‘moderate’ line.

Militant Sunni anger then erupted again on May 20, when Sheikh Ahmad Abdel Wahed, a prominent anti-Assad Sunni cleric, was shot dead after an altercation at a Lebanese army checkpoint in North Lebanon. That night masked gunmen in Beirut’s Sunni enclave of Tariq El Jdeideh opened fire on Lebanese Army soldiers, and clashes elsewhere in the country, spurred by enraged Sunni partisans, left two people dead and 18 wounded. 

Two days later, a Syrian opposition group kidnapped 11 Lebanese Shia pilgrims in Aleppo. Family members and friends protested in Beirut’s streets, with widespread retaliatory attacks reported against predominantly Sunni Syrian laborers. 

Assir’s vitriolic attacks against Lebanon’s two most prominent Shia leaders — Hezbollah Secretary General Sayyed Hassan Nasrallah and Amal leader Nabil Berri — on Al Jadeed TV provoked Shia thugs to assault the station’s offices on June 25. After burning tires out front and firing shots at the building, they were arrested, setting off protests in Shia neighborhoods. 

In August the Free Syrian Army posted a video of a beaten Hassan Salim al-Meqdad, who they had captured in Damascus and accused of being a Hezbollah member working for the Assad regime. In response, the Meqdad clan began a wave of kidnappings targeting Syrians in Lebanon, specifically Sunnis. 

The Syrian conflict’s impact on sectarian identity in Lebanon is profound. Many Lebanese Sunnis view the revolt, especially since it became an armed conflict, as the uprising of their Syrian brethren against an oppressive Alawite regime allied with Shia interests. On the other side, many Lebanese Shia see the Syrian conflict as a foreign-backed conspiracy and, should Assad fall, they worry about being regionally isolated in a sea of Sunni vengeance. The Saudi, Qatari and Kuwaiti funding that has poured in to the Syrian opposition since it took up weapons has only entrenched these sectarian characterizations.

When Sunni intelligence chief Wissam al-Hassan was assassinated in a car bomb in Beirut on October 19, sectarian animosities hit fever pitch across Lebanon. Angry Sunni protesters accused Hezbollah and Syria of the killing, demonstrators attempted to rush the Grand Serail (the administrative headquarters of the Lebanese cabinet), road blocks isolated Beirut from the rest of the country, masked Sunni gunmen manned checkpoints and demanded identification cards to identify Shia motorists, while belligerents in Tariq El Jdeideh fired rounds toward Shia neighborhoods in Beirut’s southern suburbs. 

This aggression saw little response from the Shia side, however — a show of remarkable restraint that may have saved the country from a slide back into civil war.

In November, clashes erupted again in Saida, when Assir issued an ultimatum to Hezbollah to take down posters commemorating the Shia holiday of Ashoura. Attempting to follow through on the threat, Assir and supporters confronted Hezbollah members in the neighborhood of Ta’amir; the ensuing clashes left three dead. In response to the incident, Hezbollah’s Nasrallah called for patience and restraint, urging Sunnis and Shia to remain vigilant of sectarian incitement, while Assir announced the formation of an armed “resistance brigade” in Saida, then later reneged.

Thus, 2012 nears a close with the gulf between Lebanon’s Shia and Sunni communities only widening. This hate between communities has been stoked by the likes of Assir, who has ridden its wave to take himself from obscurity to prominence. Unfortunately, this terrible tide shows no sign of receding as we move into 2013.

Moe Ali Nayel is a freelance journalist based in Beirut

December 3, 2012 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 298
  • 299
  • 300
  • 301
  • 302
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE