• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Banking & Finance

IPO Watch – A Saudi summer

by Executive Staff September 3, 2008
written by Executive Staff

The leader in Middle Eastern primary market action in August came — as has been the case for several other months of this year — from Saudi Arabia. The initial public offering of Methanol Chemicals Co (Chemanol) was worth $193 million and accounted for 79% of the aggregate amount of $245 million available last month in IPOs around the region. Different to numerous other recent IPOs which were green-field ventures, the Chemanol flotation originated from a company that has a substantial history of manufacturing activity — it was established in 1989 — which sought a flotation to obtain new capital for corporate expansion.

Its area of activity may be less splendorous than Islamic banking, but Chemanol allocated 70% of the offering to retail buyers, demonstrating confidence that it would be able to get retail investors interested in its offering at a price of SAR 12 ($3.2) per share, which included an offering premium of SAR 2 ($0.53). First results of the IPO showed that demand indeed reached high, with subscriptions totaling $1.1 billion.
Last month saw four other smaller IPOs seeking to raise between $7.8 million and $16.3 million in capital, all in Jordan. Two firms in the real estate sector each offered slightly less than half of their equity to investors; the other two offerings came from a credit card and an investment company.
A total of five companies started trading around the region in an environment of traditionally low August volumes, with international markets additionally subdued by worries over volatile energy markets, unending financial crises and recession talk. The five firms are Sohar Power in Oman, Tunisian conglomerate Poulina Group, Astra Industrial Group on the Saudi Stock Exchange, Jordanian real estate firm Amwaj Properties and the UAE’s Dar al Takaful insurance company.
Even as the last month was tough on MENA bourses, all five debutants had a decent or good start, achieving first-day gains of 12% to 437% — the latter feat was accomplished by Islamic insurer Dar al Takaful on the Dubai Financial Market and it underscores the current comparative edge of Arab bourses in the emerging markets theater. The BRIC (Brazil, Russia, India, China) markets’ top summer IPO of China South Locomotive, which raised $1.49 billion in August on the Shanghai and Hong Kong stock markets, managed a 58% gain on its first trading day in Shanghai, but disappointed in Hong Kong with a measly 1% burp. India’s Reliance Power, which has been battered on the bourse since its Jan 2008 IPO, in August scrapped the IPO of a telecoms equipment subsidiary, Reliance Infratel.

Heavyweight Arab IPOs
Although Middle Eastern investors were expected to have their minds a little less on sprinting after shares and a little more on summer diversions, two well-known Arab companies chose August to start large rights issues that will extend into September. Big money was sought by regional telecommunications operator Zain Group through its $4.5 billion rights issue for a 75% capital increase on the Kuwait Stock Exchange, which opened on August 17 and will run until September 18. A second notable rights issue was that of Egypt’s Al Ezz Steel. The company, one of the country’s leading manufacturers and an important player on the regional materials scene, announced on August 7 that it would seek to triple its share capital by offering almost 365 million new shares between August 26 and September 25 in a rights issue worth $341 million.
Also a September timeframe was selected for the $98 million telecommunications industry IPO of Kuwait’s third mobile operator. Kuwait Telecommunications Co, which was formally established in July as a company with 26% stake holding by state entities and 24% ownership by Saudi communications group STC, is offering 250 million shares, representing 50% of its capital, for subscription at a share price of $0.39.
Much more is expected for September and for the fourth quarter of 2008, with travel and tourism related IPOs something to watch for. The National Air Services offering on the Saudi Stock Exchange has been announced with a size of $600 million for 30% in the company, although the subscription period has yet to be set. In October, the Al Tayyar Travel Group will look to raise $320 million, also on the SSE, while Dubai-based retail and real estate group Aswaaq is said to plan offering 55% of its equity for participation in the same month.
Media reports from Kuwait said that the Kuwait Stock Exchange’s technical committee approved listing of four new companies, including Wataniya Airlines (or Kuwait National Airlines Co), which had sold 350 million shares, for $123.5 million, through an IPO in early 2006 and intends to start operating as a luxury carrier in 2009.

September 3, 2008 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Construction – Cement syndicate

by Executive Staff September 3, 2008
written by Executive Staff

What could prompt the cooperative efforts of a Lebanese bank to engage a French building materials company and 15 additional regional and international financial institutions from all over the globe and seal a $380 million deal? Apparently, cement is the glue behind one of largest private financing syndicates for industrial projects in the Levant.

“The current construction boom in the Middle East which has increased the consumption of cement, combined with an acute shortage in the region, has driven cement prices to unprecedented levels. Our region, and Syria in particular, has a shortage of about 4 million tons per year,” explained Ramzi Saliba, General Manager of Bank Audi’s corporate banking division. The Syrian cement deficit comes alongside an ongoing housing crisis and lack of raw materials, a result of decades of nationalization and the centralized economic policies under the ruling Baath Party.
For decades cement production remained a state monopoly in Syria. However, recent circumstances have prompted the Syrian government to open the sector to private investors, and to compensate by introducing a limited liberalized economy. “Contrary to common belief, Syria has modernized and liberalized its laws considerably in the last few years,” Saliba confirmed. “That, coupled with the explosion in construction has made cement a very attractive sector for Bank Audi, now and for years to come.”
Bank Audi, coordinator and leader of the syndication, is among the first banks to set up in Syria after the government allowed private banks five years ago. “Private banking in Syria is still in its infancy stages, and it is a natural place for Lebanese banks to take hold of opportunities, more so than any other country. We know the market well, we know the people well, many large Syrian names and corporations have been the clients of Lebanese banks for 40 years, so we know the business very well,” Saliba said.
As far as Bank Audi’s interest in putting together a bridge loan in Syria, Saliba outlined that, “This deal was in line with the regional expansion strategy of Bank Audi, helped by several factors. The main reason was the shying away of larger international financial institutions on large deal because of the economic crunch that’s taking place in the US and Europe. That gave us a really great chance.”
Capitalizing on the window of opportunity, Bank Audi pursued Egypt’s Orascom Construction Industries. Saliba detailed the progress of the operation: “We had started discussions with Orascom Construction, OCI, and in the interim, Lafarge bought OCI’s cement business. We asked them to carry on with the discussions, and they saw how far into the deal we’d gotten, so they continued working with us; it worked out.”
Global leaders in building materials, French cement maker Lafarge boosted its market position to No. 1 in the region after acquiring the cement business of Egypt’s Orascom Construction Industries at the close of 2007. Having secured the deal with Bank Audi for its subsidiary, Syrian Cement Company, Lafarge Group will now continue its expansion in the Middle East with the setup of a greenfield cement plant near Aleppo.
The new plant is scheduled to begin production in 2010, and will have the capacity to generate 2.9 million tons per annum. This should help put Syria on its way to meeting its cement demands, which are expected to grow drastically from 7 million tons per year today to around 18 million tons in the next three years due to the surge in real estate, construction, and tourism development.
The considerable size of the bridge loan, which stands be replaced after 18 months by a longer-term loan, and more importantly the union of so many diverse investors serve as clear indication of Bank Audi’s notable regional role. “It’s the first such transaction done by a Lebanese bank, in terms of region or even international financing opportunities,” Saliba said. “It’s the first, and certainly not the last for Audi, and I hope for other Lebanese banks who may be contemplating an effective regional role.”

September 3, 2008 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Private equity – An absence of exits

by Executive Staff September 3, 2008
written by Executive Staff

On any given day, a scour of Middle East business news reveals that private equity in the region is ‘hot’, owing to favorable conditions at the macroeconomic level or data on fundraising and investment, which seem to be getting bigger. Watchers of the asset class meticulously track which funds are looking for which companies and which opportunities and sectors are attracting the most private equity. The asset class’ behemoths and large-sized deals in infrastructure and other industries dominate headlines. On the surface, the coverage of the asset class looks healthy.

However, the component of private equity which is less covered than capital raised and investments is the arm of the asset class which offers the best indicator of performance, the exit. Without appropriate exit data, it has been difficult to see what trend is following the explosive growth in the other sub-data available on private equity, beckoning the question: whither to the exits in Middle Eastern private equity?
A dearth of evidence continues to pervade estimates, but some figures have indicated that only 5-10% of private equity deals in the Middle East and North Africa (MENA) region have been exited. With private equity comprising 45% of aggregate investment in the United Arab Emirates (UAE) and 35% in Saudi Arabia, the relation between money invested and return on investment can indicate several things that a purely deal-side analysis cannot, including the asset class’ performance, potential pitfalls, and lagged performance to see if larger funds are or are not commensurate with larger internal rates of return (IRRs), the derivate used in calculating the success of funds, with ranges at 15-20% on the lower end and up to 100% in more lucrative examples. Because of some poor performance in regional bourses, private equity houses seem to be holding investments for a bit longer, waiting for appropriate exit options. With funds raised, investments complete and deals outstanding, limited partners (LPs) are going to starting demanding a return on their investment within the appropriate bounds of the fund timelines.

M&A doesn’t count
Distinct merger and acquisition (M&A) activity lies on a separate sheet from pure private equity. In M&A, a buyer bids and acquires firms to enlarge businesses both horizontal and vertically. In the case of horizontal M&A, a firm might be a competitor, but vertically, the acquired firm is a complementary entity. In the instance of a horizontal M&A transaction, a hotel chain might acquire a competitor to enlarge business or grow operations in new markets, be they different countries or a higher or lower-end of the business. In a vertical M&A transaction, the hotel chain might purchase a food services group to bring more of the hotel’s daily operations in-house. The M&A as a distinct transaction differs from the bread and butter type of private equity transaction where firms are first acquired and later exited rather than incorporated as part of a firm’s main business lines.
What then do the longer partnerships between private equity players and firms indicate? There are several speculative guesses, including the disparity in vision which could entangle maneuvering by management, making a firm reluctant to realize an exit. Another possibility is the poor exit environment, while still another is the possibility that private equity funds backed by institutional investors such as sovereign wealth funds (SWFs) are bound to the wishes of these LPs and blurring the pure business thought of profit and yielding to the ‘what’s best’ scenario for firms under management.

Trade sales
Some private equity exits have come in the form of the trade sale. This type of exit is viable for the region’s numerous family-owned firms, who would like to retain control after beefing-up the best practices instilled by a private equity firm. In June, 2008 the Foursan Group exited the Abdali District in Jordan to new investors via a trade sale, while Abraaj Capital exited both EFG-Hermes and the Maktoob Group via this route in 2007. Additionally, Injazat Capital exited its stake in Atos Origin Middle East, through a trade sale exit for the GCC-based technology firm.

Secondaries
The secondary market has given a new dimension to the private equity business. It is heralded as a way to unload a firm to another private equity player and will doubtlessly be used while more traditional exits like the initial public offering (IPO) route remain weak. The largest secondary transaction was Citadel Capital’s exit of Egyptian Fertilizers Company in June 2007 and while others have not been reported as secondary sales, the private equity to private equity nature of an investment is one way of gauging the exit type.

Strategic sales
The strategic sale of a firm to a related firm covering the same or similar industries is another possibility for MENA firms and might be the destination of most unreported or disguised exits. In June, the Foursan Group exited Arab Orient Insurance Co., a Jordanian insurance provider, to Fairfax Holdings, an insurance group looking to beef up the scope of its services.
Fairfax Holdings is a Western firm that acquired Arab Orient Insurance Co. for one possible reason: to expand Fairfax Holdings reach into a new market in the MENA region. With an ever growing population consuming ever more goods, firms servicing large markets with great potential will attract the likes of more Western firms looking to establish an arm in the region.

IPOs
The most traditional of exit options for private equity firms — the IPO — has not be used by firms reticent to face the valuation of a firm in the open market. According to Private Equity International’s survey, 33% believe that valuation and control are the greatest threats to the growth and development of the private equity industry in the Middle East while 25% believe it is non-initial public offering exits. In 2007, securities markets in the MENA region mimicked the situation globally and reported fewer groups in 2007 than year to 2006, when the turmoil on capital markets began. Although Q1 2008 performance remained poor, the situation as a whole for 2008 remains positive. For instance, the Saudi Arabian stock exchange has grown from a low in July 2007 to remain up over 25%. Regional bourses have followed similar trends.
However, a less sanguine conclusion is drawn vis- à-vis regional inflation rates, which can deteriorate investments and the value of companies choosing to list restructured operations now. In an approximated situation where capital market indices are achieving 20% annual growth in capitalization figures, double digit inflation can prick the balloon of optimism.

Large time horizons
With private equity firms tabling the immediate or traditional exit, the business is taking on longer time horizons for investments. The asset class’ main driver in the MENA region is currently infrastructure, which, by the nature of the industry, involves longer holding periods between investment and exit.
Initially evoked to describe pipes, roads, and ports, the term ‘infrastructure’ has come to include a myriad of sub-industries, including downstream industries and suppliers as well as networks involved in social infrastructure, namely the hospitals and schools being built to care for the populations of new cities and the growth dynamics associated with large Arab families.
Tertiary educational institutions, from new universities to research centers, are additionally accommodating the jobs to be demanded when the under-18-year-olds turn of age. For 51% of those surveyed by Private Equity International, infrastructure will attract the most investment interest in the next twelve months, followed by energy in a distant second at 20%. The two industries involve longer time horizons owing to the scale of deals as well as the timeline to realize results.
Private equity fits into the equation by its ability to recapitalize the infrastructure industry. Statistics have accounted for infrastructure projects comprising over 60% of new funds raised by regional private equity firms. New funds are sprouting up to bolster the demand. Al Khayyat, Rasmala, and RHT recently acquired a 13% stake of Taaleem, an educational specialist, which increased Al Khayyat’s stake in the firm to 25%. Taaleem is not the only education firm seeking or gaining capital to finance growth plans. Online educational resources, private educational institutions, books, and universities have all benefited from seeking out private equity growth capital, especially as many are battling for regional supremacy, moving beyond conquering just Riyadh and Jeddah to include operations in Abu Dhabi, Kuwait City, and Manama.
With longer holding periods and new industries in which private equity players are investing, the asset class has taken on a flavor distinct to the region. Two reasons come in play to understand this dynamic. The first includes the aforementioned style of partnership in the region, with LPs consisting of SWFs in addition to individual fund backers. Sovereign wealth does not expect the same returns on investment and deals can be political to an extent in that GCC SWFs partner with MENA-centric private equity houses to strengthen the business climate in the region. An additional factor less thought of is the need for strong financial services houses. Because private equity is the quintessentially efficient type of investment, the savoir faire of industry experts is useful in structuring the longer-term outlook of firms involved in infrastructure or energy.

September 3, 2008 0 comments
0 FacebookTwitterPinterestEmail
Editorial

Corporate social profitability

by Yasser Akkaoui August 13, 2008
written by Yasser Akkaoui

With this month’s special report, Executive has taken root in the CSR orchard; it has demonstrated that it is the business magazine that monitors and evaluates what is arguably the most dynamic, worthy and important weapon in today’s corporate arsenal: that of giving back to the community or developing initiatives that make our lives healthier, cleaner, relevant and enriching.

Businesses have recognized that, by allying themselves to good causes they can raise their profile, improve their image and shape their identity. They can fight back at accusations of environmental damage by going green, both in the office and in the community; they can fight back at accusations of exploitation by lobbying for trade reform, youth initiatives and working to make better lives for their workforce; and they can, by their CSR programs, bring together civil society and the private sector to appraise how governments are running our lives. In short, the corporate world is finding its conscience and the good news is that it is actually improving the bottom line.

Still, in every blue sky there looms a cloud. Last month’s adventurism by Russia not only trod on Georgian sovereignty, it sent out a dangerous message to those states who might see the so-called rescue mission into Georgia as a template upon which to build their own regional aspirations. Such a path of action would involve taking sides in what could easily turn into a Cold War Lite. The last time the Arab World took sides (with the USSR incidentally) was in 1967, a period in which the USA had not yet committed itself to any Middle East policy, though was forced, by default, to embrace an isolated Israel. History has a nasty habit of repeating itself but we can learn from it too and today, the Middle East, which has the potential to enter a golden age of commercial prosperity, should not be tempted to once again take sides by rekindling old habits.

Finally, as the Lebanese summer season draws to a close, we cannot but say a word about the thousands of expatriates who have descended on Beirut for a well-deserved break. Yes, it was difficult to find a good table at short notice, but the simple fact of the matter is that, not only have they driven our economy for the past year, their achievements in the region have set a benchmark of professional excellence and put a premium on Lebanese human resources. We have always maintained that Lebanon is the sum of its private sector endeavors both at home and abroad.

It would be a hard case to argue against.

August 13, 2008 0 comments
0 FacebookTwitterPinterestEmail
Financial Indicators

Global economic data

by Executive Staff August 13, 2008
written by Executive Staff

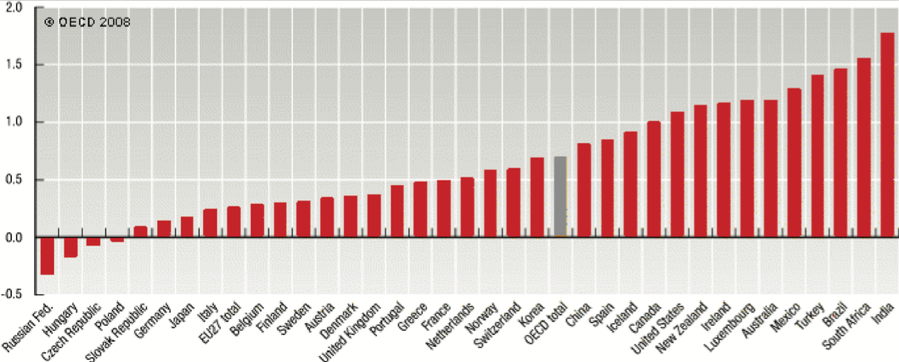
Population growth rates

Average annual growth in percentage, 1993-2006 or latest available period

In 2006, OECD countries accounted for 18% of the world’s population of 6.5 billion people. China accounted for 20% of this number and India for another 17%. Within OECD, the United States accounted for 25% of the OECD total, followed by Japan (11%), Mexico (9%), Germany (7%) and Turkey (6%). Between 1993 and 2006, the population growth rate for all OECD countries averaged 0.7% per annum. Growth rates much higher than this were recorded for Mexico and Turkey (high birth rate countries) and for Australia, Canada, Luxembourg, Ireland, New Zealand and US (high net immigration). In the Czech Republic, Hungary and Poland, populations declined from a combination of low birth rates and net emigration. Growth rates were very low, although still positive, in Germany and the Slovak Republic. The population growth of OECD countries is expected to slow down in the coming decade. Until the middle of this century, the population of OECD countries is expected to grow by less than 0.3 per cent per annum. Total fertility rates have declined dramatically over the past few decades, falling on average from 2.7 in 1970 to 1.6 children per woman of childbearing age in 2005. By 2005, the total fertility rate was below its replacement level of 2.1 in all OECD countries except Mexico and Turkey. In all OECD countries, fertility rates have declined for women at younger ages and increased for women at older ages because, on average, women are postponing the age at which they start their families.

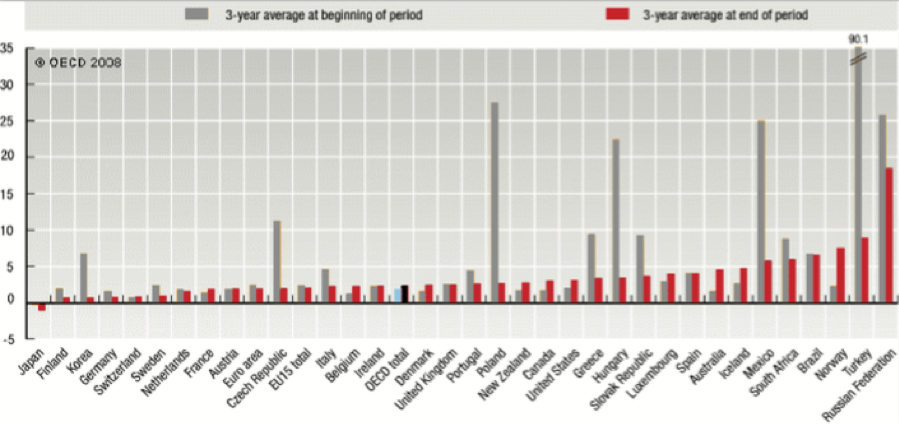
GDP defaltor

Average annual growth in percentage

Between 1993-2006, OECD inflation was lowest in 1999 at 1.2%. It then gradually increased to 2.5% in 2006. The average annual inflation over the last three years was below 5% for all OECD countries except Norway, Mexico and Turkey. The volatility in the Norwegian GDP deflator is mostly due to variations in the export prices of petroleum, and these grew very strongly over the last few years. Strong growth in the GDP deflator for Mexico and Turkey reflects general domestic inflation, though both countries have, drastically reduced their inflation from 1993-2006. At the other extreme, Finland, Germany, Korea, Japan, Sweden and Switzerland recorded average annual rates of inflation over the last three years of below 1%. Several countries (Canada, Czech Republic, Finland, Germany, Luxembourg, Norway and Switzerland) recorded deflation between 1993-2006 for one or more years, but Japan is the only country where this has been sustained over several years.

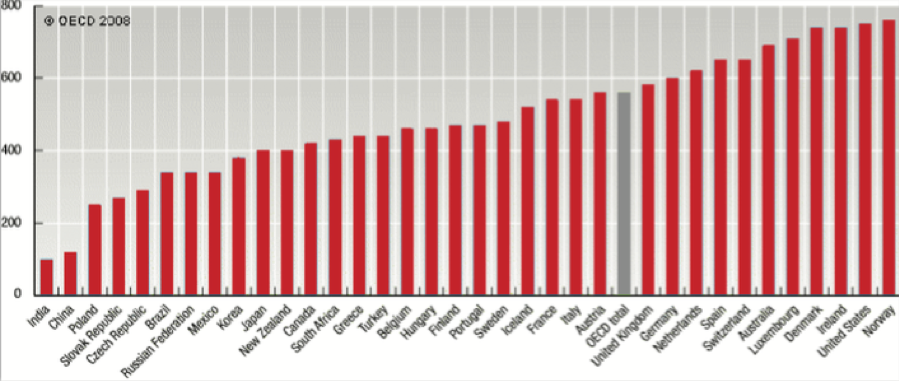
Municipal waste generation

kg per capita, 2005 or latest available year

The quantity of municipal waste generated in the OECD area (30 countries) has been rising since 1980 and exceeded 650 million tons in recent years (560 kg per capita). Generation intensity — i.e. kilograms per capita — has risen mostly in line with private final consumption expenditure and GDP, but there has been a slowdown in the rate of growth in recent years. The amount of municipal waste also depends on national waste management practices. Only a few countries have succeeded in reducing the quantity of solid waste to be disposed of. In most countries for which data are available, increased affluence, associated with economic growth and changes in consumption patterns, tends to generate higher rates of waste per capita.

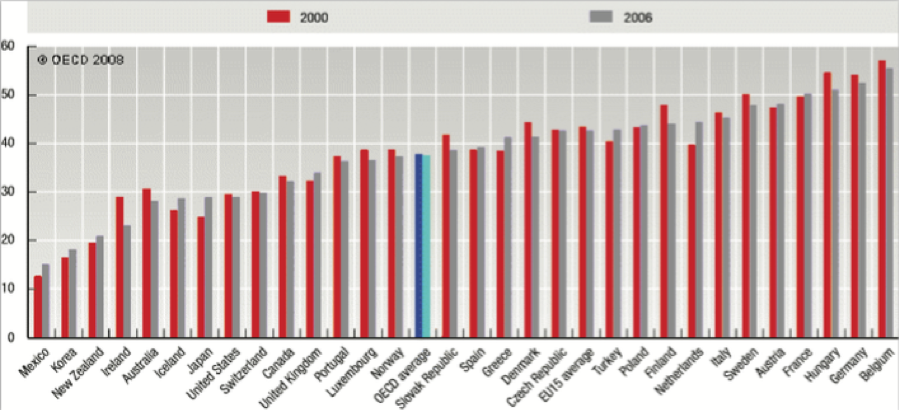
Taxes on the average worker

As a percentage of labor cost

On average, the taxes on an average worker increased until 1997 and have since declined, in both the European Union and the OECD as a whole. However, there are important differences between countries. The countries that have experienced an overall increase in the taxes on an average worker since 2000 include Japan, Mexico and the Netherlands. Countries that have experienced an overall decline include Australia, Denmark, Finland, Ireland, Luxembourg and the Slovak Republic.

August 13, 2008 0 comments
0 FacebookTwitterPinterestEmail
Financial Indicators

Regional equity markets

by Executive Staff August 13, 2008
written by Executive Staff

Beirut SE: Shuaa  (1 month)

Current Year High: 3,470.63  Current Year Low: 1,761.53

The Blom Stock Index for the Beirut Stock Exchange closed the July 25 session at 2013.55 points, down some 38 points when compared with the last close in the previous month. After climbing to a peak of near $40 per share on July 7 in reflection of a 10% dividend that will be paid out starting end of August, shares of real estate firm Solidere traded lower ex-dividend and closed at $36.01 on July 25. As politicians seemed to get something right in their negotiations in the second week of the month, the economically hopeful formation of a new cabinet drove the BSI to a new record high of 2,119 points. There was a bit of a hangover caused by renewed and probably incessant political squabbles later in the month but on the balance, July underscored that political improvements are the key in unlocking economic growth potentials for listed stocks and the whole economy. The central bank announced that reserves reached $15.5 billion in mid-July; a new sovereign bond issue was under preparation with the help of local and international banks as a $399 million bond neared its date of maturing on August 6.

Amman SE  (1 month)

Current Year High: 5,043.72  Current Year Low: 3,003.07

Share price trends on the Amman Stock Exchange broadly pointed sideways in the review period. After shedding some points early in the month, the ASE general index fluctuated between 4,500 and 4,700 points and closed the July 24 session at 4,711.36 points. This volatility in the general index was influenced largely by fluctuations in industrial stocks. These fluctuations in turn were attributed mostly to plans for introduction of a capital gains tax, which were withdrawn by tax authorities in mid July. The industry index, the main force in upward movements on the ASE in 2008, underperformed the market in July but ended the period at par with the general index. Insurance and services trailed the general index throughout the month while the banking sector displayed the best performance and gained 4.2%.

Abu Dhabi SM  (1 month)

Current Year High: 5,148.49  Current Year Low: 3,327.86

The Abu Dhabi General Index clung to the 5,000 points mark as the summer’s trends for booking profits and investing in individual relaxation made their impact. With a close at 5,005.70 points on July 24, the ADX index recorded a small gain that month because the exchange had a positive week at the end of the review period, after three weeks of losses. Sector indices did not report much that was worth writing home about. Energy was buoyant and real estate and telecoms also were positive on the month while banking was very close to the general index. The insurance, consumer, construction, and industrial sub-indices dropped between 0.85% and 2.53%, underperforming the general index. Real estate and energy led the gains in the last week of the review period.

Dubai FM  (1 month)

Current Year High: 6,291.87  Current Year Low: 3,968.09

Owing to a 215-point uptrend in the latter part of the period, the Dubai Financial Market’s general index had one nostril above water on July 24. The index closed at 5,437.54 points, 0.1% up from the start of the month. July thus did not alleviate the DFM’s standing in the regional performance tables for 2008; with a drop of 8.34% year-to-date, the DFM is still the second-worst performer this year in the GCC after the Saudi bourse. The sub-indices broadly confirm the downtrend: most sectors were flat or slightly negative throughout July; compared with the start of January, the transport, real estate, telecoms and utilities sector indices are down between 15 and 30%. Only the indices for insurance and materials bucked the trend and moved in positive territory with year-to-date gains of 6.4 and 13.5%, respectively. On the other extreme, however, stocks in the consumer staples category plummeted by more than 39% in July. The small sector lost half its value since the start of 2008. Jeema Mineral Water Co, which had listed earlier this year, shed 50% of its share price between June 18 and July 24.

Kuwait SE  (1 month)

Current Year High: 15,654.80            Current Year Low: 12,039.00

The Kuwait Stock Exchange had the highest index losses of any GCC bourse in July, closing at 14,887.80 points on July 24, down 3.7% from the start of the month. Pundits associated the slide, which had set in after the index reached a historic high above 15,650 points on June 24, with investor worries over potential attacks on Iran as the US and Israel deployed the verbal sledgehammer in their criticism of the ayatollahs’ nuclear theocracy. While all major sectors on the KSE weakened between June 24 and July 25, index losses during this particular period were the highest for industry (9.5%), followed by services (4.85%). The banking and insurance sub-indices, on the other hand, lost between 3% and 2% and suffered the least. When analyzing July share price movements alone, however, insurance and industry dropped between 5 and 6%, more than other sectors. Despite its loss in July, the KSE general index is still quite the looker for 2008 to date with a gain of 18.5% since January 1.  

Saudi Arabia SE  (1 month)

Current Year High: 11,895.47            Current Year Low: 7,506.45

The Tadawul Index on the Saudi Stock Exchange dipped down to 8,706 points on July 16, its lowest reading since October 2007. The SSE recovered to a close at 9,080.87 points in its July 23 session, signifying a 2.9% drop in the opening period of the year’s second half and certainly not enough to change the SSE’s situation as the most underperforming Middle Eastern securities market this year. Three sub-indices out of 15 in the SSE showed gains in the review period, namely telecommunications, retail, and industrial investments. All three major telecommunications companies, Etisalat Etihad, Zain Saudi, and STC, made gains toward the end of the review period but STC advanced the most, lifting away from a 12-months low recorded on July 16 on news of a good outlook for the Saudi telecommunications industry. Among debutants, Alinma Bank continued trading lower in the second month of its life on SSE.

Muscat SM  (1 month)

Current Year High: 12,109.10            Current Year Low: 6,423.95

The Muscat market was not to be caught by its GCC peers in July. The Muscat Securities Market general index closed the review period up 2% at 11,544.61 points on July 23 ahead of a long national holiday weekend. While the month did not see trading reach exhilarating levels, the MSM performance ahead of the other GCC bourses secured the Omani bourse’s claim to being the strongest gainer in 2008 at being up almost 28% when compared with the start of the year. Banking stocks struggled in the review period relative to other sectors; the banking sub-index closed 1.14% lower on July 23 when compared with the beginning of July. Industrial stocks, which had frequently served as drivers of the market gains in the first half of 2008, stayed married to the general index, leaving it to the services sector to outperform the general index with a gain of 4.2% on the month. The shares of Omantel were among the most watched during the month as the stock drew attention from buyers on announcements that the government plans to sell another major chunk of its 70% stake. 

Bahrain SE  (1 month)

Current Year High: 2,902.68  Current Year Low: 2,495.28

Stocks on the Bahraini bourse moved generally lower in July as the Bahrain Stock Exchange extended its losing streak into a second month. The general index closed at 2819.58 points on July 24, down 1.4% on the month and up 2.3% on the year. The sub-index for hotel and tourism companies, already the best performer among the BSE sector indices in the first half of 2008, continued to stay ahead of the market and added 3.7% in the July review period. Banking, insurance, services, and investments on the other hand moved lower last month; the investments sector gave up 2.4% and underperformed the general index the most, by a full percentage point. Al Khaleej Development Co, the BSE’s best performer this year so far, made further modest gains while the sharp slide of Arab Banking Corporation – the year’s hardest hit stock in Bahrain – appeared to be tapering out into a more stable picture (but one of a negative price to earnings ratio).

Doha SM: Qatar  (1 month)

Current Year High: 12,627.32            Current Year Low: 7,340.06

The Doha Securities Market’s general index slipped in July but switched to a sideways pattern in the second part of the month. The market closed at 11,851.02 points on July 24, representing a drop of 0.7% on the month and a retreat by 845 points from its year high on June 11. Banking stocks shadowed the general index in their July trend whereas industrial and insurance values outperformed the index, adding 3.9 and 2.8%, respectively. The services sector underperformed with a drop of 4%. Reporting a price to earnings ratio of 19.89x, the DSM is the most expensive market in the GCC, though, and it serves to remember that the bourse is up over 50% when compared with a year ago. In the real estate sector, Barwa Real Estate, whose share price fluctuated in the upper 80s (Riyals) in July, tops most DSM traded stocks in terms of the P/E ratio, at 43.81x. However, 2008 newcomer Ezdan, also a real estate player, displays an even higher P/E of astounding 67.03x.

Tunis SE  (1 month)

Current Year High: 3,059.63  Current Year Low: 2,436.94

The Tunis Stock Exchange had a month that ended better than it started. Dropping some 75 points in the first ten days of July, the Tunindex gained most back and closed the July 24 session at 3020.55 points. Investors on the TSE got some exciting news in July as agro, manufacturing, and real estate conglomerate Poulina Group Holding (PGH) announced plans to list 10% of its capital via a capital increase on the exchange in what PGH touted as the largest initial public offering in the TSE’s history. PGH, which has 71 subsidiaries, moreover said it will be the bourse’s new market cap leader after the flotation; subscription in the IPO was opened in roughly equal proportions to local investors and foreign institutional investors and was scheduled to run from July 24 to August 6. In other market news, the Tunisian government was reported to be planning to sell a 35% stake in listed insurance company STAR to the French insurer Groupama.

Casablanca SE All Shares  (1 month)

Current Year High: 14,925.99            Current Year Low: 11,394.32

The Casablanca Stock Exchange index added 272 points between July 1 and its close at 14,463.40 points on July 25. Up 13.93% since the start of 2008, the Moroccan bourse remains at the top of the price ladder for all stock exchanges in the Middle East and North Africa, with a proud price to earnings ratio of 32.75x. Market cap leader Maroc Telecom traded sideways in July; however, the company announced 10% higher net profits in the first half of 2008 when compared with the same period in 2007. The company attributed the profit increase firstly to revenue growth at its domestic mobile communications division.

Egypt CASE (1 month)

Current Year High: 11,935.67            Current Year Low: 7,517.77

Although it had a couple of positive sessions in mid-month, the Cairo & Alexandria Stock Exchanges could not come to a liftoff in July. The CASE 30 index closed at 9382.51 points on July 24, down 4.5% from the start of July. Market capitalization leader Orascom Construction Industries had a volatile time but showed a net gain of EGP 20 the share on the month to close at EGP 387.55 on July 24. The second largest company on CASE by market cap, Orascom Telecom Holding was less fortunate and saw its shares lose 14.9% in value between July 1 and 24. OTH additionally received a valuation rebuff from international investment bank Morgan Stanley; the bank’s analysts reportedly lowered their target price for OTH by more than 25%, citing the company’s uncertainty over strategy and vulnerability to inflation. OTH, OCI, and Orascom Hotels & Development, the third large firm in the family, each lost between 30 and 40% of their value since the start of 2008. Showing few positive examples of companies that currently enjoy trust of investors, the market is still looking for its new champions.

August 13, 2008 0 comments
0 FacebookTwitterPinterestEmail
Executive EducationSpecial Report

Money Matters by BLOMINVEST Bank

by Executive Staff August 13, 2008
written by Executive Staff

Regional stock market indices

Regional currency rates

Middle East contracts at $5.4 billion

According to the Middle East Economic Digest, contracts awarded in the Middle East in the first half of this year reached $5.4 billion. The most prominent projects are Saudi Arabia’s installation of a 1,200mw thermal power plant that is commissioned to Alstom (France) at $3 billion. On the other hand, United Arab Emirates’ (UAE) Shah gas field exploration by Abu Dhabi National Oil Company (Adnoc) and Conoco Phillips is worth $1 billion. Other prominent projects include Tunisia’s 400mw combined cycle power plant that is being built by Alstom for $529 million. Country wise, UAE’s total awarded projects stand at $1.6 billion, Saudi Arabia’s at $3.15 billion and Kuwait’s at $158.5 million.

GE and Mubadala in $8 billion partnership

Mubadala Development Company, an investment company owned by the Abu Dhabi government, announced an $8 billion partnership agreement with GE to establish a commercial financial business. The aim of the agreement is to invest in infrastructure assets, real estate, clean energy research and development and aviation. Both parties will contribute $4 billion each in equity to the joint venture over the next three years and expect to build assets up to $40 billion over the next 12-18 months. It is worth noting that according to Khaldoon Al Mubarak, CEO of Mubadala, the company’s long term plan is to become one of the top ten shareholders in GE through buying shares on the open market. GE is worth about $3.3 billion.  

Fitch upgrades Saudi Arabia’s credit rating to AA-

The Middle East and Africa monitor expects Saudi Arabia’s real GDP growth to push higher in 2008 and 2009, to be around 4.0% and 4.3% respectively. This is mainly due to the non-oil sector expansion, increasing oil production and a jump in global oil prices. Moreover, the monitor expects the OPEC basket to average $121.5/bbl in 2008, up 57% from the previous year. This will spill over other areas of the economy, notably the external sector that will lead to a trade surplus of around $328 billion, more than double the $151 billion recorded in 2007. In line with Saudi Arabia’s growing economic strength, on the back of record oil prices and increasing energy production, Fitch Ratings have upgraded the kingdom’s credit rating from A+ to AA-. The agency also changed the kingdom’s long-term ratings outlook from positive to stable. The new ratings put Saudi Arabia on a par with Kuwait, and one notch below Abu Dhabi, and although Saudi Arabia is unlikely to need any additional financing in the short-to-medium term, the upgrade is likely to increase foreign direct investments.

August 13, 2008 0 comments
0 FacebookTwitterPinterestEmail
Executive EducationSpecial Report

Morocco’s educational capital

by Executive Staff August 13, 2008
written by Executive Staff

As the global economy continues on its path of integration, more Moroccan students and professionals are turning to business schools to gain an edge in competitive job markets. Enrollment in business and management programs increased by 3.1% in 2003/04 from the previous school year, according to the Ministry of Education. A growing group of public and private schools are offering advanced degrees in business and management education to meet rising demand. 

Schools of today and tomorrow

Business and management schools are adapting their programs to changes in the global business environment. In particular, demand is growing for English-language MBAs and executive education. Al Akhawayn University, the Hassania School of Public Works (Ecole Hassania des Travaux Publics), and Ecole des Mines de Rabat all offer executive MBAs taught in English. To encourage innovation in business development, institutions also foster synergies with engineering schools and combine research into local business development with global dimensions of business education.

Houdaifa Ameziane, director of the National School of Business and Management of Tangier (ENCG), calls the evolution of Moroccan business schools “very satisfying.”

“We came on the scene somewhat timidly several years ago, to fulfill the needs of local businesses by according training programs in management aptitude. After that, we organized on-the-site training in the enterprise, with modules specially formulated for groups installed in the region. Since then, we have passed to the stage of master’s level diplomas available for students who seek managerial know-how and for professionals interested in continuing their education.” The ENCG network has invested heavily in relations with the region’s socio-economic powerhouses. Representatives from the shipping and transport companies that are rapidly growing in the Tangier region, and from the nation-wide telecommunications, manufacturing and banking sectors regularly recruit from the pool of ENCG’s students.

Going back to school

For those who have already joined the workforce, several institutions offer continuing education programs in business and business-related fields. Al Akhawayn University, a leader among Moroccan higher education institutions, offers a master of science in corporate finance, international master in e-business management, and an executive MBA. The executive MBA is completed through short weekend classes and evening seminars in Casablanca and residential sessions at the idyllic Ifrane campus. A part-time MBA is also available for public and business administration managers who want to raise their earning potential without sacrificing their current employment.

Some higher education institutions are tailoring their programs for the globalizing world by developing partnerships with international schools in Europe, Canada, and America and providing joint degrees. Joint degree programs are mainly master’s and executive master’s in various fields, such as business administration, public management, logistics, finance, and operation management. There are also franchising networks of private institutions from within Morocco, and others created by consortia of businesses, who groom students as trainees or future employees.

Casablanca business school ESCA recently teamed up with France’s Grenoble School of Management to offer Grenoble’s ‘specialized masters in business intelligence’ to students and executives living in Morocco. The Grenoble school said in a statement that the program was formulated to respond to particular problem areas in Moroccan businesses, “as business intelligence is increasingly playing a significant role in terms of business performance, but lacks specialists notably in the retail, marketing, consulting, and project management fields.”

Moroccan executives regularly lament the lack of qualified personnel in the region, and often recruit foreigners, particularly French nationals, for high-level positions. In turn, foreigners come equipped with high-level training, but often have trouble understanding local business practices and culture. With Morocco becoming a hub of regional investment and trade, local business schools are increasingly important in creating the skilled professionals needed to manage new wealth and sustain high levels of growth.

August 13, 2008 0 comments
0 FacebookTwitterPinterestEmail
Executive EducationSpecial Report

Jordan’s business class

by Executive Staff August 13, 2008
written by Executive Staff

Executive education in Jordan has yet to become a staple of academic institutions, but the country’s accelerating integration into the global economy means that ambitious Jordanians increasingly have to be on the lookout for the competitive advantages offered by focused higher degrees. Faced with more competition, one way for the young Jordanian executive to keep up is through a mid-career boost from a small but growing number of master of business administration (MBA) and similar courses. Particularly innovative is the new MBA degree offered by the German-Jordan University (GJU) at its Talal Abu-Ghazaleh College of Business (TAG CB) in Amman. Established in 2006 as one of the faculties of the new university, TAG CB represents an education partnership rare in the Arab world between academe and the region’s private sector, bringing the expertise of the Abu-Ghazaleh business consulting and services group to the GJU. The latter, a public university jointly launched in 2004 by the German and Jordanian governments, is headquartered in Amman and plans to open branches in various other Arab cities.

Designed as a passport to a higher management career for ambitious young executives, the GJU MBA program enforces the concept of transferring knowledge from classes into real-world workplaces. Normally, students in this program will have qualified some three to five years previously with a Bachelor’s degree and then gone on to perform well and show leadership at work. In a sign of the times, GJU points out that its MBA graduates could go on to serve as effective managers not only in the private sector, but also in business aspects of government or other public agencies. Though not at the level of Dubai and other high-flying economies where state offices often function as smoothly as private business, Jordan’s public sector is nevertheless moving in that direction — helped by a growing number of bright young graduates of executive education programs. In particular, GJU allows its MBA students to specialize in such areas as finance, statistics, marketing, or international business, not to mention the Abu-Ghazaleh specialties of Intellectual Property and Accounting.

More specialized, but still aimed at the executive, is the MBA offered by Jordan’s Queen Nour Civil Aviation Technical College. Established in 1973 and recently privatized, the college meets Jordanian and regional civil aviation needs through a two year program leading to a community college diploma, as well as by special training. However, in the process of upgrading and revamping its offering, eight years ago the college started an MBA in Aviation Management. Designed for high-flyers, as it were, Jordanians and students from elsewhere in the region have benefited from this course, helping their respective airlines compete an increasingly sophisticated and vital sector.

Finally, for Jordan’s finest young executives, the Queen Rania Global Leader Scholarship is offered annually by the famed Thunderbird School of Global Management in Arizona. The scholarship goes to Jordanian business leaders interested in pursuing an MBA in global management. Candidates for the award must have a minimum of two years’ work experience and they have to be motivated by factors other than personal advancement. In fact, applicants for this MBA scholarship must submit an essay on how they intend to use their education to make a positive contribution to their nation, region and/or the world community. Jordan’s Queen Rania promotes the award saying that empowering women is, “perhaps, the single greatest legacy we can bestow upon our children.” Although in the age of gender equality, men are also eligible for this prestigious MBA scholarship. Look for more of these initiatives in Jordan, as well as an expansion of home-grown MBAs, over the next few years.

August 13, 2008 0 comments
0 FacebookTwitterPinterestEmail
Executive EducationSpecial Report

Learning business in the Middle East

by Executive Staff August 13, 2008
written by Executive Staff

“Every degree becomes obsolete five years down the line, so you have to renew your knowledge,” said Assaad Raphael, chairman and general manager of Porsche Center Lebanon. This is why Raphael returned to his Alma Mater, the American University of Beirut (AUB), for the Executive MBA (EMBA) program last year. The 20-month program meets every three weeks for a three-day weekend: Thursday, Friday and Saturday mornings.

“I know that this program added value to my role at my company,” Raphael said. He was quick to point out that a major benefit was the ability to learn from the experiences of his classmates, who came from all over the region. “Fully 50 percent of my classmates were commuting in from outside of Lebanon,” he added. According to AUB’s Olayan School of Business (OSB), which hosts the program in addition to their MBA, typically half of EMBA students are residents of Lebanon. Of the others 14% are Saudi, 12% Kuwaiti, 9% Qatari, 5% Emirati and 5% are even residents of Europe.

Student ages vary as well, asserted the EMBA Program Director Riad Dimechkie. “We aim at executives and those aspiring to be executives,” he said. Thus participant age varies from 30 to 60 years, although the average age is 40. The students’ combined and varied experience plays directly into the program. Class sizes of 15-20 students, roughly half that of many EMBA programs in the United States, means that classmates have an intimate setting in which to share their experiences and learn from each other.

From an academic angle, Dimechkie said “the overall focus is on general management” so that all elements of the contemporary business world are covered. This facet allows an executive to speak with an accountant, human resources manager or marketing executive and be able to follow the conversation without a second thought.

Furthermore, the AUB program prides itself on having strong roots in the region. This is also reflected in the academics of the EMBA, which aims to be Middle East relevant in three ways. First, there is a strong focus on the service industry, which is very important to both the Levant and the Gulf. Second, there is an emphasis on small and mid-sized enterprises. This is a nod to the numerous family-run businesses of the Middle East. Finally, there is a specific focus on Arab businesses. The OSB facilitates this by conducting case studies on the Arab world and by bringing in Arab leaders to lecture.

The cost of class

Full tuition for the program is around $35,500, usually paid in one of two ways: either the students cover the cost themselves or their company pays. A common practice when the company pays is that the cost gets amortized over a three-year period. For example, if the freshly graduated employee leaves the company after one year, they must reimburse the company for two-thirds the cost of the program. If they leave after two years they are responsible for one-third the cost and if they leave after three years they owe nothing. This approach helps to prevent a valuable human resource investment from walking out the door.

While AUB’s business school is cheaper than many Western options, there are several other options in Lebanon for the value conscious. One of these is the Ecole Supérieure des Affaires (ESA) in a quiet neighborhood of West Beirut. “Both our MBA and EMBA require 16 months of course work and four months for the thesis,” said ESA Academic Coordinator Jan Schaaper. The MBA is designed for young professionals with less than five years of experience. It is a much more technical degree, while the EMBA focuses on soft skills like employee relations and negotiation. Schaaper suggested the EMBA has value added in that “professionals are coming together, not only for course work, but to share their experiences as well.”

ESA’s graduate business students usually hail from Lebanon, though some come from Syria and Jordan as well. The MBA programs are conducted in cooperation with ESCP EAP European School of Management and are taught in French. But according to Schaaper, the main difference between the American MBA system and French programs like ESA is specialization. “The French system has specialized master’s degrees. We have not only an EMBA, but also four specialized master’s for executives including finance, marketing, hospital management and we will be offering Islamic finance next year,” he said. The MBA program costs some $13,000 and the EMBA is roughly a thousand dollars more.

For young executives involved in the North African market, the American University of Cairo’s MBA might be of interest. “It is the only AACSB accredited program in the country and many prominent Egyptian business people have graduated from the program,” said Mohga Badran, head of the management unit at AUC’s Department of Management. MBA students can choose to concentrate in accounting, finance, international business, leadership and human resources management, information systems management, marketing or operations management.

According to Badran, 90% of these MBA students come from Egypt and the remainder from other Arab countries, Europe and the US. Half of the students are engineers, while the others are physicians, family business owners or from multi-nationals with offices in Egypt. The program is entirely in-house as it has no affiliation with any foreign universities. Regarding the cost of tuition, students who complete the minimum 33 semester credit hours pay $52,000. Students coming from the sciences, however, may qualify for the full-ride Gameel Fellowship.

Learning in the GCC

There are also several options for MBA programs in the Gulf. The United Arab Emirates boasts several business schools such as the American University of Sharjah (AUS). “Diversity is one of the attractions of AUS. Our MBA students come from the UAE (28%), Iran (21%), Syria, Jordan, Palestine and throughout the GCC,” said Rob Bateman, acting dean of the Business Management School.

The program’s core courses often require practical projects involving actual business situations, preparation of business plans or resolutions of leadership problems, added Bateman. Most students enroll part-time as they have full-time employment at corporations based in the Emirates. It is possible to complete the degree in one year, although three to four years is more common. Starting tuition for the program is $39,000.

Also in the Gulf is Qatar University (QU) in Doha. “The Qatar MBA curriculum presents students with a cross-functional approach to business education that leads to a better understanding of real world challenges in the current business environment,” according to Mohammad Najdawi, dean of the Business and Economics College. The average age of MBA students is 27 years and the average undergraduate GPA is 3.3. As for foreign affiliation, QU has relationships with Nanyang Technological University in Singapore and it will soon have a relationship with Bocconi University in Milan, Italy. The degree costs a minimum of $9,900 for non-Qataris with a business background. Non-nationals who have not previously studied business are required to take 12 foundational credits, raising the price to $13,000. Qatari nationals receive a 30% discount.

Finally, for the up and coming professional looking for executive education in Damascus, the Higher Institute for Business Administration (HIBA) offers a solution. HIBA students are predominantly Syrian, but also come from Jordan, Egypt and France. HIBA offers both an MBA and an EMBA.

“There are three main foci for the MBA program,” according to HIBA’s dean Fouad Dib, “communication in business administration, economics, and quantitative methods in business administration.” Students can also specialize in marketing, human resources and finance. All courses are given in English and the MBA program takes 18 months on average. HIBA has cooperation agreements with Universitat Autonoma in Barcelona and with the Bordeaux Business School in France. Tuition for the EMBA costs $11,700 for Syrians and $12,000 for internationals.

Thus there is no shortage of executive education in the region. From North Africa to the Levant and the Gulf, opportunities for professional growth abound, with the MBA is still the most common form of graduate business degree. As long as the regional need for executive talent continues to grow, the number of executive education programs available will continue to grow with it.

August 13, 2008 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 515
  • 516
  • 517
  • 518
  • 519
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE