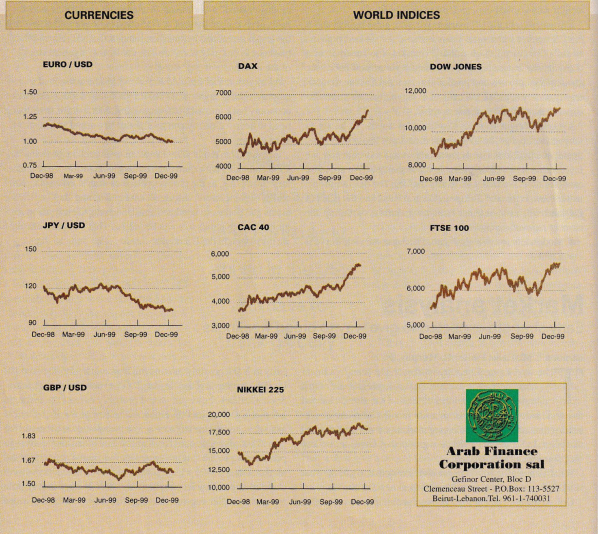
The world’s major equity markets have been in a linear
uptrend since early in 1993. The most recent phase of that
uptrend began in October 1999, and has already carried
the world index above a previous multi-month consolidation pattern.
At the same time, the emerging markets are still in an uptrend
that began in September 1998. As a group, they have almost doubled
since then in dollar terms.
What’s ahead for 2000? In general, strength early in the year
is likely to give way to broad-based weakness, in our view.
United States The US market may face an interim correction early in 2000, possibly moving the Dow and S&P 500 down 10
to 15% or more and the Nasdaq 20% or more from their peaks.
Such a setback, however, would probably correct the market’s
internal excesses and divergences, and improve its technical
indicators, setting the stage for a new, broader advance later in the
year. That advance could be characterized by an above-average
performance by the long-neglected mid-to-small-cap sector of the
market. During 1999, a large portion of mutual fund inflows were
directed into large-cap growth funds while comparatively little
went into smaller-cap-oriented aggressive growth funds; from a
contrarian point of view, that suggests that a performance shift
favoring the latter area could take place in 2000. That possibility
would become more likely if the small-cap-oriented Russell
2000 Index were to hold up better than the Dow and S&P 500 during
a correction early in the year.
Europe The UK market is likely to start the year strongly, in our
view, but there is a growing risk of a cyclical downswing in the
second quarter, when waning momentum could coincide with a
renewed upswing in commodity prices and bond yields. The FTSE
could register losses of 20% or more from its highs. Early
strength is also likely in continental Europe, and most country
indexes could reach new high ground. However, a correction could
be in full swing before mid-year, taking the averages 20 to 25%
below their peaks and undercutting their summer-1999 lows.
Asia The rally in Japan’s equity market has the potential to
reach the 21,000 area on the Nikkei in our judgment. However, we doubt that the bear-market pressures have run their
course. The next important decline could be a substantial
retracement of the post-1998 rally – one that could take the
Nikkei back to 15,700 to 15,800. Elsewhere in the region, the
post-1998 rally is likely to peak early in 2000. The region’s rally
is roughly 14 months old. If we use the Hong Kong market as
a bellwether for Asia, long-term rallies have tended to have a
lifespan of 12 to 24 months. That points to a possible peak late
in the first quarter.
Latin America The current rally in the region is still in its early
stages, and it has a seasonal plus going for it: January generally
tends to be a good month. We think that the rally is likely to continue
into the early part of 2000 and that all of the Latin American
markets will participate in it. Even so, the global pressures that
we see on the horizon suggest that the second half of the year will
be difficult for the region.