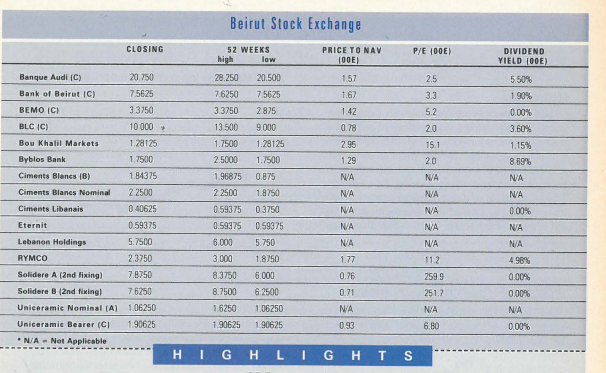
SOLIDERE
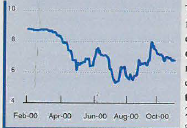
The political stagnation resulting
from the long break between the
end of the parliamentary elections
on September 3, and the appointment
of a new government by the
end of October, is taking its toll on
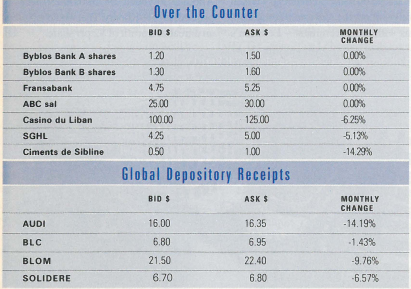
the market. Solidere’s GDR fell
2.41 % to $7 .075 (22/9), then fell
another 1.06% to $7 with the
materialization of S&P’s downgrades. International investors continued
trading cautiously as uncertainty surrounding the identity of the new
prime minister was still in question, though sentiment is leaning toward
Rafic Hariri. Solidere’s GDR lost 1.07% to finish the first week of
October at $6.925 (6/10). The escalating tensions in the Middle East
alarmed international investors who registered their concern by exiting
Lebanese GDRs. Solidere lost 2.17% to $6.775 (13/10).
AUDI
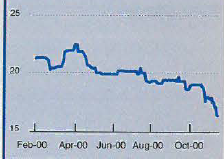
Two downgrades from international 25
agencies negatively affected Audi ‘s
GDR, first S&P credit downgrade of ~
Lebanon’s sovereign rating, as well as 20
Bank Audi and two other banks, citing
concerns on the deteriorating public
finances. Audi’s GDR fell 1.06% to
18.65 (22/9). Rating agency Fitch
IBCA then downgraded Bank Audi’s individual
rating, voicing concerns that asset quality will be affected by the
ongoing economic recession. Audi tumbled 4.83% to $17.75 (29/9). It then
fell another 2.37% to $17.33 (6/10) as international investors saw the political
stagnation, resulting from the transition of power, as negative and persistent
to Audi’s outlook. The increasing political instability in the occupied territories
crossed the border into Lebanon, driving Lebanese GDRs south, with
Audi’s GDR losing the most and dropping from 6.64% to $16.18 (13/10).
BLOM
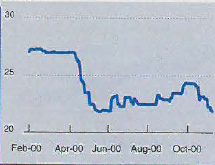
S&P lowered its rating for BLOM
in line with the sovereign downgrade
as concerns mounted about
asset quality during the economic
recession. BLOM lost 0.72% to
$24. 125 (22/9), then plummeted
4.04% lo $23.15 after a volatile
week that saw its, price fall to
$22.85, but rebounded by the end
of the week on rumored foreign
buying. The economic and political freeze did not impress investors, but
BLOM attracted some buying leaving its price at $23 (6/10), a 0.65%
weekly decrease. The rising troubles across the border were immediately
seen by wary investors as the first signs of political instability in the
region. They sent BLOM’s GDR down 4.78% to $21.9 (13/10).
BLC
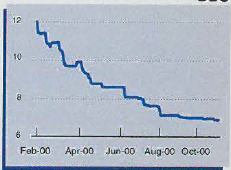
Going along with the market
sentiment, BLC’s GDR edged back
slightly, 0.36%, to $6.95 (22/9), as
the vacuum in the political arena
started 10 weigh on the economy.
BLC was not specifically affected
By the downgrade by S&P. The rating agency cited the overall
economic recession as the main reason for
the downgrade, while investors
believed that the old news was already reflected in the price. BLC held
its ground two weeks in a row (29/9) lo remain at $6.95 (6/10).
However, investors did not ignore the escalating tensions in the Middle
East that resulted in the halt of the peace process. BLC lost 1.08% to
$6.875 ( 13/10).
MOROCCO
The Casablanca Stock Exchange ended lower driven
by losses in leading shares as investors failed to
react to the announcements of first-half corporate results
that were somewhat in line with expectations. A
wait-and-see mood dominated the market as investors
kept to the sidelines awaiting the announcement
of promised reforms, including new incentives
for companies to list their shares on the stock market
and a series of tax breaks. Year-to-date losses now
stand at almost 17%.
EGYPT
The rising political tension in the region and the continued
liquidity crisis combined to deal a heavy blow to
Egyptian equities, which shed almost 20% since early
October and are down more than 50% since the beginning
of the year. This was heightened by news that foreign reserves
retreated to $14.64 billion in July 2000, down from
$15.13 billion a month earlier, while the Egyptian pound
has been traded at almost EGP4 to the dollar. In an effort
to contain the foreign currency crisis, the Central Bank issued
directives limiting daily cash withdrawals of foreign
currency to $20,000.
JORDAN
A cautious mood continued to dominate the Amman
Stock Exchange following weeks of Israeli atrocities
in the Palestinian Territories, bringing year-to-date
losses to 21 %. The banking sector led the decline as a
result of a drop in Arab Bank, which is one of the market’s
largest blue chips in terms of capitalization. Nevertheless,
statistics show that around 150 foreign mutual
funds have been operating in the Amman Bourse
over the past three years. Net non-Jordanian investment
at the bourse between August 1996 and the end
of August this year amounted to $281 million, or
around 6% of total market capitalization.
Regional Markets
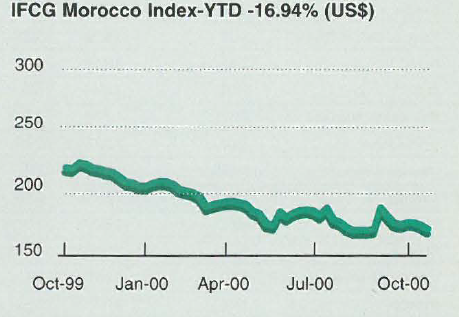
MOROCCO
The Casablanca Stock Exchange ended lower driven
by losses in leading shares as investors failed to
react to the announcements of first-half corporate results
that were somewhat in line with expectations. A
wait-and-see mood dominated the market as investors
kept to the sidelines awaiting the announcement
of promised reforms, including new incentives
for companies to list their shares on the stock market
and a series of tax breaks. Year-to-date losses now
stand at almost 17%.
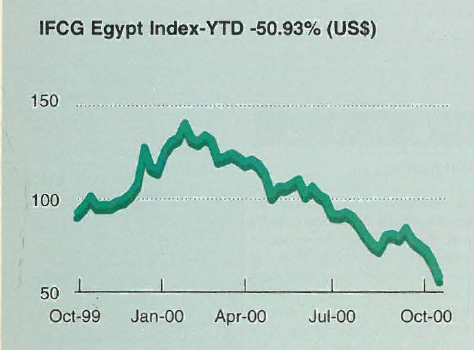
EGYPT
The rising political tension in the region and the continued
liquidity crisis combined to deal a heavy blow to
Egyptian equities, which shed almost 20% since early
October and are down more than 50% since the beginning
of the year. This was heightened by news that foreign reserves
retreated to $14.64 billion in July 2000, down from
$15.13 billion a month earlier, while the Egyptian pound
has been traded at almost EGP4 to the dollar. In an effort
to contain the foreign currency crisis, the Central Bank issued
directives limiting daily cash withdrawals of foreign
currency to $20,000.
JORDAN
A cautious mood continued to dominate the Amman
Stock Exchange following weeks of Israeli atrocities
in the Palestinian Territories, bringing year-to-date
losses to 21 %. The banking sector led the decline as a
result of a drop in Arab Bank, which is one of the market’s
largest blue chips in terms of capitalization. Nevertheless,
statistics show that around 150 foreign mutual
funds have been operating in the Amman Bourse
over the past three years. Net non-Jordanian investment
at the bourse between August 1996 and the end
of August this year amounted to $281 million, or
around 6% of total market capitalization.

The performance of the largest 100 Arab banks in 1999
The positive effects on Arab
economies of higher oil prices
from mid-1999 onward and the
ongoing structural adjustment programs
in the non-oil countries saw
Arab banks recording healthy returns in
1999, with few exceptions. The combined
net income of the 100 largest
Arab banks rose by 10.2% to $8.3 billion,
while their combined assets
increased by 4.2% on their 1998 level to
$526.3 billion. However, these assets
remain smaller than the assets of any of
the largest ten banks in the world. For
example, the assets of HSBC Group
alone were $569 billion last year.
Average return on equity for Arab
banks stood at 13.9%, with return on
assets and capital-to-asset ratios at
1.58% and J 1.3% respectively. The top
Arab bank in the region in terms of
equity, the Arab Banking Corporation in
Bahrain, ranked as number 161 among
the world’s largest l000 banks in 1999,
followed by Saudi American Bank,
which ranked as number 166.
According to Euromoney’s Top 100
Arab Banks survey, the seven largest
Tunisian banks recorded the highest
increase in combined net income in
1999, up 84%, followed by the top
Bahraini and Egyptian banks with earning
growth of30.5% and 25.2% respectively.
ln the Gulf, the banking sectors of Kuwait and Qatar fared
well, with the top banks in
each country posting profit
increases of I 0.8% and
5.7% respectively. In
Saudi Arabia, the combined
pretax profits of the
nine banks (excluding
National Commercial
Bank, which had not yet
released 1999 results) rose
by a modest 1.5%.
A comparison of return on equity ratios, a key measure of profitability,
places the five top Qatari banks
in the lead with 17.7% average return
on capital in I 999, followed closely by the
largest 14 Egyptian banks, which saw
their average return on capital rise from
16.2% in 1998 to 17.5% in 1999. Return
on equity for the seven Lebanese banks
fell to I 6.9% in I 999, from 18.1 % the
year before.
The banking sector ‘s concentration
ratio measured by the market share of the
top five banks in the region is relatively
high. In Saudi Arabia, two banks, the
Saudi American Bank and the National
Commercial Bank, hold almost 50% of
the sector’s assets. The National Bank of
Kuwait and the National Bank of
Bahrain each holds 30% of their country’s
respective banking assets. Egypt’s
four state banks have 50% of total
assets and control most of the retail network,
while in Jordan, the top five
banks control 80% of the assets.
Management of Arab banks has so far
been emphasizing mainly asset size and
market share, believing that the large balance
sheet on the long haul would guarantee
competitive advantage. Instead,
management objective in the new millennium
should be to maximize shareholders’
value. This necessitates shedding
off businesses where the returns do
not cover cost of capital and allocating
more resources to those activities that
add value over time. Enhanced profitability
could also be achieved by
reducing operating expenses through
the effective use of modem technology
such as the Internet, and seeking consolidation
with banks in the domestic
market or abroad.
Arab banks will have to understand
their products and their customers’
needs much better and invest more in
technology if they are to survive the
onslaught of new competition. And if
they were too slow to adapt, the consequences
could be detrimental. Look at
what had happened in just four years to
stock trading on the World Wide Web,
and note that the stock market with the
highest proportion of Internet trading is
not in New York but in Seoul.
Consolidation would reduce operation
cost, minimize duplication, boost efficiency,
spread the huge technology costs
over a bigger base and cross market products
on a larger scale. However, consolidation
has to be planned carefully and
motivated strategically to be effective.
Despite the few consolidation deals carried
out in the region in the last two years,
mergers and acquisition activity remains
sporadic. It seems Arab banks are unlikely
to pursue serious consolidation activity
unless they are forced to do so by their
respective monetary authorities.

Global research Highlights
Investors seem to fear a hard landing, but the evidence for
one is close to nonexistent. Although the tech-dominated NASDAQ
has had some rough going, orders for computers were up
by 34% from August 1999 to August 2000, and telecom-equipment
orders advanced by 19%. That isn’t the image of a tech
sector that’s falling apart. Meanwhile, consumer spending appears
to have grown at a 5% rate in the third quarter. The economy
has lost some momentum, but remains healthy, in our
view. We still expect GDP to increase by nearly 4% for 2001.
• Our benign view of the world is based on the belief that the
New Economy is putting down ever-deeper and broader roots.
Specially, we believe that productivity gains will remain
strong, leading to rapid non-inflationary growth and decent
profit margins. We will be wrong if productivity gains suddenly
start to flag. Third-quarter productivity probably grew at
about a 3.5% rate, faster than GDP.
• Technology spending is at the center of the productivity revolution.
Our work shows that an acceleration in tech spending
now tends to lead to an acceleration in productivity within years.
Because tech spending is up by 27% on a year-to-year basis –
fastest pace of the expansion – we believe that structural
productivity gains are pretty much a certainty for 2001 and even
2002. What’s our 200 I forecast for tech spending? A somewhat-
slower but brisk increase of 22% in real terms.
• One thing that’s worrying tech-sector observers is the
euro. Tech has the highest European exposure of any S&P sec-
tor. Currency translations reduced S&P 500 EPS growth by
about three percentage points in the third quarter; logic
suggests that the figure was larger for tech companies. Based on
the assumption that the euro will stabilize, the adverse
currency effect will probably be only half as strong in the fourth
quarter; it should be neutral by the first quarter of 2001.
• The job market shows neither excessive weakness nor
strength. Stripping away special factors, September payrolls rose
by 204,000 jobs, in line with the performance so far this year. The
unemployment rate fell to 3.9%, but only because the labor force
temporarily shrank. Wage pressures are contained: hourly wages
were up by only 0.2% for September and by 3.6% on a year-to-
year basis, in line with their rate for the past five years.