• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Lebanon

Private banking, investment banking and private equity.

by Executive Staff October 1, 2007
written by Executive Staff

With high oil prices pumping fairy-tale-like sums of money into the coffers of the oil producers, the private equity wave is sweeping the region, with more and more capital looking for interesting projects to finance. GDP growth in non-oil producing states is increasingly buoyed by oil money from abroad, most visible in the various “mega-projects” springing up not just in Dubai, Doha, or Manama anymore but now also in Damascus, Amman, and Cairo.

In the Gulf, PE funds are now replacing traditional commercial banks as big investment houses and the region is flush with money. The question, however, is: How does this play out in Lebanon?

The financial experts interviewed by Executive say that the domestic political situation during the past decade forced Lebanon to move on a separate path, different from the rest of the region.

According to Khaled Zeidan, at Banque de la Méditerranée, “Investment banking, as a stand-alone business, has ceased to exist. If we look at all the investment banks that sprang along Lebanon in the 1990s, Lebanon Invest, Middle East Capital Group, investment house, etc. … those houses, which were quite well-capitalized, were unable to survive because the depth of the market was not there.”

As he explained, most of the specialized investment firms were acquired by other banks and ceased to exist as independent entities. An example is Lebanon Invest, which is now part of Banque Audi Saradar, a big and diversified bank. Zeidan sees the reason for the investment banks’ failure is that for serious investment banking in Lebanon, there are too few deals available. Everyone banked on Lebanon becoming a business hub for the region but that did not materialize. And since investment banking is a high overhead business — people that work in this sector are usually extremely well paid — it cannot be run on a cheap budget. But, in his words, “if there is not enough of a deal flow for market conditions, it just doesn’t work.”

Failures of investment companies

Jean Riachi, chairman of Financial Funds Advisors, put it even more drastic: “Lebanon Invest and Middle East Capital Group (MECG) were not bought as star acquisitions, but instead were dismantled when they went into liquidation.” Like Zeidan, he sees one of the reasons for the failure of the investment companies that had started with some IPOs in the ‘90s, when there were high expectations about Lebanon, in the fact that the economic boom did not last. However, he adds that, “For various reasons, in some cases mismanagement, the basic foundations were not laid within these companies, creating problems. Also, the market did not mature — the local financial market, needed to create a secondary market for the primary issues, did not exist and was not established. It should have been created parallel to the investment business, but it did not happen, and thus the necessary conditions for successful investment banking were not brought in place.”

The fall of investment banking has, in Khaled Zeidan’s view, led to a strengthening of classic private banking.

“The bulk of Lebanese banks, even at the branch level, do private banking, the sort of high-end retail,” he said. In Lebanon, people do expect their bankers to offer them many things outside the basic deposit business. One can see that at multiple levels, even in commercial banks, where the bankers cater to wealthy individuals. When done in a more organized fashion, there are a few banks that have established private banking departments or are private banks. What they are doing is either managing assets out of Lebanon in Cyprus or Switzerland, or sometimes also in Lebanon. The relationship managers are located in Lebanon and travel throughout the region, gathering assets, developing new projects or following up with their existing client base. They usually provide everything — they do portfolio management, real estate business, can push a particular product. Overall, they are relationship managers that do the full-fledged liaison with a particular client. Contrary to investment banking, where a windfall could be made with each deal, private banking is a long-term, low-margin business. But as assets grow, a lot of money is made. The majority of banks, like UBS & Credit Swiss, generate 40% of their income from the asset management of their private banks.

Difficulties on the Lebanese front

In his view, “This model has been more of a success, it is here to stay, and most probably will continue to grow. Had there been more stability in the country, we would’ve seen even bigger success, since we have the human resources. It takes time, effort and a lot of resources. But it pays off in the end.”

Private equity fund penetration of the Lebanese market seems to be facing the same difficulties as the investment banks of the 1990s: not enough interesting deals and a reluctance of domestic, often family-owned companies to disclose and embrace international standards of business transparency.

The first product of this type launched in Lebanon, Lebanon Invest’s “Lebanon Holding” in 1997, was launched by an investment firm that had had deal flow in the past, had a sizeable team of 40-50 people, and was a product that had about $50 million in assets. Yet, it still failed. Zeidan sees the reason in the local business structure, explaining that, “When you are in PE you need to penetrate the family structures in the country, convincing them that if you are the PE fund entering into their capital, it will not change the course of the way they do business. But people have a problem with reporting in Lebanon, with transparency and all those things that affect the business environment. Hence, PE will have a hard time in Lebanon, like in the rest of the region. The market isn’t mature yet.”

The only place where PE can attract large sums of money is the real estate market. As Executive reported in previous articles, over the last 12 months large sums of money have been poured into Lebanon’s real estate market, as reflected in prices: up by 30-40% year-on-year. Yet, in the wider region real estate prices have been rising even more, so that now Lebanon is perceived to be a cheap market, attracting buyers and investors.

But in other sectors, industry or high-tech for example, Zeidan does not see any deal flow because there are not enough mature companies. There are a number of venture capital transactions but these deals do not attract PE people because they like to go into companies that are already established.

Think regional

There are some activities, in which Banque de la Méditerranée participated in a PE fund geared toward helping small and medium-size enterprises that do not have the resources.

Jean Riachi sees the impact of PE on Lebanon more in within the development of an integrated regional market: “When it comes to PE, one has to think regional. Even if there are interesting investment deals in Lebanon, they can be bought by regional PE firms. There is something happening with the integration of markets in the region. Lebanon is too small of a market. If you think only in terms of Lebanon, you think too small and you cannot succeed.”

Khaled Zeidan sees the developments in the region posing a threat to the Lebanese market, as major banks are looking for opportunities outside Lebanon because they do not see any realistic growth in the country today.

In the end, Zeidan calls to resist quick jumps from old, established financial tools onto the new horse in the stable. “In terms of private equity, one should wait with the analysis until one has a real PE market. Right now there are small, hybrid funds between private and public money. I don’t see any real PE flowing into Lebanon, unless it’s a specific deal, like buying land and developing a project. But private banking is here to stay.”

October 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
By Invitation

Private Equity Makes Inroads into the MENA Region

by Fadi Majdalani & Ulrich Koegler October 1, 2007
written by Fadi Majdalani & Ulrich Koegler

With the rapidly growing economies of the Middle East and North Africa (MENA) requiring greater levels of investment, an increasing number of private equity firms are appearing in the region.

Consider just how quickly the region’s private equity industry has evolved. Five years ago, only a handful of private equity firms targeted the MENA region. Today, over 75 firms, with approximately $10 billion in funds announced or raised in 2006 alone, are active throughout the region.

In mature markets, such as North America and Europe , private equity firms have proven to be effective active owners. Companies that have been acquired by private equity firms have achieved, on average, better risk-adjusted returns than publicly-owned companies in their respective industries. Accordingly, one would expect the development of the MENA private equity industry to have a positive impact.

The role private equity firms have in elevating business performance is particularly important as the region’s economies liberalize, leading to an increase in foreign and intra-regional competition. In order to compete with foreign and other regional companies, MENA-based companies will have to enhance their performance. This is particularly true for companies that were once monopolies and now find themselves in an open market, and companies that are government-owned and subsidized, and now face privatization. For such companies, private equity can serve as a effective catalyst for transformation.

Despite the rapid growth of the MENA private equity industry, it faces a number of challenges. While investors may look to mature markets to extrapolate lessons for the region, MENA-based private equity firms face region-specific challenges. As such, it is critical to understand what private equity firms are, how the region can make its own markets more accessible and attractive to private equity firms, and how the economic landscape will shift as these firms seek further inroads into the region.

Private Equity Firms Seek Value Creation

The private equity industry encompasses a wide range of firms that fundamentally seek to create value, but often in different ways. At the highest level, the industry can be segmented into venture capital firms, which invest in seed through growth stage companies, and buyout firms, which invest in growth through late stage companies. The vast majority of firms, at least in mature markets, are thesis-driven, in that they seek to invest in companies that have specific characteristics, such as industry, location, stage of development, and size.

All firms adopt one or more value creation strategies that are at the core of their investment thesis. As an example, leveraged buyout firms, seek to invest in late stage companies that have stable cash flows and can accommodate additional debt. By levering up such companies, buyout firms effectively lower their cost of capital. In addition, through management incentives and greater operational oversight, they increase returns on capital, thereby earning a greater spread between returns and cost – in effect, value creation. As another example, turnaround buyout firms seek to invest in companies that may be unprofitable due to uncompetitive product lines, poor management, or other causes. By developing a solid turnaround plan, often involving product portfolio, organizational, and financial restructuring, turnaround buyout firms save, what might be otherwise, a dying business.

Private equity firms profit from their investments largely by receiving a share (typically 20%) of the return on their fund’s portfolio return. This “carried interest” is typically received only after the fund’s investors receive a preferred return. In other words, if a minimum amount of value is not created, the private equity firm does not profit. In essence, this ensures strong alignment of incentives between investors and private equity firms in generating value for portfolio companies. It is important to note that private equity firms do also profit from their fund’s management fee (typically 2% of the capital – a substantial amount for large funds) and other fees (e.g., advisory fees) that they receive from their fund and portfolio companies, but these are, for the vast majority of firms, small in comparison to the carried interest.

In addition to having their own incentives aligned with the value of their portfolio companies, private equity firms are also effective at aligning management incentives. In a typical investment, a private equity firm will require management to put their own “skin in the game” by buying a sizable portion of the business. This makes management highly sensitive to the value of the company, and far more keen to making key performance-enhancing decisions. If the company performs well, all investors benefit. Furthermore, with the company shielded from the short-term scrutiny of the capital markets, management can make the types of decisions that have long-term benefits, but might ordinarily be punished by the capital markets and their quarter-to-quarter earnings focus.

Impact on Labor Market is Positive

Private equity firms generally have a positive impact on the labor market. By providing growth capital, private equity firms enable businesses to expand, thereby creating new employment opportunities. In addition, private equity firms tend to invest in improving business practices, thereby contributing to human capital development as employees learn new technologies and skill sets.

In some cases, particularly turnarounds, a private equity firm may engage in workforce downsizing to improve an acquired company’s performance. In the long term, this is beneficial to the labor market as it is far better to have a smaller company than no company, if the business were to fail. Companies that downsize to regain profitability in the short term, position themselves to invest in new avenues for growth that may later require them to increase employment.

Also notable are the indirect effects private equity firms have on the labor market. As private equity firms enlist the services of investment banks, law firms, accounting firms, and other service-oriented businesses, more high-skilled employment opportunities are created in adjacent sectors.

Regulation and Capital Markets Are Critical

The development of the MENA private equity industry depends heavily on the regional regulatory and business environment. In comparison to the private equity industry in mature markets, the MENA private equity industry is small, with just over $25 billion currently under management. In comparison, several deals in Europe and North America (e.g., Equity Office Properties: $38.9B, HCA: $32.7B) each topped $25 billion. Apart from having larger target firms, private equity firms in mature markets have three main advantages that many regional private equity firms lack.

First, private equity firms in Europe and North America have access to a wealth of financial instruments (tradable debt securities, preferred stock) which allow a richer palette of financing options for private equity firms to utilize in structuring deals. As an example, through preferred stock rights, a venture capital firm can minimize downside risk while increasing participation in any upside.

Second, private equity firms in mature markets benefit from greater access to more accurate and detailed market information – the lifeline of the industry – due to greater disclosure and accounting standards. As lack of information increases uncertainty, and consequently perceived risk, it lowers the valuation that private equity firms can place on potential investments, often rendering deals not possible.

Third, private equity firms in mature markets benefit from developed capital markets, enabling them greater opportunities to exit. Private equity firms typically exit through a sale of the investment (trade sale) to another company (40-50% of all investments) or through a public offering (20-30% of all investments). Within the region, the latter exit strategy suffers from a lack of developed capital markets, which are often too illiquid and volatile. As the region’s capital markets develop, in part by attracting greater institutional investors, exiting via an IPO will become a more viable approach.

Challenges Abound, but the Market is Ready

The MENA region may be ripe for private equity firms, but challenges remain. First, the region’s appeal is somewhat compromised by the limited availability of deals and increased competition from other investors, including private investors, investment holding companies, family conglomerates, and government investment agencies. For many private equity firms in the region, the current climate is one of “too much capital chasing too few deals.” This is particularly challenging because private equity funds typically have a pre-defined time limit for investing their funds’ capital. This time pressure could force fund managers to make suboptimal investment decisions.

Second, the increase in the number of firms and funds in the region has crowded the market, effectively making access to capital no longer a distinct advantage. Private equity firms need to better differentiate themselves by having a greater focus in their investment thesis, or by offering a value-add beyond capital, such industry/operating expertise, or access to customers and strategic partners.

For private equity firms that can overcome these challenges, the regional markets offer tremendous opportunities. For companies considering being acquired by private equity firms, there’s never been a better time to be on the “sell side.”

October 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Real estate

What‘s in store – Possible correction?

by Executive Staff October 1, 2007
written by Executive Staff

Bubbly can be tasty. Bubbly stock markets are less so as those who have been caught in the implosion phase of market bubbles are known to share. The problem with market bubbles is not really that only very few people can detect them; the problem is that it is very tricky to avoid being hit when they burst.

For the past year, economists have been divided over the future course of the UAE real estate market, arguing when a correction will set in. The debate was quite intense in the immediate aftermath of the GCC stock markets correction, driven by the painful experiences of billions of dollars in market caps that were wiped out in the first half of 2006. Additionally, as analysts pointed out in autumn of last year, stock market corrections often are followed by downturns in real estate prices — and that with considerable lag time.

On the other side were experts who diagnosed the UAE as having continued severe housing shortages that in the short term would not likely be answered by home construction, despite the immense number of project announcements that flooded the emirate at the center of attention, Dubai, throughout 2006. In short, market liberalization, foreign property ownership, sector volatility, outstanding economic growth — both in the UAE and the GCC — has created two camps: One camp believes that Dubai’s property bubble has reached a head and will soon burst, while the other camp believes the sector will continue to experience growth at least until 2010 and the bubble will remain intact.

Diversifying economic programs

As part of its strategic diversification plan to rely less on oil revenues, Dubai has been for the past seven years spearheading an ambitious economic program with real estate, trade and tourism being the main drivers. The government invested directly into these sectors through the creation of the country’s top real estate development and operating companies. Consequently, Dubai’s measures designed to build a state-of-the-art, modern infrastructure, with the aim to attract millions of tourists and international firms has spawned massive construction projects in the emirate, which, in turn, has created a substantial and a buoyant real estate stock market. Real estate and construction accounted for 15% of UAE’s $164 billion GDP.

Not to be left behind, Abu Dhabi has also earmarked the real estate, business and tourism sectors as key drivers of growth and now engaged in a frenzy of construction activities unmatched in the world. The government of Abu Dhabi announced in mid-September its “Abu Dhabi 2030: Urban Structure Framework Plan,” which lays out a vision that would make the UAE’s capital a global city equal to its European peers. The plan estimates the city’s population to grow to over three million people by 2030 and calls for the spending of over $165 billion on real estate sector and infrastructure projects.

Due to the high speed of economic expansion, the real estate sector was marked by a speculative streak in both property deals and trading in the shares of sector companies on the two stock exchanges of the UAE, the Dubai Financial Market (DFM) and the Abu Dhabi Stock Exchange (ADSM). Equity prices have returned to levels that reflect more reasonable valuations but recent turmoil in international markets raised new questions if equities in the property development and real estate sector have fortified themselves by improving their corporate governance and sensitizing their expansion strategies.

The property sector’s volatility on the Dubai Financial Market was demonstrated in August by very strong, sudden fluctuations of leading property stock, Emaar, which swung within 48 hours from a 3.5% drop to a gain of 5.6% on poorly communicated information, fears, and speculative pressures. Emaar’s fluctuation impacted local and regional market indices but only on a very short term. Calm was restored in September and the following weeks demonstrated that UAE investors have considerable trust in the value propositions of listed real estate stocks.

One testimony to this optimism on the real estate sector was the trading start of Deyaar on the DFM on September 5. Strengthened by an IPO with high demand, the company — a real estate subsidiary of Dubai Islamic Bank — rocked up 100% on its first day of trading, achieving market capitalization equal to the fair value assessments the scrip had been given in recent weeks. The first month of trading saw Deyaar retaining comparatively high price levels of 80 to 90% above its issue price.

Notably, however, the two UAE bourses diverged in September as far as their real estate stocks. The key sector companies on the DFM, Emaar and Union Properties, were rather listless in their share prices. On the ADSM, however, key players ALDAR and Sorouh recorded substantial gains in the latter part of September. Up until the summer, Emaar (and the DFM real estate sub-index that is heavily under its influence) stuck out as subdued performer while Union Properties moved more similarly to its ADSM peers. If real estate sub-indices on the two bourses maintain divergent trajectories over prolonged future periods, it could imply that investors perceive the Abu Dhabi property market as promising but have doubts about the sustainability of Dubai real estate prices.

Supply still has to catch up with demand

However, until now, “the supply of properties, whether in the residential, commercial, hospitality or retail segments of Dubai and Abu Dhabi alike, has yet to catch up with the ever increasing demand,” a report by Dubai-based Shuaa Capital said. “The result has been spiraling prices and rental rates for properties on the market and those in the pipeline,” it added, noting that prices have increased by 13.9% in the eight months leading up to August 2007.

Freehold house prices had more than doubled in the last two years because a fraction of homes under development had been completed, creating a short-term supply crunch. Yet, with many set for completion from 2008 to 2010, experts say the market is set to experience a “declining price” phase and that prices may drop 20% by 2010.

But market observers told Executive that the current market conditions for real estate in the UAE will not turn to the worse in the foreseeable future, that balance on the demand curve has definitely shifted, and greater hunger for residential and commercial property is predicted. “The extent of a correction is difficult to quantify since the economic business cycle does not appear to be at risk of suffering a decline over the forecast period,” Shuaa said in its report.

However, one thing is certain: the price rise can’t go on forever. If the real estate bubble bursts, the pattern will be different from that of a correction in equity markets. While the latter is characterized by huge trade volumes at lowered values, a collapse in real estate markets shows through illiquidity. The prices may not go down but transaction numbers melt away and distressed sellers have a hard time finding buyers. This is bad news for people who bought a home at a price they considered excessive on a rationale that the value of the property will still go up. After a property market correction, these people may have to wait for years for a buyer.

Possible correction in 2009

While international markets carry the memories of burst real estate cycles in the 70s, 80s, and 90s of the last century, opinions on the GCC market see the two possibilities of a sharp sudden drop or a soft landing. Prices will not go up indefinitely but a gradual slowing is a plausible scenario for many in the current positive economic environment of much of the region.

In its latest sector view, investment bank EFG-Hermes expects a UAE price correction in 2009, following upon “a rise in average prices of 10-15% in 2007 and a rise of 5-10% in 2008, with the peak being reached in 2H2008.”

Earnings of listed real estate companies in the UAE, so far, have been no cause of concern and it makes no sense to speculate on short-term weaknesses of publicly traded sector heavyweights, however disappointingly some companies may have treated their stakeholders.

Historic causes of real estate bubbles were in relation to the economy’s expansion low interest rates, scarcity of land, rapid accumulation of people in an area, and speculative pressures. Experts say if investors are concerned about real estate values and feel that the bubble might burst, than they must keep a close eye on long-term interest rates and the unemployment rate. If both of these rates start creeping up, it might be time to reconsider investment in real estate market.

Currently, the unemployment rate of locals in the UAE remains high and given that the emirates has its national currency tied to the US dollar creates a potential recipe for a bubble burst. Add to this the fact that that real estate companies in Dubai are already overvalued the chances for a burst become more acute.

But much can be done to reduce the risk of a stock market decline. For example, housing prices simply can’t continue to rise faster than wages do and wage increases must catch up to housing price increases. Furthermore, speculative excesses in markets will trigger downturns in real property valuations. As such, the government must take steps to end the speculative winds. Proper valuations of real estate firms are also in order. “Proper handling of the real estate market dynamics by the authorities will prevent a potential meltdown,” Samer Shaheen, a senior analyst at Zawya told Executive. “The UAE’s young markets lack a form of information sophistication. In-depth research on the property market to forecast trends are rare and much more on this level is needed.”

October 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
By Invitation

At a Crossroads: The Middle East transport and logistics industry

by Fadi Majdalani & Ulrich Koegler September 21, 2007
written by Fadi Majdalani & Ulrich Koegler

The Middle East has historically been a trade route for merchants, prized for its connections to both Europe and Asia. This history has laid the groundwork for a vast transportation and logistics network that is slowly emerging in the region and could be a significant source of economic growth for many years to come. The Middle East’s geographic location and excellent accessibility by air, land, and sea put it in a prime position to serve as a trade hub.

The trade volume between Europe and Asia is likely to continue to grow, as Asia has become a key production and manufacturing region for the Western world. Traditionally, air freight carriers used to stopover in the Middle East to refuel, halfway along this trade lane, and will continue to do so to maximize freight loads. However, volume growth on the Europe-Asia trade lane has increased the need for shippers to use larger vessels and apply more advanced logistics concepts. With product cycles speeding up, demand becoming less predictable, and companies managing their stock more closely, sea freight increases the risk of carrying outdated items. As air freight remains too expensive for most goods, the option of a conversion from cost-effective sea to air freight while en route becomes more significant. The Middle East is a natural location for sea-to-air conversion.

Beyond its potential as a global hub along the Europe–Asia trade lane, the Middle East can establish regional transport and logistics hubs serving northern and central Africa, Pakistan, and the Caucasus. The region has equal proximity to all these markets and very good connectivity by road and short sea transport. These markets currently lack access to competing regional centers, such as Europe and South Africa, and cannot yet afford the required infrastructure investments. Furthermore, as companies optimize their supply chains, it makes sense for them to establish a single regional distribution center in the Middle East for all of these markets. Increasing production capacity also underscores the need for a strong regional logistics sector.

Public Policy Steps for a Strong Industry

As Middle Eastern governments embark on the development of the transport and logistics sector to drive economic growth, it should be clear that the opportunities are not equally available to all countries. Hence, governments should consider four key building blocks for developing a successful transport and logistics sector strategy.

1. Choose a strategic play for the sector with appropriate infrastructure. The correct choice of one of the three strategic plays described hereafter needs to be based on a thorough and honest assessment of the qualifying factors. The global multimodal transport and logistics hub strategic play is the most demanding option, requiring a preferred geographic location and huge investments to create infrastructure incorporating a world-class airport and port zone. It also demands an economic environment that attracts foreign direct investment; the availability of a large free zone around the port-airport infrastructure; highly competitive handling charges; and living standards that accomodate a large expatriate community. However, there are very few truly global hubs: We predict that there is an opportunity to establish two global hubs in the region, and one will likely be Dubai.

The regional logistics and distribution hub strategic play requires similar elements but is less demanding in terms of overall size and multi modality. However, services and processes must adhere to the same high standards; the infrastructure must simultaneously provide good connections to global hubs and exporting countries, as well as excellent links to neighboring regional markets, via a strong road and short sea infrastructure. A few traditional gateways to the Middle East such as the Nile Delta, the Red Sea ports, Kuwait’s coastal area, and the northern shores of the Gulf could develop into regional hubs.

Finally, countries that cannot meet the needs of a global or regional hub play should focus on the development of domestic transport and logistics services.

2. Adjust policies and regulations to promote sector development. These should promote foreign direct investment, provide a liberal economic environment, and allow for full foreign ownership of the respective local entities.

3. Optimize government services to meet the demand of the logistics sector. The key government services required by the logistics sector fall into three areas: business and equipment licensing, regulatory oversight and competitive regulation, and customs services. Optimization of government services in the first two areas should be part of a broader economic development program to promote and foster entrepreneurial activity. Transactional customs services should be automated as much as possible and seamlessly integrated into the logistics service providers’ order management systems.

4. Promote the development of national transport and logistics champions. In most countries in the region, the industry structure of transport carriers and logistics service providers is still highly fragmented and often not developed.

The development of a strong domestic transport and logistics sector is a strategic imperative for economic development in the Middle East. The countries that succeed at establishing sustainable networks can expect to see increased economic activity, improved industry competitiveness, and growth in job opportunities. Those that do not, however, may find themselves falling by the wayside.

September 21, 2007 0 comments
0 FacebookTwitterPinterestEmail
Comment

Musings from Arab America

by Norbert Schiller September 21, 2007
written by Norbert Schiller

During our holidays this summer we were fortunate to be able to stay with my wife’s extended Lebanese family on both the east and west coasts of the United States. It had been almost six years since we last visited, and I must say that staying in an Arab-American household lessened the shock of fitting into the American way of life; a kind of decompression chamber if you will. Behind closed doors nothing really changed; the family was as tight-knit as ever and if it wasn’t for the green lawn outside the window and the lack of blowing horns and shouting in the streets we could have all been sitting in Beirut.

Both Lebanese-American families we stayed with were forced to leave during war. The husband of my wife’s cousin, who is originally Palestinian, remembers when in 1948, at the age of eight, he was forced to flee his village in northern Palestine after the Arab armies advised the inhabitants to leave because “the Jews are coming to take your land.” He made his way to southern Lebanon by holding onto the tail of his uncle’s donkey. On the east coast, my wife’s brother and his wife fled Lebanon for the United States in the mid-1980s, during one of the darkest chapters of the civil war.

Obviously, for my wife and her family, the first few days were consumed by relaying and absorbing Lebanese and Diaspora news: the physical changes taking place in Lebanon (the pulling down of the grand old building around the corner that once belonged to so-and-so) and how much of the country has been restored a year after the war with Israel.

However, unlike previous visits, the solid opinions that my wife’s family once held true were now blurred and the issues watered down.

When we first traveled to the States in the early days of our marriage 15 years ago, Lebanon was always on the forefront of every conversation. One misplaced word or train of thought could trigger an all out major debate on Lebanese politics that would result in phone calls to friends and family across America and even a call to Lebanon if it meant proving a point. Now that has all changed.

It’s not hard to explain this waning interest. American press coverage of the Middle East is something you have to actively seek out. Even with the 500 plus stations available to most cable subscribers, if you don’t have your own satellite hook up, you are not privy to all the international news stations like CNN International, BBC World, Al Jazeera, and LBC International. The newspapers inundate readers with local news, followed by a bit of national news and then a blurb here and there from the rest of the world. If there is something from the Middle East, it will probably be about Iraq and even then there is a good chance it will have a local angle. 

In the past, I remember always seeing a second, more international, newspaper lying around — the New York Times or Los Angeles Times — but now, with time, I notice that my wife’s family are slowly becoming more interested in the news that affected them on a daily basis. Even when we were visiting, they tended to veer away from the Middle East if some local issues, like the rise in crime, a garbage collection strike, or the bridge collapse in Minneapolis there was more anguish — “Haraam, they were just going home from work” — than for any car bomb outrage in Iraq.

One family member told my wife that she felt that her generation had “missed all the boats.” They had missed Lebanon’s golden era, caught the war and then had to endure all the insecurities of living as immigrants in the United States. And then came 9/11 with all that feeling of not belonging and being seen as outsiders. Her only consolation is that her children will hopefully feel more grounded and not live forever in search of a homeland.

September 21, 2007 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

by Executive Contributor September 20, 2007
written by Executive Contributor

Ithmaar Bank posts 130% in H1-07 net profits

Ithmaar Bank, a Bahrain based global investment institution, announced a 130% increase in its H1-07 net profits to $65.09 million up from $28.7 million for the same period last year. As a result of their expansion, Ithmaar experienced a tripling of operating profits from $23.7 million in the first half of 2006 to $71.1 million in the first half of 2007. Income from investment in financing amounted to $97.8 million, while $25.4 million was generated in fees and commissions and $23.1 million was generated from sale of investment securities. Total assets, including funds under management stood at $5.1 billion at the end of last June, compared to $4.4 billion at the end of last year. Ithmaar is growing at a rapid pace and is one of the most dynamic financial institutions in the region covering a wide range of Islamic financial services and investments. Ithamar’s wholly-owned Ithmaar Development Company (IDC) has made considerable progress in several major projects with the Kingdom of Bahrain and internationally.

Emaar ranked in top 10 of S&P Index

Standard and Poor’s (S&P’s) ranked Emaar Properties PJSC, the UAE-based real estate developer, in the Top 10 of IFCG Extended Frontier 150 Index for frontier equity markets. Attaining the highest weight of 5.59% in the index reflects Emaar’s strong regional presence and growing international recognition. The Extended Frontier 150 Index plans to accommodate the needs of increasingly sophisticated investors willing to expand in developed and emerging markets. This year, S&P Rating Services and Moody’s Investor Services assigned Emaar A- and A3 ratings respectively, with steady outlook reflecting the company’s strong financial profile.

IMF forecasts strong growth for Syria in 2007

In its latest report, the International Monetary Fund (IMF) highlighted the strong economic performance of the Syrian economy in 2006 and has forecasted a positive outlook in 2007. According to the report the economy’s supply responsiveness, the tighter credit policy and the fiscal discipline have contributed in tightening inflationary pressures caused by the large demand shocks from Iraqi investors. The report assessed that Syria needs to maintain a strong external stability over the medium run, which can be achieved through strong fiscal adjustments, accelerated structural reforms and exchange rate flexibility. The IMF regarded the Syrian private banking sector promising despite the possible drawbacks it might face in developing reforms. In addition to that, vital action is needed for the state banks to attract the accumulation of non-performing loans and enhance competition. Finally, Syria’s economy is in need of progress in developing market-based instruments for monetary control and should reduce the excessive risk taking as well as dollarization.

September 20, 2007 0 comments
0 FacebookTwitterPinterestEmail
North Africa

Tunisia  Emirati Dreaming in Tunis

by Executive Editors September 20, 2007
written by Executive Editors

Bilateral relations between the UAE and Tunisia are set to expand with leaders from both countries being keen on promoting joint-investment projects to enhance social and economic relations.

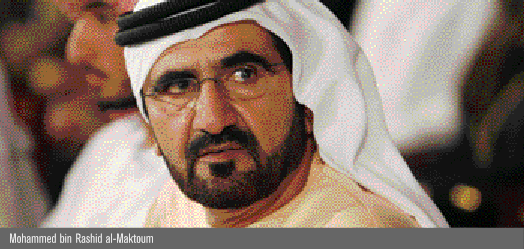
On his recent visit, HH Sheikh Mohammed bin Rashid al-Maktoum, vice president and prime minister of the UAE, expressed that the enhancement of bilateral relations is a starting point “towards wider avenues of mutual economic, technological and tourism cooperation.” He also added that such cooperation is a significant step in “embodying the deep fraternal relations and the common history of our two countries and peoples and building new bridges between the eastern and western Arab countries.”

The most recent joint-investment agreement between the two countries was part of a ceremony held during the visit of Sheikh Mohammed to Tunisia. Together with Tunisian President Zine El Abidine Ben Ali, the two leaders laid the foundation stone of a $14 billion real estate and investment development set to provide housing for half a million people. The mega real estate development project on the southern lake of the Tunisian capital is a joint venture between Sama Dubai, the international investment arm of Dubai Holding and the Tunisian government. The development will cover some 850 hectares and offer all the services of a satellite city, including retail and entertainment centers along with apartments, luxury hotels, a wide range of recreational and sports facilities, and up market housing.

Called the Century City and Mediterranean Gate, the development is intended to serve as a business hub, with office space for more than 2,500 international firms, with an emphasis on those in the financial sector. Businesses located there will benefit from state of the art communications infrastructure and impressive architecture. The centerpiece of the project will be two massive towers.

Additionally, the new city will play a major role in the country’s tourism industry, boasting 14 high class hotels and resorts, leisure and sporting facilities and a marina as part of the design.

Century City will be the single biggest investment project in Tunisia’s history, and will make Dubai the largest foreign investor in the country. The $14 billion price tag eclipses TECOM Investments and Dubai Investment Group’s acquisition of a 35% stake in Tunisie-Telecom in 2006 — valued at $2.25 billion.

According to Mohammad al-Gergawi, Dubai Holding’s chief executive officer, Sama Dubai expects to raise investment in Tunisia from $3 billion to $18 billion in the near future.

The potential for Century City to attract further foreign investment through companies relocating to the vast business district, drawn by the opportunities presented by a new city of up to half a million prospective customers, is undoubtedly welcomed by the Tunisian authorities.

State projections predict the work will add 0.6% to the country’s growth rate for a period of up to 15 years, and provide jobs for 130,000 people during the construction phase, pleasing statistics considering that unemployment is running at more than 14%, according to official figures.

Agreements signed between the state and Sama Dubai specify that most workers on the project will be Tunisians and the company will provide them with specialized training.

Al-Gergawi said actual work on the project will begin in the next few months. “The scheme is very important so it will be done in stages,” he commented. “It requires 10 years to be finished.” Al-Gergawi stated that Tunisia had been chosen as the site for the development by Sama Dubai because the country has potential to become a promising regional economic center, thanks to its position as a gateway to many other destinations. The growing services sector and the favorable investment regime were also strong attractions, he told a press conference in early August.

September 20, 2007 0 comments
0 FacebookTwitterPinterestEmail
North Africa

Morocco  Linking the continents

by Executive Editors September 20, 2007
written by Executive Editors

The construction of an undersea tunnel linking Morocco and Spain has been on both countries’ agenda for over 25 years now. Today, the idea is closer to materializing than it has ever been before.

After rounds of geological tests and feasibility studies run by specialist independent geotechnical consultants from the Swiss engineering company Giovanni Lombardi, the project looks to get a go ahead by the end of 2007. The cost of this project has been estimated to exceed $13 billion and initial studies by engineers forecast a project length of up to 25 years.

It is predicted that the tunnel could carry 9 million passengers and 8 million tons of freight annually. There is a potential for boosting the economies of both nations as well as mutually improving tourism and trade opportunities. Currently, Moroccan exports to EU countries account for 73.8% of total export revenues and generate $12.76 billion (or 22% of current GDP) annually. In return, Morocco receives 65.1% of its total imports from the EU, the bulk of which are transport equipment and machinery, which contribute to Morocco’s automotive industries. Additionally, agricultural exporters would be set to gain a strong advantage from this transport development, being able to send some of Morocco’s more delicate exports such as flowers and tomatoes by train instead of ship.

The growth in the number of European tourists to Morocco has given further impetus to ambitions to link Spain and Morocco across the Strait of Gibraltar.

Morocco’s tourist industry witnessed a successful first half of the year with EU figures showing over 2.26 million visitors from January to June 2007, representing a 7% increase in year-on-year terms. As such, the country is keen further to improve the accessibility of its tourist sites by moving ahead with the Gibraltar tunnel project.

European tourists

According to the Moroccan Ministry of Tourism, European arrivals to Morocco account for 83% of 2007’s arrivals to date, with French visitors leading the pack with 873,000 visitors in the first six months of 2007, an increase of 4% on last year. Visitors from Spain and Britain accounted for 479,000 and 175,000 visitors respectively, with British tourist arrivals recording a 43% increase as a growing number of no-frills airlines such as easyJet and Ryanair are making the country more accessible with flights to Marrakech, Casablanca and Fez. Germany, Belgium and Italy are also important markets, each accounting for approximately 100,000 visitors. The three most popular tourist destinations have recorded growth in the number of visitors in the last six months; Marrakech has seen a rise of 12%, Casablanca recorded a 9% rise and the coastal resort of Agadir saw a 3% more visitors than in the same period last year.

The construction of the proposed Gibraltar tunnel is a joint venture between government agencies Société Nationale d’Études du Détroit (SNED) in Morocco and Sociedad Española de Estudios para la Comunicación fija a Traves del Estrecho de Gibraltar (SECEG) in Spain. The tunnel would consist of a 39 km passenger, car and freight rail line running across the strait connecting the cities of Tarifa and Tangier. Its deepest point will be 300 meters.

The next step will be to consider a number of logistical challenges. Even though the distance across the Strait of Gibraltar is 14.5 km, the challenges posed to engineers by a Morocco-Spain tunnel are far greater than challenges facing engineers during the “Chunnel” construction between England and France, which lie 32 km apart at the Strait of Dover. The water is deeper; nearly 1000 meters at the shortest route across the strait, compared with just 61 meters in the English Channel. Another challenge is the texture of the earth. The first test diggings over 10 years ago revealed that the soft earth near Tarifa is not suitable for building a structure of this type. Recent tests have re-confirmed this and so Cape Malabatta has been selected as the entrance point to Morocco, after which the tunnel will continue to Tarifa. Additional concerns include securing the tunnel against human trafficking between Africa and Europe and whether the there will be a sustainable flow of goods and people in both directions given the economic disparities between the two continents.

Yet leaders of both countries are keen on proceeding. Spanish Prime Minister Jose Luis Rodriguez Zapatero has said that he is fully committed to the project. According to the minister the tunnel would “greatly speed growth, development and prosperity” on both sides of the Mediterranean. The goal behind the construction is to create “an integrated Euro-Mediterranean economic area” and possibly lead to developing the transport network further to include a link between Marrakech and Europe.

September 20, 2007 0 comments
0 FacebookTwitterPinterestEmail
North Africa

Algeria  Taking out Trabendo

by Executive Editors September 18, 2007
written by Executive Editors

The part-privatization of Algeria’s ports to major operator Dubai Ports World (DPW) has been hit by a series of rolling strikes by trade unions. The potential unrest stems from talks the government is holding with DPW over the company possibly taking a 50% stake in the container terminals at the ports of Algiers and of Djen Djen, in the eastern province of Jijel.

Algiers port has reached saturation point and will need considerable investment to extend it. However, the stumbling block at the moment is the plan to include the potentially highly lucrative Djen Djen port, and disagreement over the issue of bringing in a foreign owner. Some also point to the possible disquiet of those involved in the “trabendo” economy, or contraband imports, as looking to scotch the deal to preserve their lucrative, if illegal, niche.

Djen Djen’s port is something of an oddity, having been built to serve a steel plant that was never constructed. However, it has developed as a major point for container and dry cargo transport (notably grain) abroad. The purpose-built port also benefits from very good land transportation links, as well as deep water piers accessible to ships of up to 120,000 tons.

Local media have reported that DPW made a $70 million bid for the operation of the Djen Djen port, coupled with a $120-150 million investment program to upgrade it. In June, the transport ministry announced that negotiations were making good progress.

“Dubai Ports World took into account the principal requests of the Algerian side at the time of the first round of negotiations, which was held in Algiers on June 12,” the statement said. “We will be able to advance.” The deal seemed to be likely to be finalized by year’s end, officials have been reported as saying.

However, the umbrella union Coordination Nationale des Syndicats des Ports d’Algerie (CNSPA) has objected strongly to the plans to change the port’s ownership and their employer and threatened to block the deal.

One source of discontent is the government reneging on a pledge made by the minister for investment promotion, Abdelhamid Temmar, to tender the sale internationally rather than moving immediately to negotiate directly with DPW.

CNSPA has a membership of 14,000 across all of Algeria’s 10 most important ports, giving it a great deal of leverage in the situation, as has been show in the past. Strikes by CNSPA-affiliated unions in October 2005 against government privatization and labor restructuring plans left 100 ships abandoned by workers. The Port of Oran alone, where 15 ships were left stranded, hemorrhaged $130,000 a day during the industrial action. In May of this year, another anti-privatization strike shut down almost all Algeria’s ports, causing losses of up to $2.1 million in a single day.

Guermache Abbes Maamar, the secretary-general of the Algeirs port trade union, has said that opposition to the proposed deal with DPW was in the national interest and not only an issue of workers’ rights.

Maamar questioned the wisdom of “giving away” container activity, which generates 70% of the port’s receipts, in return for the proposed investments DPW has put on the table. The unions agree that Djen Djen is in need of an overhaul, but Maamar proposed that the government work with its port management authority Entreprise Portuaire d’Alger to develop the nation’s ports, rather than using foreign firms.

“We can do everything between Algerians: to buy gantries and all the equipment to improve the output. We cannot release sovereignty on the ports,” he added.

To break the current deadlock, it has been suggested that the unions should be involved in future privatization negotiations to ease the tension and distrust. However, it seems that the CNSPA is unlikely fully to embrace partial privatization to DPW. Meanwhile, private sector companies involved in trabendo activity at the ports are also against the deal. Many are believed to be involved in illegal practices which they fear the Emirati company might eliminate if the deal goes through.

September 18, 2007 0 comments
0 FacebookTwitterPinterestEmail
North Africa

Algeria  Building the Gas Bridge

by Executive Editors September 18, 2007
written by Executive Editors

Algeria, the world’s fifth largest gas producer, is supplying around a quarter of the EU’s gas imports, and is hoping to expand further into that market. Its valuable position is firming with pipelines under construction to southern Europe and liquefied natural gas (LNG) deals with northern Europe. And although Russia remains the major gas supplier for the EU, Algeria’s flexible gas sector and geographical location are factors playing in its favor.

On July 12, Algeria and the EU finalized an agreement dealing with territorial restrictions, allowing companies of EU member states that import Algerian gas the right to resell it either within their own domestic markets or to third-party countries.

In return, Sonatrach, Algeria’s state oil and gas company, will have the right to a share of the profits earned by European companies, for LNG contracts only. Sonatrach will also be allowed to sell LNG shipped by tanker directly on the European market.

The deal will consolidate Sonatrach’s position as one of the main suppliers of natural gas to the EU, with Algeria behind only Russia and Norway.

Deepening the Algeria-EU relationship

Chakib Khelil, the Algerian minister of energy and mines, said the agreement was a further step toward deepening the strategic relationship between Algeria and the EU. “Algeria supports the establishment of Sonatrach as an active player in an open, transparent and competitive EU gas market,” Khelil said at a signing ceremony in Brussels, where the final details of the deal were hammered out after lengthy negotiations.

The EU’s Competition Commissioner, Neelie Kroes, also attended the ceremony. “The agreement reached constitutes a major breakthrough in our relations with one of Europe’s most important suppliers of natural gas and eliminates an important obstacle for the creation of a single EU-wide market in gas,” said Kroes.

The agreement with Algeria was essential for the EU, having launched the fully deregulated energy market within the bloc on July 1, allowing clients to choose their preferred suppliers of electricity and gas, rather than be tied to state operated utilities that continue to dominate energy markets in some EU member states.

Algeria agreeing to allow the unrestricted sale of its gas to third parties means that its present and future contracts are now in keeping with the EU’s new open market policy. Algiers had long held out against the ending of destination restrictions, fearing the move could result in wholesale reselling of its gas without any benefits coming its way.

Algeria’s long running dispute with Spain, over restrictions on how much of the gas piped through the Medgaz gas pipeline Sonatrach is allowed to sell directly on the Spanish market, appears headed to the courts.

The Algerian company has been limited to selling no more than 1 billion cubic meters of gas annually in Spain, despite being the largest single shareholder in the Medgaz project, with a stake of 36%. Sonatrach hoped to sell up to 3 billion cubic meters of gas a year.

At the beginning of July, Khelil said that Algeria would lodge an appeal against the Spanish energy watchdog’s ruling to limit Sonatrach’s sales.

“We will lodge an appeal with the higher authorities in Spain …  as well as the European Commission,” Khelil said. “What we are asking is to be treated like any other operator, Spanish or otherwise, whether for the distribution of gas or for the shares in the Medgaz project.”

Algeria and Spain are also involved in international arbitration over Sonatrach’s demand that the price of Algerian gas imports be increased in two stages by 20%, to keep the tariff in line with world prices. At the present rate, Algeria stood to lose around $300 million annually, according to Khelil.

Only days after the agreement was signed, Algeria moved to strengthen its energy production infrastructure, announcing more than $4 billion worth of construction tenders for new processing facilities.

In mid-July, Algeria awarded French firm Total the $3 billion tender to construct and operate a cracking steam facility with the capacity to produce 1.4 million tons of ethane annually. The plant will also produce polyethylene and ethylene glycol, with Sonatrach funding 49% of the project and Total the remaining 51%.

The same day, Sonatrach and a consortium of foreign firms, including Mitsui of Japan and Kuwaiti company Qurain, were awarded the contract to build and operate a $1 billion methanol plant with a projected output of 1 million tons a year. Again, Sonatrach will hold 49% of the project, with the other members of the consortium combining to take the rest. With so many projects in the pipeline, the future of the petrochemical industry in Algeria seems to be brighter than ever.

September 18, 2007 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 562
  • 563
  • 564
  • 565
  • 566
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE