• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Comment

“Month of Mayhem” in Iraq

by Michael Holmes April 1, 2007
written by Michael Holmes

This was my eighth visit to Baghdad—in many ways, Baghdad feels like a second home, which I’m not sure is a healthy sentiment—my first being as the war wound down in 2003. I cringed a little when told the documentary would be called“Month of Mayhem.” It proved to be a more than apt title.The previous seven “tours” had allowed me to witness a steady deterioration in the level of security and services—despite my hopes, it was always, always worse. AndI knew this trip would likely be no different. It really becomes a matter of how bad it’s going to be. Before leaving the airport—before leaving home, for that matter—I know there will be bodies, and there will be bombs—it is only a question of who and how many.

A bloody time for Baghdad

As it turned out, this visit would see one of the bloodiest periods since the war began.

Within 10 minutes of reaching the bureau, I was live on air reporting on the battle for Haifa Street, as US andIraqi forces fought Sunni insurgents and al Qaeda elements not more than a mile or so from our office. All day, the air was rent by the sounds of small arms fire, heavy caliber machine gun fire, and missiles fired from the Apache helicopters that swooped low over our heads.

CNN’s Arwa Damon being in town ended up being a boon for me. She was embedded with a Stryker Unit and this allowed me to largely escape the routine of “live shots” from the bureau and embed with the military for much longer than usually possible on a five-week assignment. Embedding with the military has become the safest way of reporting, not just on the war, but on Iraqi civilians. It’s about the only way we can safely meet with ordinary residents, talk to them on and off camera and get first hand accounts of the awful tribulations they endure.

This was a month of massive bombs at universities and market places, of more and more bodies dumped in the streets, hands bound and shot after being tortured in almost inconceivable ways, including the use of electric drills. It was a month when what the US called its “troop surge” began, when the “Baghdad Security Plan” got underway, when the first Joint Security Stations were being set up.

The severity of the security situation is well illustrated by the embed in Adhamiya, an area about six miles from our bureau, but considered by our security advisors too dangerous to drive. Roadside bombs and ambushes are common.

Each time I return, there seems to be a new “worry” among the troops. This time it was the increased sniper activityand the growing threat of EFPs, or explosively formedprojectiles. These are savage weapons—“shaped” charges thatfire out a ball of molten copper, or similar metal. RegularIEDs were described to me by one soldier as “like a shotgunblast.”

“EFPs are like an armor piercing bullet aimed at your head,”he said.

A month of laughter and tears

I met another soldier who’d been “blown up” as he put it, four times, by IEDs, and wounded three. It was his first day back after his latest medical leave, and he was the driver in my humvee. Another soldier told me about an EFP that hit a humvee he was driving. It went through the right rear window of the vehicle, decapitated the soldier sitting there, took the legs off the gunner in the middle, took the head off the soldier in the left rear seat and continued out the window.

And this happened to an “up-armored” humvee.

During that month, we laughed in our bureau—you have to laugh—we had a party or two with our competitors inside ourcompound, we flew in helicopters, drove in Strykers and humvees and Bradleys. And we saw incredible suffering and loss. I left feeling that some positive things were being put into effect. And a stronger feeling that most of those things were about two or three years too late.

I’ll go back, later this year. Because I need to. BecauseI feel honored in many ways to, as a journalist, have the opportunity to cover this story up close. Because, like most of us who come—many for much longer periods than I do—I care.

MICHAEL HOLMES is a co-anchor for CNN International’s rolling newscast ‘Your World Today’
April 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Lebanon

Al Waseet pushes into region

by Executive Staff April 1, 2007
written by Executive Staff

The market for consumer goods has never been moreprosperous, according to recent advertising businessstatistics. Classified Intelligence reported the market forclassified ads accounted for $30 billion in 2003 in theUnited States alone, a figure that also includes newspapersand online websites. During the same year, the global marketwas estimated at over $100 billion. In the Arab region, AlWaseet classifieds boasts over 4.7 million copiesdistributed weekly and a readership base of over 20 million.With its 26 operations and staff of 5,000, Al Waseet ispresent nine countries across the region.

“Al Waseet provides a medium for people to buy, sell andexchange goods, keeping them updated with the latestpromotions and products featured within eight differentcategories,” said John Fawaz, the company’s managingdirector. Al Waseet includes listings for real estate, jobs,automotive sales, electronics, technology, hobbies and otheritems, and a personal classifieds section entitled BigHeart.

Based in Dubai, Al Waseet International (AWI) is part ofAl Wataniya Group, which owns numerous publications,including Al Balad newspaper, as well as the Layalina, AlHayat and Laha magazines. Operating in Syria and Kuwait,Baladna newspaper, Top Gear, What’s On and Concord OutdoorMedia are also part of the Al Wataniya group. Founded byBashar Kiwan, Mohammed Abdulaziz Al-Otaibi, Sheikh SabahJaber Al-Sabah and Majed Suleiman—who came up with theoriginal concept—AWI’s 26 publications are featured in asmany as 23 cities.

100 Branches by 2012

“Our expansion plan targets 100 branches by 2012, withcoverage spreading beyond the Middle East and Africa,” saidFawaz. In keeping with the company’s growth, an Englishversion of Al Waseet was made available in places likeKuwait, Cairo and Dubai, where there are largeEnglish-speaking populations. To further strengthen its gripon the market, the company also chose to pursue corporateinvestment and franchising deals.

“With AWI’s experience and successful internationalexpansion, no company is more fit to establish a lucrativebusiness model that can be emulated and operated profitablyanywhere in the world. Franchising, therefore, makes a lotof sense for us and has become a crucial step in thecompany’s development. It will undoubtedly take the AlWaseet business model to the next level,” continued Fawaz.

Franchising as a sustainable business strategy dependsprimarily on AWI’s performance in the media advertisingsector. Backed by an efficient market research departmentand advanced computer software, the company is able todetail business processes from marketing protocols todistribution methodologies. In addition, franchisees can gethands-on experience by visiting the Al Waseet Showcase inDubai, a fully functioning Al Waseet branch that serves,according to the company website, as a franchise trainingcenter. The franchise agreement that was recently signedbetween Al Waseet and Nigerian Middle Advertisement Limitedunderscores the company’s approach towards securinginternational stature.

To enhance Al Waseet’s position as a major advertising andmedia player, management has relied on local marketingcampaigns to create brand awareness. Launched regionally,this year’s advertising campaign adopted a unified messagethat was expressed individually according to differentmarkets. “We have the advantage of being a media companythat has companies like Al Wataniya as media partners, whichprovides us with wider coverage. In terms of BTL [below theline strategy], we follow the same marketing approach usedin the FMCG [fast moving consumer goods] business, thusproviding fully-branded materials to various POS [points ofsale] and PODs [points of distribution],” said Fawaz.

The high market penetration and circulation rates indicatethat the company’s marketing approach has thus far been asuccess. Company figures show that 4.7 million copies aredistributed every week, with Saudi Arabia proving thelargest market with a total weekly circulation of 1,050,000copies. In Dubai, Al Waseet’s new English version is showingpromising results with 200,000 copies distributed weekly.The overall Al Waseet market share for the UAE is estimatedat 92.04%; in Kuwait, it reaches 32% and in Syria, 56%.

“With 20 million weekly readers, Al Waseet is currentlythe only regional publication offering such wide coverage,with a cumulative market penetration of 77%. Although westill face competition in many markets, we remainnonetheless leaders in our category,” Fawaz pointed out.

Fawaz added that the very nature of Al Waseet, a massproduct that can be easily positioned in any market,provides an open door to a world of unlimited opportunities.It is for this reason that the company intends to pursuecorporate expansion by identifying new potential markets,opening new branches wherever internal criteria fordevelopment are met.

Focused on small to medium clients

In terms of readership, Al Waseet focuses on small tomedium clients, including corporations and advertisingagencies. In addition to regular ads, Al Waseet alsoprovides mailing services based on geographic location,demographics, nationality, profession and income, withneeds, wants and purchasing habits varying from one marketto the other. Targeted mailing also includes VIP listingsand identifying key figures. “Al Waseet was the first freeweekly classified publication to be distributed door todoor. Today, our regional network is our main competitiveadvantage,” said Fawaz.

AWI is in the process of restructuring call centers toimprove the quality of services and customer satisfaction.It intends to add new products to ranges already offered. The Al Waseet website has also been overhauled and is nowcalled ewaseet.com. “With its new look and features, weexpect ewaseet to provides us with a separate source ofincome and generate revenue once it is launched properly,”underlines Fawaz. The website offers online brandingsolutions, which includes above the line advertising,classifieds and targeted advertising. According to thecompany website, with its 90,000 registered members and200,000 visitors, “the portal serves over 2.2 millionvisitors per month.”

This year, Al Waseet has acquired licensing rights for theGuinness World Records for the MENA and the GCC regions.This includes publishing and distribution activities as wellas management of all related PR events. “Now that we havesolidly established our SOPs [Standard OperatingProcedures], we can say that we are paving the way towardsstock market entry. The IPO is very much on top of ouragenda, but it is not an easy step to take, and requiresmuch preparation,” conceded Fawaz.
 

Al Waseet market share in Kuwait. source: Al Waseetwebsite, Ipsos stat 2006.
Al Waseet market share in the UAE. Source Al Waseetwebsite, Ipsos Stat 2006


April 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Lebanon

Cry of despair for investments: Habtoor blames Lebanon

by Executive Staff April 1, 2007
written by Executive Staff

I came to Lebanon as an investor believing in the law,constitution and state of this country and I believedstrongly enough to invest hundreds of millions of dollars,”said Khalaf Habtoor, founding father and chairman of theEmirati Habtoor Group. “However, despite the existence of apolitical and legal framework, law and order is not beingimplemented. Investments in Lebanon have been significantlydamaged by political, economic and social instability,created by the Lebanese system.”

Habtoor Group is one of the main foreign investors inLebanon, with such assets as the Metropolitan Hotel, theHabtoor Grand Hotel and Habtoorland. Due to the summer warand ongoing political crisis, the hotels have laid off mostof their staff, while the amusement park has closed downcompletely. No wonder, Habtoor on March 20 asked someunsettling questions, as he delivered a message of anger,despair and bitter disappointment.

“Protests, affirmative action and terrorist activities takeplace in many countries. Lebanon is not alone in this,” hesaid. “The difference is that in other countries life is notbrought to a standstill. Did London close down for weeksafter the subway blast? Did Egypt, Morocco and Jordan cometo a complete standstill? No. The situation was contained bythe state, and authorities made sure that businesscontinued.”

Not so in Lebanon, where the seemingly endless politicalcrisis increasingly paralyzes the economy. Emphasizing he isnot engaged in politics on either side of the Lebanesedivide, Habtoor firmly pointed his finger not at theopposition or government, but at the shortcomings of theLebanese system.

“The state should take care of the welfare of the countryand people and should have policies and decisions firmly inplace,” he said. “Lebanon needs foreign investments as itneeds to create employment, and for that it has to ensurepeace, justice to all and security to the investor. Why isthe state unable to protect interests and security, despitehaving a full fledged army and police force?”

According to Habtoor, “a ship has only one captain andcannot navigate a rough sea if the power is diluted.”Lebanon’s lack of unity and true leadership is onlyaggravated by the fact that “local and governmental bodiesact as independent authorities. Each and every corner of thecountry has its own ruler and for every few villages anautonomous municipality functions without state sanction.”

As an example, Habtoor cited he was never told by localauthorities that there was an army firing range next toHabtoorland and, while the Habtoor Grand Hotel was ready foroperation by August 2005, the opening suffered excessivedelays, as an operating license was denied, even though thehotel was built according to prior approval.

Habtoor is not the sole investor with such grievances. Dueto the continuing unfriendly investment climate in Lebanon,a number of Arab and Lebanese investors have approachedHabtoor to join them in suing the Lebanese state at theUnited Nations Commission on International Trade Law.

Habtoor, who was decorated by Lebanon’s president in 2002,blamed the Lebanese and their frail political system for hismisery. “I think that the only fault I committed was that Iever believed in Lebanon.”

April 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Lebanon

The ABC Group does retail by the letter

by Executive Staff April 1, 2007
written by Executive Staff

According to the latest figures in the retail real estatemarket, the sector is growing faster in the Gulf than in anyother region. The business website AME Info reports that by2010, nearly 50 million square meters of gross leasable area(GLA) will be available in the area, with the UAE and SaudiArabia taking up 44% and 30% of the pie, respectively. By2009, Dubai is also expected to have the highest retailspending in the GCC, beating out Saudi Arabia, despite itssmaller population. The city is gearing up for this increaseby building giant malls, such as the Dubai Mall, which isbeing hailed as the largest in the world. Hoping to cash inon this growing trend is the ABC Group—operators of the ABCdepartment stores and malls—which is scheduled to open two stores this year in Bahrainand Amman.

From the original store that was located in old Beirut onBab Idriss Street in 1936, the ABC Group has since morphedinto an expansive department store, with two shoppingcenters and a number of additional stores, including twonewly-added cosmetic and perfume outlets, under its belt.Despite the civil war that first claimed the Bab Idriss shopin 1976, followed by the 1982 destruction of the Hamra andTripoli stores, ABC has managed to become a member of theInternational Association of Department Stores (IADS),boasting retail spaces of over 60,000 m2.

Leader in Lebanon

According to figures provided by ABC, the Group enjoysone of the highest brand awareness rates in Lebanon,estimated at 97%, while 76% of consumers shop at one or moreof its locations. Within its first year of operation in2003, the ABC Mall in Ashrafieh was visited by five millionshoppers, with the number of visits to the Dbayeh mallamounting to 2.5 million per year. Branching out with ninedepartment stores into various Lebanese regions, such asBeirut, Zahleh, Kaslik and Tripoli, the company is supportedby a staff of over 600 employees.

The ABC concept as we know it today has shifted away fromits original exclusive focus on retail activities. “Thecompany started first as a regular retail business, addingat a later stage a real estate arm in charge of building,developing and leasing retail space, which resulted in ashopping center, comprising an inclusive ABC departmentstore,” said Robert Fadel, ABC’s director. This shift instrategy was marked by the construction of the Dbayehdepartment store, where for the first time, space was rentedto retail businesses. This move was subsequently followed bythe construction of the 42,000 m2 Ashrafieh mall. Otherservices, such as child daycare, information desks, weddinglists and a car wash were also added to the initial basketof products offered by the Group.

Expansion into foreign markets seemed like the naturalnext step. Prompted by booming Arab markets, Lebanese marketlimitations and a teetering political situation, variousfactors conspired to export the ABC concept to the MiddleEast. In the Jordanian and Bahraini markets, consideredstepping stones in the company’s overall expansion plan, thebusiness model adopted was either inspired from the Lebanonexperience or completely overhauled. “Occupying a 4,500 m2surface, the Amman department store will be similar to theBeirut one, although it will be developed on a smallerscale. The Bahrain 1,500 m2 concept store, however, focuseson women’s apparel, which includes accessories, shoes andlingerie,” added Fadel.

Positioned as mid- to high-end outlets, the ABC departmentstores offer various international brands, such as Carol,Tintoretto, A Priori, McGregor and Kookai, as well as luxuryitems from Chanel and various jewelry designers. The storesalso provide tableware and household items, shoes,accessories, cosmetics and perfumes, which are sold atcompetitive prices. With over 100 international, regionaland local brands holding sales stands at ABC, the group isthe largest retail developer in Lebanon, incorporating over200 tenants. Within the Middle East, the Bahrain and Jordanstores will also be positioned in the middle range of theretail spectrum, with Debenhams on the lower end and HarveyNichols on the higher end. “Besides these two contenders,basically anyone in the fashion industry is our competitor,”said Fadel.

Expansion plans

Collections on display in the Jordan and Bahrain storeswill also differ from the ones available in Lebanon, as aresult of differing store sizes as well as conflictingrepresentation and exclusivity contracts, a problemcurrently under examination by the ABC management. “TheAmman store will, however, include ‘shop-in-shops,’ such asKookaï or Chanel,” Fadel pointed out.

Despite expansion into foreign markets, ownership of thecompany will not be affected. “The company is owned up to80% by the founding family, with the remaining 20% dividedamong 100 shareholders,” explained Fadel. Owners also relyon a flexible structure based on three core activities:operation and services, leasing, and merchandising andmarketing.

Operation and services, the first sector of activity, isunderpinned by support services—including HR, purchasing,MIS, design and in-store marketing, maintenance,warehousing, finance and legal office departments. Store andmall operations are divided by area—including Dbayeh,Tripoli, Zahleh, Hamra, Ashrafieh, Kaslik and Furn elShebbak—and overall mall management. Leasing, the secondcore activity, is dependent on the company’s real estatearm. Lastly, the marketing activity involves events andpromotions, customer relationship management (CRM), marketresearch and communications. Purchasing is in charge ofregrouping ladies’ and men’s wear, shoes, lingerie,children’s wear, home items, appliances, toys andaccessories under one roof.

While the Group’s larger projects in Lebanon requiredmajor investments—the company’s total assets are currentlyestimated at over $100 million—the Bahrain and Jordanventures will require less capital. Including the cost ofmerchandise, the new ABC stores will fall within a bracketof $5 to $10 million and will be backed by staffs of 50 to200 employees. Fadel also expects sales revenue for the twonew outlets to vary between $4,000 and $7,000 per m2, afigure that can be put in perspective when compared to the$3,000 generated by local Lebanese stores. Considered one ofthe highest non-food ratios in Lebanon, ABC’s turnoverrepresents 13% of the $1.5 billion Beirut retail market.

Like any other company with an eye on attractive businessopportunities available in the Middle East, Fadel isconsidering ABC’s expansion into Kuwait, the UAE, Syria,Egypt or the KSA. As for going public, however, he has lessambitious plans. “It will eventually happen, sooner ratherthan later,” Fadel stated, “but there is no definite timeframe yet.”

April 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Lebanon

Parking meters Coming to Beirut

by Executive Staff April 1, 2007
written by Executive Staff

This month will see 50 parking meters installed in one areaof the Beirut Central District. The pilot scheme, operatedby Near East Automatic Distributors (NEAD) in an $8 million,2.5-year, World Bank funded project, will then see a further10-20 on Charles Malik and Bliss streets and 50 more in thearea currently occupied by opposition campers. Althoughtargeting commercial areas, NEAD will eventually targetspecific residential zones to offer resident parking permitsin a system similar to that operated in London and othermajor cities.

“The number will eventually rise to 750 throughout Beirut,”says Chafic Sinno, NEAD’s managing director, “We will belocating them in the business districts, where we hope thecustomer will have the social wherewithal to understand andaccept the concept as something that is beneficial.”

The concept is simple. One main meter will dispense ticketsaccording to the “pay and display” system, with LL500 buying30 minutes and allowing a maximum stay period of twohours—perfect, Sinno believes, for the short-term parker.Customers who overstay their welcome will receive multiplefines—or citations—and further non-payment can result in a“booting” or immobilizing if the car is later spotted atother meter locations.

Drivers who think they can simply throw away the citationand disappear will be disappointed. Records are kept and,now that the mécanique renewal process is also under theauspices of the private sector, “wanted” drivers who haveoutstanding fines will not be able to renew their car papersuntil all debts have been cleared.

Handing out fines will be the responsibility of fieldoperators, all of whom will be accompanied by police, whosepresence—especially on the notoriously territorial BlissStreet running the length of the American University ofBeirut—will be welcome.

Those who have had run-ins with the often-threatening andintimidating parking attendants on Bliss might be skepticalabout NEAD’s chances of success on this busy,student-drenched thoroughfare. Even if they do contribute totraffic congestion, most businesses rely on double parkingfor their customers and, until now at least, the policehave, by and large, turned a blind eye.

Sinno is confident that the system will work and isrealistic about how people will react to the newrestrictions. “Listen, on Bliss Street, we will be flexible.We will not penalize very short term drivers if theyactivate their flashers, keep their windows down and ensuresomeone stays in the car,” he explains, adding that the jobwill become easier when the sidewalk is widened, a move thatshould make the street’s double parking culture impossible.He also insists that no one has been bought off in his bidto enforce parking.

“On Bliss, we are going head on,” he explains, “It will notbe easy. They [the shop keepers and restaurant owners] haveno idea we are coming and they will just have to deal withit. The police have been told that they too must cooperate.No one has been paid off. The orders have come from the verytop and we are receiving encouragement from all the seniormunicipal officials. In any case,” he laughs, “my marginsare too tight.”

Sinno confirmed that he had initially recruited 40 fieldoperators and that this number will rise to 150. He isconfident that if an operative is doing his job correctly,he should issue around 70 citations a day. In the firstyear, the government estimates it will generate revenues of$5 million, part of which will be given to NEAD—which hasbeen operating vending machines in universities, hospitalsand big offices for 12 years now—as its operating fee, andpart of which will be used to pay off the World Bank loan.

April 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Private equity booming

by Rami Bazzi April 1, 2007
written by Rami Bazzi

The United Kingdom’s National Union of General andMunicipal Workers (GMB Union) has recently accused privateequity firms of evading tax payments on billions of poundsthat have been borrowed to fund their buyouts. The Union hasblamed the tax code for encouraging investors to overloadcompanies with debt in order to claim tax relief on theinterest payments.

However, evidence indicates that the private equity housesare delivering enviable results for investors and in factthe private equity industry has become a great Britishsuccess story.

The benefits are not simply the high rates of return oninvestment. There is evidence that takeovers by privateequity firms will, in the medium term, generate jobs, ratherthan destroy them. For instance, a study by NottinghamUniversity’s Center for Management Buyout Research studiedprivate equity deals over a five-year period, (1999-2004),and concluded that there was a significant increase inemployment, up by an average of 26%, after five years. Thatstriking figure suggests that private equity injectsefficiency and generates growth.

As a result, the private equity industry is booming inmany parts of the world and is highly regarded in the MiddleEast and other emerging markets including China, Sydney andthe US. According to Thomson Financial, private equity netreturns outperformed the S&P 500 19% to 9.7% for the 12months to last September and 14% to 9.7% for the past 20years. The firm predicts that new money will keep flowinginto private equity as long as the public market fails toallocate capital efficiently.

The immense benefits of private equity to the overalleconomy make it a vital cog in any market. Private equityhouses and activist fund managers of all kinds, includinghedge funds, play a much more valuable role than anygovernment or regulator in propelling the liquidity of ourcapital markets, in reducing the cost of capital, in drivingforward a country’s growth and in equipping the industry tosurvive and compete in the more challenging global marketsof today.

What we also need to remember is that private equity hasproven its potential in enabling the institutionalization offamily businesses and in the implementation of propercorporate governance, key to the sustained growth of today’senterprises.

Critics of private equity also highlight the limitedaccountability as one of the drawbacks. What they fail tounderstand is that in reality, when a private equity firmpurchases a company, ownership and control are much moreclosely aligned on the main shareholders. On the otherhand, in public companies, mechanisms of accountability haveto be developed because of the separation of ownership andcontrol.

The concentration of ownership in private equity meansthat formal accountability mechanisms become far lessimportant and the owners are actively engaged in thesupervision and management of the business.

If the importance of private equity has been wellestablished in developed markets, its role in supporting thedevelopment of emerging markets will be even moresignificant, especially in sectors such as IT and telecoms.For instance, in China, the total investment for 2005 was anincredible $1.057 billion invested over 233 enterprises in2005. As a result, hoards of foreign private equity firmshave rushed to quickly establish a physical presence in thecountry to take advantage of its huge domestic market, largepool of low cost engineering talent, technologicalinnovation and fast growing economy.

In the Middle East, the Islamic module of private equitypractices presents the optimum solution for many of thechallenges faced by private equity. The shariah law governsthe mechanics as well as the integrity of the investingoperations. For example, the shariah law prohibits investingin industries that are considered detrimental, such asalcohol, tobacco and weapons. The money invested also needsto be from permissible industries and cannot be from a fixedincome ROI whether it’s interest-based or interest-like.Another shariah investment requirement relates to acceptableleverage ratios. The ratio of the total debt of a targetcompany to its total assets must be less than 33%.

In Malaysia, such Islamic banking practices are popularamong non-Muslims and have proved to be a mainstreambusiness in many emerging markets, especially in the MiddleEast where the Islamic funds are mushrooming at anaccelerated rate. Those funds have proved to be lucrativeand trustworthy, as they can be a good alternative to theconventional funds whose integrity is in question.

Unfortunately however, the campaign against the privateequity industry is not tenuous. The growing use of“shareholder loans” in highly leveraged structures allowsprivate equity groups to disguise the equity as debts andobtain tax deductions. On the other hand, controversialquestions are being raised over jobs and working conditions,about private equity firms who made staff redundant andintimidate workers to maximize short term profits in firmsthey buy out.

The UK private equity industry continues to be the largestand most developed in Europe, and accounts for more thanhalf of the total annual European private equity investmentin 2005. Although private equity has been criticized by thelabor unions, wisdom dictates that the issue is actuallyrelated to tax policies and not necessarily to thefundamental characteristics of the private equity industry.We need to realize that exceptions cannot become the normsin free and open economic markets if economic progress isour underlying concern.

Rami Bazzi is principal fund manager at Injazat Capital

April 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Financial Indicators

Global economic data

by Executive Staff March 22, 2007
written by Executive Staff

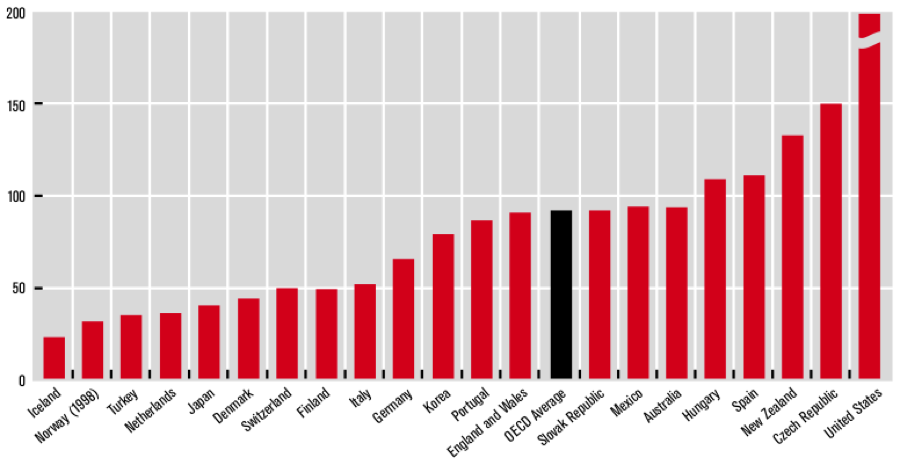
Prison population

Convicted adults admitted to prisons

Number per 100,000 population

Since the 1970s, OECD countries have experienced steady increases in prison population, with the exception of Finland where the rate has continued to decline. Over the last 10 years, Portugal has recorded one of the largest increases together with Spain among European countries. However, levels in both countries remain far below the United States, where the prison population has witnessed a huge jump that bears no historical comparison, with a population in 2000 four times as high as in the early 1970s. Differences across countries have, surprisingly, only little to do with the prevalence and development of crimes but more likely to do with political factors and responses to the increasing belief in certain countries that prison is preferable to other alternatives. When comparing prison populations in 2000, the United States again stands far above the norm with an incarceration rate five times as high as the OECD average and three times larger than the Czech Republic, ranking second. More than 1.2 million convicted American adults are in jail (a little less than 2 million when pre-trial and non-guilty offenders are included), and this may have a significant distorting role on the labor market for young males. Rising prison populations, unless fully resourced, generally reduce the effectiveness of criminal re-education. Upward trends can pull down the staff-prisoner ratio, a key component for achieving effective prevention of re-offending and promoting reintegration in the community. Moreover, prison overcrowding tends to exacerbate already high levels of tensions and violence, raising the risks of self-injury, suicide and sexually transmitted diseases including HIV/AIDS. Overcrowded prisons are also more likely to act as “universities of crime.”

Migration of the highly educated

Foreign-born persons with tertiary education

As a percentage of all residents with tertiary education

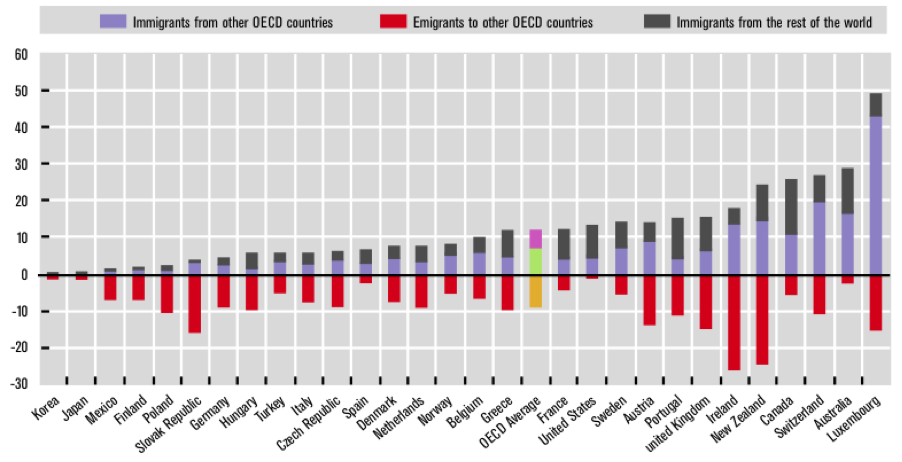
In the total OECD area, about 4% of persons with tertiary education are immigrants from other OECD countries. Those from non-OECD countries account for about 6% of all current residents with tertiary attainment. Net stocks of foreign-born persons with tertiary attainment are highest in the traditional “settlement” countries of Australia, Canada and the United States, but also in Luxembourg and Switzerland. Other countries with a large excess of foreign-born persons with tertiary attainment relative to their nationals living in other OECD countries include Sweden and France (8-9%). On the other hand, countries having a large percentage of tertiary-educated former residents living in other OECD countries include Ireland and New Zealand (at close to 25%); Austria, Switzerland, the United Kingdom, Luxembourg, Poland, Portugal and the Slovak Republic (all at more than 10%); and the Czech Republic, Germany and the Netherlands (at close to 9%).

Long-term unemployment

Persons unemployed for 12 months or more as a percentage of total unemployed, 2004*

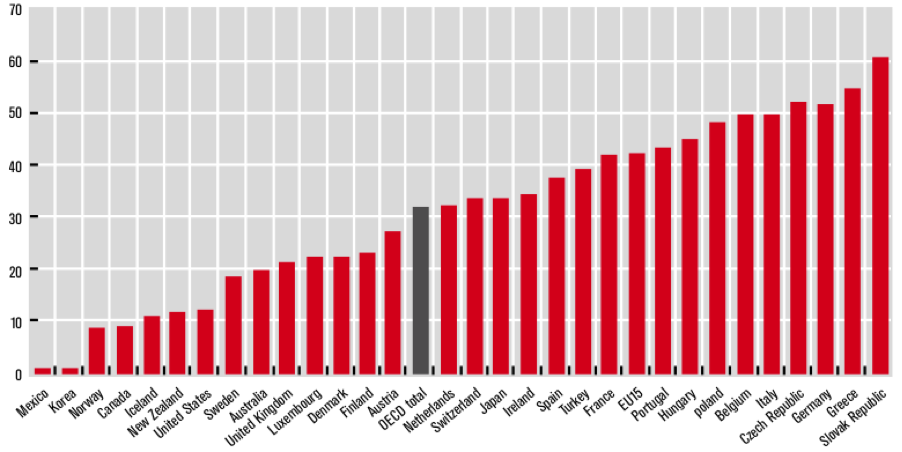
In 2004, rates of long-term unemployment varied from 10% or less in Canada, Korea, Mexico and Norway to 50% or more in the Czech Republic, Germany, Greece and the Slovak Republic. Lower rates of long-term unemployment are generally found in countries that have enjoyed relatively high rates of economic growth in recent years. There appears to be a two-way causal relationship here. On the one hand, jobs are easier to find in a fast growing economy and, on the other, economies may grow faster by making unemployment an unattractive proposition. Over the period shown in the table, long-term unemployment rates have been relatively stable for the OECD as a whole, but there have been some sharp rises in several countries and equally sharp falls in others. Rates of long-term unemployment have more than doubled in the Czech Republic, Hungary, Finland and the United States (albeit from low levels) and have also risen sharply in Iceland (although from very low levels), Japan and Switzerland. On the other hand, there have been large falls in the long-term unemployment rates in Belgium, Ireland, Italy, Luxembourg, Netherlands and Spain. It is noticeable that, since 1990, the share of long-term unemployed has halved in Korea, Norway, Luxembourg, Ireland and New Zealand.

*Latest available figures

Languages on the Web

Top 10 languages used in the Web

( Number of internet users by language )

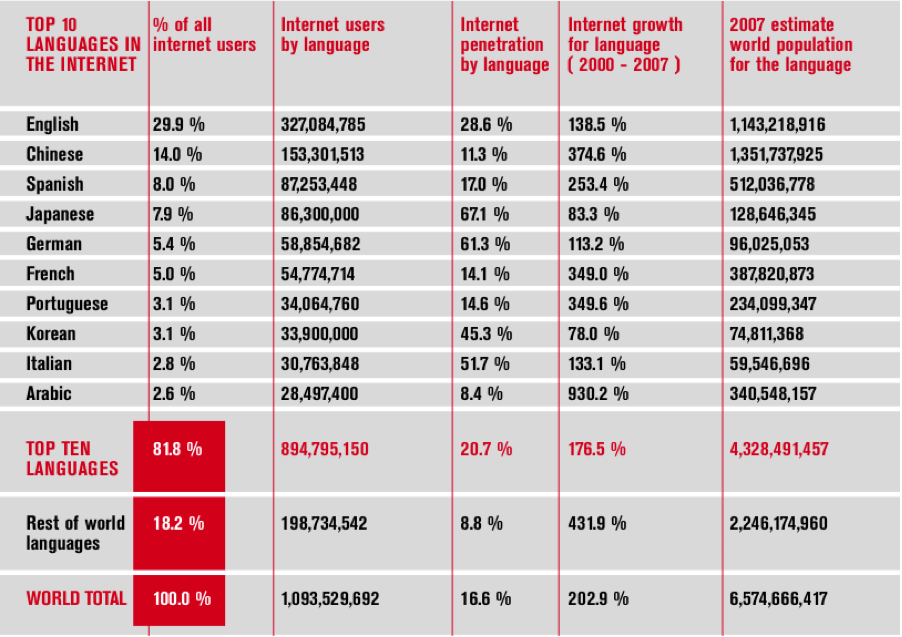
There are 87,253,448 Spanish speaking people using the internet, representing 8.0% of all the Internet users in the world. Out of the estimated 512,036,778 world population that speaks Spanish, only 17.0 % use the internet. The number of Spanish speaking internet users has grown 253.4 % in the last six years (2000-2007). Arabic speakers saw the largest growth—930.2%—although they still has the fewest speakers online (2.6%) and least penetration among speakers (8.4%).

Employment rates by gender

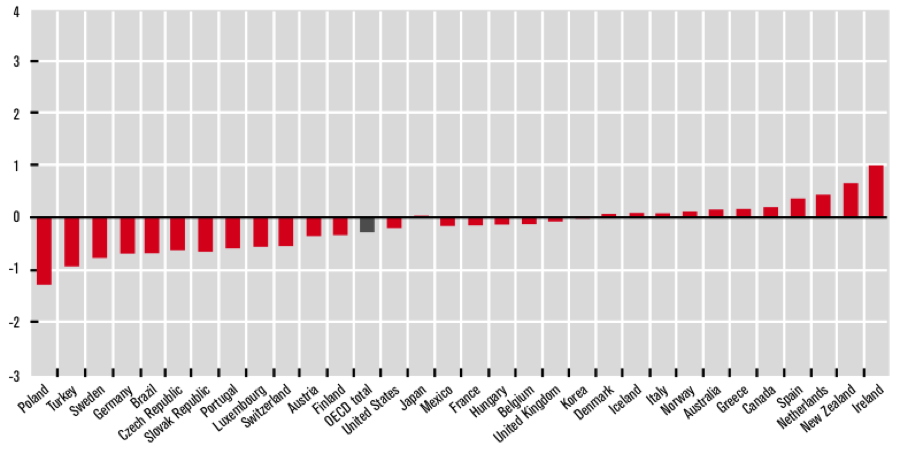
Employment rates: total

Average annual growth in percentage, 1991-2004 or latest available year

Employment rates: men

Average annual growth in percentage, 1991-2004 or latest available year

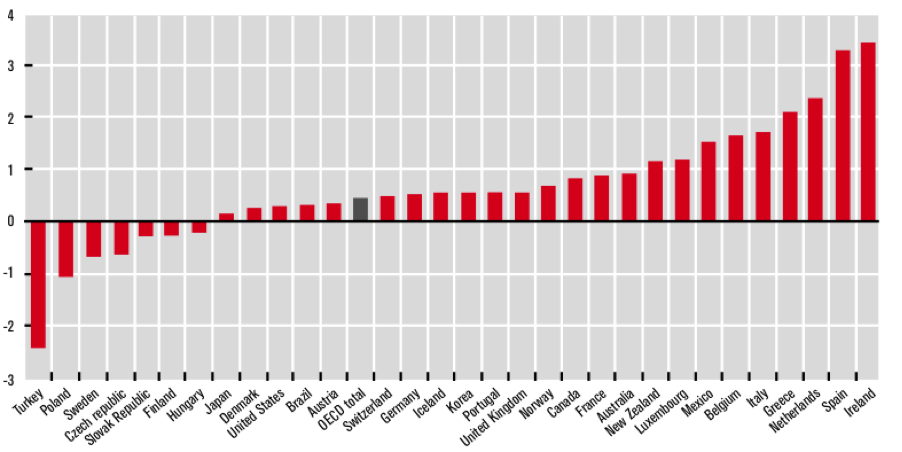
Employment rates: women

Average annual growth in percentage, 1991-2004 or latest available year

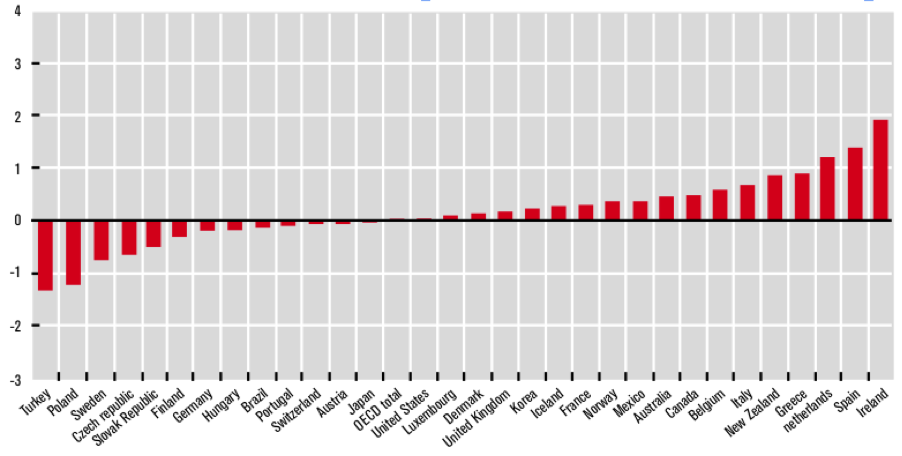
All OECD countries use the ILO Guidelines for measuring employment, but the operational definitions used in national labor force surveys vary slightly in Iceland, Mexico and Turkey. Employment levels are also likely to be affected by changes in the survey design and/or the survey conduct, but employment rates are likely to be fairly consistent over time. For the denominators—the population in each age group—the data are taken from labor force surveys. Over the period shown in the tables, total employment rates (men and women) have fallen in 13 countries and risen in 17. Particularly large falls were recorded in Turkey, Poland, Sweden, Czech Republic and Slovak Republic and particularly large increases occurred in Ireland, Spain and the Netherlands. Growth in employment rates was very different for men and women. Employment rates for men decreased in 19 countries during the period with an annual fall of more than 0.5% in Poland, Turkey, Sweden and Germany. For women, on the other hand, employment rates grew in 23 countries with increases of 1% per year or more recorded for Ireland, Spain, Netherlands, Greece, Italy, Belgium, Mexico, Luxembourg and New Zealand. Clearly, these differences in the growth of employment rates are leading to convergence in the rates for women and men although differences remain large in many countries.

March 22, 2007 0 comments
0 FacebookTwitterPinterestEmail
Financial Indicators

Regional equity markets

by Executive Staff March 22, 2007
written by Executive Staff

Beirut SE: Blom  (1 month)

Current Year High: 1,713.79  Current Year Low: 1,168.85

The BSE short seems inauspicious to inspire trading volumes these days, but the Beirut Stock Exchange undercut the Bahraini bourse in matters of confidence last month. After no more then a hiccup of an improvement to 1,208.57 points on January 26, the day after Lebanon was promised $7.6 billion in international funding, the Blom Stock Index went lower and lower to close at 1,171.47 on February 23. Solidere slumbered in the troughs while BLOM Bank did a bit better than its sector peers. Traders said they did not want to be quoted with comments on the whole market performance, because “nothing is happening, it is the same shit every day.”

Amman SE  (1 month)

Current Year High: 7,584.32  Current Year Low: 5,267.27

The Amman Stock Exchange continued a surprisingly strong show of growth to close at 6,467.63 points on February 25, representing a 17.2% improvement in the index for the year-to-date in the best two-month performance for any regional market at the start of 2007. On the month, the ASE index climbed by around 480 points since January 28. Top market power Arab Bank was strong in volume and share price development to JOD 27.50; it is now up by JOD 6.20 since the start of 2007. Select real estate stocks saw good volume, including Taameer Jordan and Arab East for Real Estate Investment. The share price of the latter advanced by 25% in the course of one month. Upstart Jordanian television station ATV said it wants to become the first station in the region to go on the bourse. 

Abu Dhabi SM  (1 month)

Current Year High: 4,648.80  Current Year Low: 2,925.03

The Abu Dhabi Securities Market had a U-shaped trajectory in February, with a hanging chad at the end. Starting at 3040.50 points on January 28, the ADSM index fell by over 90 points by February 1. It remained below the 3,000 line until it jumped to 3,035.12 points on the 20th of the month but retreated again to a close of 3,004.03 on February 25. Energy sector company Dana Gas saw strong trading volume and one of the interesting movers was oil sector company Aabar Petroleum, with a 44% rise to AED 2.21 in the latter part of the month. Some market traders thought that the rise was initiated by a case of mistaken identity, because a Kuwaiti company with similar call sign had been awarded a government contract in Kuwait. However, Aabar also had news of its own, with a new contract and production increases in Thailand.

Dubai FM  (1 month)

Current Year High: 6,731.63  Current Year Low: 3,997.29

The Dubai Financial Market moved with no clear direction in the range between 4,314 and 4,120 points. The start of the month saw the index drop by nearly 200 points but after some up and down, the market closed at 4.207.51 points on February 25. Earnings seasons added some spice to a not overly exciting month. After announcing 35% year-on-year higher net profits for 2006, market heavyweight Emaar Properties saw a spike in volume but the stock never moved far from AED 13 throughout the month. Investment bank Shuaa Capital share prices pointed downward in February, but the stock did not appear to suffer heavily from allegations by magazine Trends Arabies that the company had manipulated a Kuwaiti stock deal in 2005. Shuaa denied the allegations.

Kuwait SE  (1 month)

Current Year High: 11,542.90            Current Year Low: 9,164.30

The Kuwait Stock Exchange was one of three GCC bourses that traded lower in the fourth week of February than at the start of the year, with Bahrain and Qatar being the other two. The KSE rebounded from a month-low of 9,584.5 points on February 10 but closed not higher than 9,726.40 points on February 21. One of the market’s gainers was telecoms firm MTC, which released strong results on February 19. With most gains before the results announcement, MTC’s stock appreciated by 17% between the start of the month and February 21. Holding firm Kipco made news by saying late in the month that it is leading a consortium tasked with selling 51% of telecoms firm Wataniya. Share prices of Kipco and Wataniya are expected to benefit from the move.  

Saudi Arabia SE  (1 month)

Current Year High: 19,502.65            Current Year Low: 6,916.85

The Saudi Stock Exchange gently traversed the entire 7,000 points realm in February and reported in at 8,385.45 points on February 25. Dipping only slightly on profit taking early in the month, the Tadawul index over the period improved by 21% from 6,916.85 points on January 29. The big thing in the market for this month, and probably a few more times in the coming months, is insurance. Initial public offerings of insurers Medgulf and Malath were oversubscribed by healthy margins. Being the first two insurance IPOs in a lineup of recently licensed providers, the flotations will be followed by others and add a new dimension to the SSE.

Muscat SM  (1 month)

Current Year High: 5,956.46  Current Year Low: 4,657.16

The Muscat Securities Market closed at 5,780.39 points on February 25, up some 11 points when compared with January 28. Sailing southward in the first half of the month, the index turned back north after February 11. Flag carrier Oman Air was suspended from trading for most of February pending a capital restructuring. The sultanate’s government plans to infuse new capital into the firm, which would increase the government’s stake from 33 to 84%. Brokers on the MSM said that the shareholding of GCC investors in Omani listed companies at the end of January 2007 was substantially higher than a year earlier. GCC investors owned a total of 14% of MSM-listed stocks, up from 10% in January 2006. Shareholding by non-GCC investors remained basically unchanged at 6.5%.

Bahrain SE  (1 month)

Current Year High: 2,265.58  Current Year Low: 1,996.68

The Bahrain Stock Exchange closed February 25 at 2,160.65 points, down some 21 points compared with its close on January 28. Gulf Finance House, Nass Corporation, and Ahli United Bank were among the most active stocks in the muted market. Gulf Finance House announced a mixed cash and shares dividend of 75% after its 2006 results came with a 51% higher net profit of $212 million. The stock’s price dropped by $0.20 in the days after the announcement and closed at $2.03 on February 25. The BSE board issued a warning to one and a reprimand to another listed company for violating guidelines against insider trading and not following disclosure standards.

Doha SM: Qatar  (1 month)

Current Year High: 9,878.10  Current Year Low: 5,825.80

The Doha Securities Market had the roughest ride of all GCC markets last month, closing at 6,237.51 points on February 25, down from 6,781.08 points on January 28 and more than 12.5% down since the start of 2007. Industries Qatar climbed in the second half of the month and saw high trading volume on announcing a 50% cash dividend. Shipping company Nakilat with its capital call was also among the most active stocks; the company also announced new construction orders for six LNG vessels. In the second half of the month, government and central bank officials tried talking confidence into the market by highlighting the strong growth of the Qatari economy in 2006 and the good performance of the banking sector.

Tunis SE  (1 month)

Current Year High: 2,712.33  Current Year Low: 1,732.72

Like its colleague in Casablanca, the Tunindex conquered a new historic pinnacle in February, reaching 2,712.33 points on February 9. It slipped back by a bit over 100 points in the following week but then returned to growth, closing at 2,646.75 on February 23. The bourse is 13.54% up since the start of 2007; its market capitalization is closing in on the $5 billion mark but on our record date of February 23 it is not quite there yet, reporting $4.907 billion. The new market cap leader is drinks maker SFBT after a steep rise in its share price between the start of 2007 and mid February. Its market cap was $575 million on February 23, compared with $569.5 million for Banque de Tunisie whose stock in February retreated from historic highs in the TND 104 range and closed at TND 99.20 on February 23. 

Casablanca SE All Shares  (1 month)

Current Year High: 11,207.82            Current Year Low: 6,563.27

The Casablanca All Shares Index went up by 1,000 points in the first part of February, to scale a new record of 11,201.82 points on February 19. From that peak, however, it retreated back to 10,518.13 points at its close on February 23. It is too early to say if the market is turning. It is still up by more than 10% since the start of the year, but one reminisces about the experience of the Saudi market exactly 12 months ago. On February 23, the Casablanca Exchange saw 23 stocks go up and 29 stocks go down, with 4 unchanged.

Cairo SE: Hermes  (1 month)

Current Year High: 64,978.48            Current Year Low: 41,965.37

In the measurement of the Hermes Index, the Cairo and Alexandria Exchanges moved up nicely from 57,013.49 points on January 29 to 64,655.63 on February 25. Viewed together with the uptrend of the Saudi Stock Exchange, the 13% rise of CASE made February a gainful month for the region’s leading bourses by market size and by number of listed companies. Orascom Telecom Holding (OTH) and its chairman Naguib Sawiris were the Egyptian market’s international newsmakers last month, as OTH bid for Saudi Arabia’s third mobile license and as Sawiris-owned Weather Investments bought Greek operator TIM Hellas. The OTH share price chased new records in February and closed 19% higher at EGP 440 on February 25 when compared with its quotation on January 28.

March 22, 2007 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Money Matters by BLOMINVEST Bank

by Executive Staff March 22, 2007
written by Executive Staff

Regional stock market indices

Regional currency rates

Doha Bank opens representative office in japan

Doha Bank, established in Qatar in 1979, opened a representative office in Tokyo, Japan as part of the bank’s implementation of its globalization plan. Doha Bank, with 32 branches in Qatar as well as branches and representative offices in Dubai, New York, Japan, Turkey and Singapore posted net profits of QAR744m ($204m) in 2006 up down 5.81% year-on-year. The bank’s total assets rose 42.45% for the same period to reach QAR22 billion ($6 billion) in 2006.

UAE’s Etisalat 2006 net profits reached $1.6 billion

Etisalat, the sixth largest telecommunication corporation in the Middle East, declared a rise of 37.7% in 2006 net profits to reach AED5.9 billion ($1.6 billion) and a 91% rise in its 2006 total assets to reach AED45.9 billion ($12.5 billion). This rise in assets is mainly attributed to the company’s international expansion, through the acquisition of a 51% stake in Pakistan Telecommunication Company Ltd, in addition to negotiations with the Afghan government for the country’s third mobile license and the purchase of Egypt’s third mobile network license. The UAE government currently owns 60% of Etisalat while the public owns the remaining 40%.

Country profile: Saudi Arabia

Global Investment House (GIH) issued a report estimating Saudi Arabia’s nominal GDP growth at 12.4% in 2006 to SR1.30 trillion ($346.9 billion). In turn, real GDP grew 4.2% to SR799.9 billion ($213.3 billion) The Compounded Annual Growth Rate (CAGR) of Saudi Arabia’s nominal GDP growth for the period 2002-2006 was at 16.5%. According to GIH’s report, the Saudi Arabian private sector grew by 7.9% in nominal terms in 2006, while the oil sector registered a nominal growth of 16% for the same period. According to the Ministry of Finance 2007 budget report, the Kingdom’s public debt is estimated to drop by 23% to SR366 ($97.6m) in 2006, some 28% of GDP. The expansion in Saudi Arabia’s economy was not affected by the correction in the stock market as all indicators show an “exceptionally sound and robust” 2006 performance.  Standard & Poor’s Rating Services recently upgraded Saudi Arabia’s long term foreign currency credit rating to “A+” from “A” and affirmed the county’s long term local currency rating at A+ and short term sovereign credit rating at A-1, all with a stable outlook. Saudi Arabia is the largest oil producer among the Gulf Cooperation Council countries, producing around 10% of the world’s oil.

March 22, 2007 0 comments
0 FacebookTwitterPinterestEmail
Regional BankingSpecial Report

UAE banking executives On forecast for 2007

by Executive Staff March 22, 2007
written by Executive Staff

Executive talked to Hani Hamid, Marketing Manager at the National Bank of Umm Al Qaiwain, and Yousef Padganeh, Head of the Basel II Project at Bank Saderat Iran in Dubai, about the outlook for the UAE banking sector this year.

E  Is the UAE banking market as competitive as it could be? Specifically, do you expect greater competition this year on prices for core banking products? 

NBUQ: Definitely. Prices on interest will vary from bank to bank, so the sector will become more competitive. The sector will become more competitive this year—there are now 52 banks in the UAE.

Bank Saderat: Yes, there is growing competition. The UAE market is highly competitive and will become more competitive because the people are trying to find new markets.

E  Is the regulatory environment and enforcement of regulations fair and equitable for all banks in the UAE?  

 NBUQ: Yes, I think it is—but the UAE needs a credit bureau, which has been talked about for a long time.

 Bank Saderat: Yes, it is fair.

E  Will the UAE be able to defend its role as leading banking hub in the Gulf against the competition from Bahrain Financial Harbor and Qatar Financial Center? Does the function as banking hub benefit local banks or are there disadvantages?   

NBUQ: I think the UAE is one of the strongest banking hubs, so then it will be able to compete. It is competing with the Middle East, not just the Gulf. Local banks compete differently from international banks—a different environment and customers—so they have the edge on international banks for local and Arabic-speaking customers.

Bank Saderat: Yes, if you compare it to a few years ago you will see more and more companies and organizations are coming to the UAE, to the DISE. If we look at the whole Gulf region, the market share will decrease as more banking come to Dubai. Local banks will benefit as we [international banks] are limited—we cannot have more than eight branches, but foreign banks will try to have more branches. Local branches will open more and be more active, so they will benefit.

E  Should regulators modify their approach to the licensing of local and/or foreign banks in the UAE?

NBUQ: It could be possible, as I think there are too many banks in the UAE, even foreign banks. UAE has an open market so anybody can come.

Bank Saderat: I am not aware of this. Regulators are supporting local banks more than international banks.

E  Is the sector ripe for mergers? Should regulatory authorities do more to encourage consolidation? 

NBUQ: I think it is the right time for some merging. With all the money banks made last year, and in 2005 due to the stock market, there was talk before then for mergers, but if the market stays the way it is, or there is a drop in the market, mergers could happen.

Bank Saderat: One thing I am seeing is that Emirates groups will merge. For example, we are seeing new banks, but state banks will not like mergers.

E  Are UAE banks valued adequately in the Abu Dhabi and Dubai stock markets? Are 2006 earnings growth and performance reflected in recent share price developments?

 NBUQ: In terms of profit it has affected them, but in terms of value at the right level. Looking at the market it is good and healthy. I think the stock exchange will grow this year.

Bank Saderat: The price of the banking stock depends on construction. I think it depends on that area rather than banking. For instance, if Emaar goes up, the National Bank of Dubai will go up.

E  UAE banks have been looking east and west for cross-border expansion opportunities. Which markets are the most attractive for expansion in 2007?  

 NBUQ: I would say Iraq, but that’s not a good market right now. Africa is showing it is a competing market; Sudan and Libya have shown they are good markets. Egypt is also a good market, and there are some international banks are there. Qatar definitely a good market and competitive—a lot of banks are trying to open there, and in Bahrain. Syria is good, but tere are too many rules and regulations.

Bank Saderat: UAE banks are opening branches in Pakistan and India, and want immediate customers living in Dubai. Some 55% of workers in the UAE are from Pakistan, India and Bangladesh, so there is demand, particularly for retail banking. The other factor is based on trading, where they have the most trade. Some of these investors are looking for property investment so that is why they are opening in Morocco and North Africa. Banks are also trying to get into Iran and Iraq.

E  What obstacles do banks find most challenging when pursuing cross-border expansion, and are some of these obstacles higher for UAE banks than for international competitors in the same markets (e.g. regulatory requirements in other markets, competition with European banks in countries like Egypt, acquisition of skilled staff, integration of corporate cultures in takeovers)?  

NBUQ: In Egypt, rules are the obstacle, along with money transfers and exchanges. Sudan and Libya are much more open, but politically Sudan is not stable. Libya is an open market.

Bank Saderat: The first problem is regulatory. We should know what the rules are—and then new competition in the market. I also think they should have a good idea of customer needs and wants as they will differ from the UAE. For instance, just now regulations for foreign banks requires UAE-employees, so recruiting can be a problem.

E  Do staff shortages create problems for domestic growth of the bank?  

NBUQ: It definitely affects a bank’s growth. All banks have been affected by stock markets, and I don’t think there is a problem, but staff exchanges between banks are a problem, which affects banks moving ahead.

Bank Saderat: Getting staff in the UAE is a problem as there aren’t enough people. We may find a few post-grads, but they have no experience. In the long term it should be better.

E  Is the growth of Islamic banking the future of UAE banking?

NBUQ:  I think it is the future of everywhere, even the UK and now the US. It is a trend they follow, like changing clothes. They have used credit cards, car loans, and now trying Islamic banking. We have already started that here.

Bank Saderat: Islamic bank is rising. HSBC started and others too, so there is a market.

E  Do you expect shifts in the structure and importance of corporate banking? Where are the best options to expand and/or diversify financing portfolios for manufacturing ventures and corporate borrowers?   

NBUQ: Banks are doing corporate banking but retail banking is a lot more profitable, but I think they should change their policies, as the commercial banking is moving fast and changing, and it is a good banking product.

Bank Saderat: Diversified portfolios will minimize risk, so there will be a shift. We have corporate banking and the target market is changing. Nowadays competition is high so we need to find new markets.

E  What are the main challenges in retail operations? Given the rapid changes in costs of living and the scenarios in the housing market, what can banks do to keep their consumer loan portfolios profitable and lending growth sustainable? 

NBUQ: In retailing, the most popular products are mortgages, and banks are looking into priority banking due to customers having more wealth. We have 40-50,000 millionaires in the UAE, out of a population of 4 million, so priority banking will make some growth for banks and they are looking at this. Mortgaging is also booming.

Bank Saderat: The main challenge here is that the cost of living is rising. If banks can provide home loans they will benefit, and then what will happen is that people will try and invest in houses. Second, credit card users are rising, so savings will decrease. Loans will increase and repayment times. High rates of loans will also increase. Banks are now offering Dh120,000 loans.

E  Could the consumer lending and housing loan segments face problems from rising loan default levels in 2007? What mechanisms will banks use to avert the overheating of the retail lending market?

NBUQ: There have not been many defaults in the market—I have not heard of that many, more in cars than houses. It is a new loan through banks, so not many defaults, and people just sell out the deed. Definitely prices have hiked, and I think the surplus will drop. In three years, you might see more defaults.

Bank Saderat: Default will increase, particularly for homes. We should look at the political situation of the region, and consider that there has been an abnormal increase in property prices. There are also delays in construction times, and people still have to pay off loans. Salaries are also not increasing in relation to rising costs, with housing rising 100%. The onus should be on the government, as banks want profit. If the government increases salaries, that may help.

March 22, 2007 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 591
  • 592
  • 593
  • 594
  • 595
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE