• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Analysis

Diverging realities for Lebanon’s food producers

by Andreas Groes September 15, 2026
written by Andreas Groes

Lebanon’s food producers have spent the past seven years navigating a financial crisis, currency collapse, soaring prices and repeated conflict. The upheaval has fundamentally changed the economics of producing food locally. While higher import costs have created opportunities for some producers to replace imported goods, rising production costs, weakened purchasing power and conflict have made it increasingly difficult for others to maintain production and sales.

Those different realities are reflected in the experiences of three Lebanese producers operating in different parts of the food sector. Agrifresh, led by partner and CEO Roy Noujaim, produces fresh-cut vegetables in the Bekaa Valley, supplying primarily restaurants. Balkis, where Ali Beydoun is operations manager, produces juice at its facility in Insarieh, using fruit from orchards in southern Lebanon and targeting the higher end of the consumer market. Biomass, headed by CEO Mario Massoud, works with a network of farmers across Lebanon, bringing locally grown fresh produce to market. 

Their experiences have been shaped by the pile-up of crises that began with the economic collapse of late 2019 and escalated with the COVID-19 pandemic and the Beirut blast of August 2020. Any relief from these polycrises was only tamped down by periods of lower level conflict beginning in October 2023, and subsequent phases of all-out war on Lebanon and the systematic destruction of the south which has damaged an estimated 22.5 percent of Lebanon’s agricultural land, according to Lebanon’s Ministry of Agriculture on 17 April 2026.

The currency collapse was accompanied by high inflation. Annual inflation reached 221 percent in 2023, before slowing to 45 percent in 2024 and 15 percent in 2025, according to Lebanon’s Central Administration of Statistics (CAS). Food inflation followed a similar trajectory, falling from 208 percent in 2023 to 22 percent in 2024 and 15 percent in 2025. While food prices rose almost as fast as overall prices in 2023, food inflation slowed considerably faster than the overall inflation in 2024, before the two rates converged in 2025.

Against this backdrop, agriculture has increased its share of the Lebanese economy. According to the Centre de Recherches et d’Études Agricoles Libanais (CREAL), agriculture accounted for 9.4 percent of GDP in 2025, compared with 5.8 percent in 2020. The increase does not necessarily mean that agricultural production has grown by the same proportion, as agriculture’s share of GDP is also affected by changes in the size and composition of the wider economy.

Adapting to a new economic reality

For Agrifresh, one of the first consequences of the financial crisis was losing access to financing for growth.

“When we started growing our company, we were relying on loans from banks like any other company that would grow. You can’t only rely on your own revenue stream or your profit. So when the economic crisis hit in 2019, that was one of the biggest challenges we were facing back then. Our growth was only based on our own revenue generation,” Noujaim explains.

The crisis also increased the cost of keeping the business running. Agrifresh relies heavily on electricity to keep its fresh vegetables refrigerated, while fuel is needed for distribution and irrigation.

“Our business relies a lot on energy because we have fridges all over the place. Our products have to be cooled at very low temperatures 24/7, so you can’t lose electricity,” Noujaim tells Executive.

Integrated Petroleum, a oil and gas trading organization headquartered in Doha, recorded a rising price of diesel by 85 percent in Lebanon between September 1, 2025 and September 1, 2026, adding further pressure on producers reliant on fuel for transport, irrigation and generators.

As electricity and fuel supplies became increasingly unreliable, Agrifresh invested in its own energy infrastructure in 2021, gradually expanding its solar system as the company’s energy needs have grown. The company also built a fuel station in 2022 at its factory to ensure that its distribution fleet would not be affected by shortages.

“Now we operate 100 percent on solar energy. We no longer rely on the energy provided by the government because we know it’s not reliable and it might go out at any second,” Noujaim says.

The wars have presented a different challenge. While Agrifresh’s production facilities have not been directly affected by the fighting, the company has felt the impact through its customers. Restaurants in the south were largely out of operation during periods of intense fighting, while some restaurants in the north saw a small increase in demand, among other reasons because displaced people moved north.

The impact extended beyond the areas directly affected by the fighting. “Most of our customers are restaurants. People would tend to go out less during war times,” he notes.

Another challenge for Agrifresh has been the rising cost of imported inputs. 

“We rely a lot on imported materials, like packaging material. All of these are imported, they’re not produced in Lebanon. So they were impacted by inflation. Our products have, over the last six years, become a lot more expensive,” Noujaim tells Executive.

But higher import costs have also created opportunities for Agrifresh to replace some imported products with locally grown alternatives.

“There are five different kinds of vegetables that we didn’t grow in Lebanon because they had been imported and were not very expensive. Nowadays, because of inflation and high import costs, there was an opportunity for us to start growing those vegetables in Lebanon, and this is what we have done,” Noujaim explains.

The locally grown alternatives include baby spinach, sucrine lettuce and beetroot leaves. While these products continue to be imported, Agrifresh says it can compete with them on both price and quality.

“We are 15 to 20 percent cheaper,” Noujaim says.

Forced to shut down production

While Agrifresh has been able to adapt to the changing market, the war has presented Balkis with a more fundamental challenge of keeping its production running.

“We closed fully because our facilities are based in the south. Our areas were being targeted or being under threat, and it was not safe for us to operate in those areas,” Beydoun tells Executive.

The interruptions were not limited to a single period. In 2026, Balkis was unable to operate for almost two and a half months.

“Sometimes there was no threat and we were able to manufacture, and then there was a threat, so we had to shut down and go home. During those periods, we had to continue with the usual business expenses and all, but we were unable to supply the market, we were unable to sell,” Beydoun recalls.

The company also experienced a prolonged closure in 2024, when it was unable to operate for around three months. The closures came on top of the financial pressures created by Lebanon’s economic crisis. The banking crisis made it difficult for Balkis to access its funds and carry out international payments. Rising fuel and electricity costs have added further pressure to the company’s production costs.

The economic downturn has also hit Balkis on the demand side. As the company sells a high-end product, the decline in purchasing power has reduced the size of its potential market.

“We don’t make the same now as we did six years ago. In our case, our product is a luxury item. Due to the circumstances and wars, the consumer market has been materially impacted,” Beydoun says.

Avocados left at home  

For Biomass, the consequences have been felt both in the fields and in its ability to reach foreign markets. The war has particularly affected their operations in southern Lebanon where farmers were forced to leave. 

“It was way too dangerous to stay in the south. We lost crops and we lost farmers,” says Mario Massoud, CEO of Biomass.

The loss of production has also affected the company’s exports. “We export avocados to European countries. Most of our avocados are located in the south. During the wars we couldn’t export,” Massoud says.

The war has also changed Biomass’s geographical production footprint, with the company now producing less in southern Lebanon.

“The farmers in the south are more limited than they were in the past, so we have fewer farmers there now,” Massoud adds.

The rising cost of production has added another pressure on farmers. “Most of the irrigation is done on fuel, and you have farmers not irrigating as well, losing crops because they can’t afford the fuel,” he notes.

Despite the higher cost of producing locally, Biomass sees an advantage over imported fruits and vegetables.

“It has become more expensive to produce, but it is cheaper compared to imported goods. Producing locally is still more competitive than importing from Europe or from neighboring countries,” Massoud argues.

A weaker pound is no major gain for producers

Nassib Ghobril, Chief Economist at Byblos Bank Group, says the crisis has affected businesses through both declining purchasing power and rising costs.

“The financial crisis led to the decrease in the purchasing power of households, which affected consumption and consumer demand, which in turn affected sales at companies,” says Ghobril. “It increased the cost of imports and their operating costs and created a period of uncertainty and lack of visibility. There have been many theories that this will encourage local production and it will reduce imports. But we have not seen this.”

“The economy still relies on imports,” he adds. “We have seen an increase in local production but not to the point of replacing imports. Last year, the import bill was about $21 billion, which is the highest level on record. Exports were around $3.5 billion, so we still have a wide trade deficit.”

The figures refer to Lebanon’s overall trade in goods. Yet the depreciation of the pound has not translated into significantly lower production costs in Lebanon.

“It did not get cheaper because you still have high energy costs, you still have very high operating costs, administrative costs, the cost of formalities with the public administration, poor infrastructure. And anyway, there are products that are raw materials that industry still needs to import that are not produced locally,” Ghobril argues.

The continued reliance on imports comes despite some improvement in Lebanon’s overall economic conditions compared with the beginning of the crisis.

“Today conditions are relatively better than they were in 2020. You have a stable exchange rate, you have a larger economy, you have lower inflation, you have a functioning government and parliament,” Ghobril notes.

Infrastructure is the key to future growth 

But adapting to the changing market is only part of the challenge. Roy Noujaim from Agrifresh says greater government support could help farmers adopt new technologies and production methods.

“Something that we would like to see more changes is probably more governmental support incentivise and support the adoption of new technologies,” Noujaim says. “It can be on the financial side and it can be on the consulting side as well.”

Beydoun and Massoud similarly point to the need for greater government support for the sector, including better access to finance and support for farmers.

Despite the challenges, Massoud believes Lebanon already has many of the natural conditions needed for its agricultural sector to prosper.

“We have a climate, soil, sun, water, and microclimates that few countries in the region have. Unfortunately, we don’t have the proper infrastructure in place for the farming and agriculture sector to prosper properly. If we get the right infrastructure, we have everything that the Lebanese terrain can offer. I think food production and agriculture here has a bright future,” says Massoud.
September 15, 2026 0 comments
0 FacebookTwitterPinterestEmail
Comment

Deja Stink

by Executive Editors September 14, 2026
written by Executive Editors

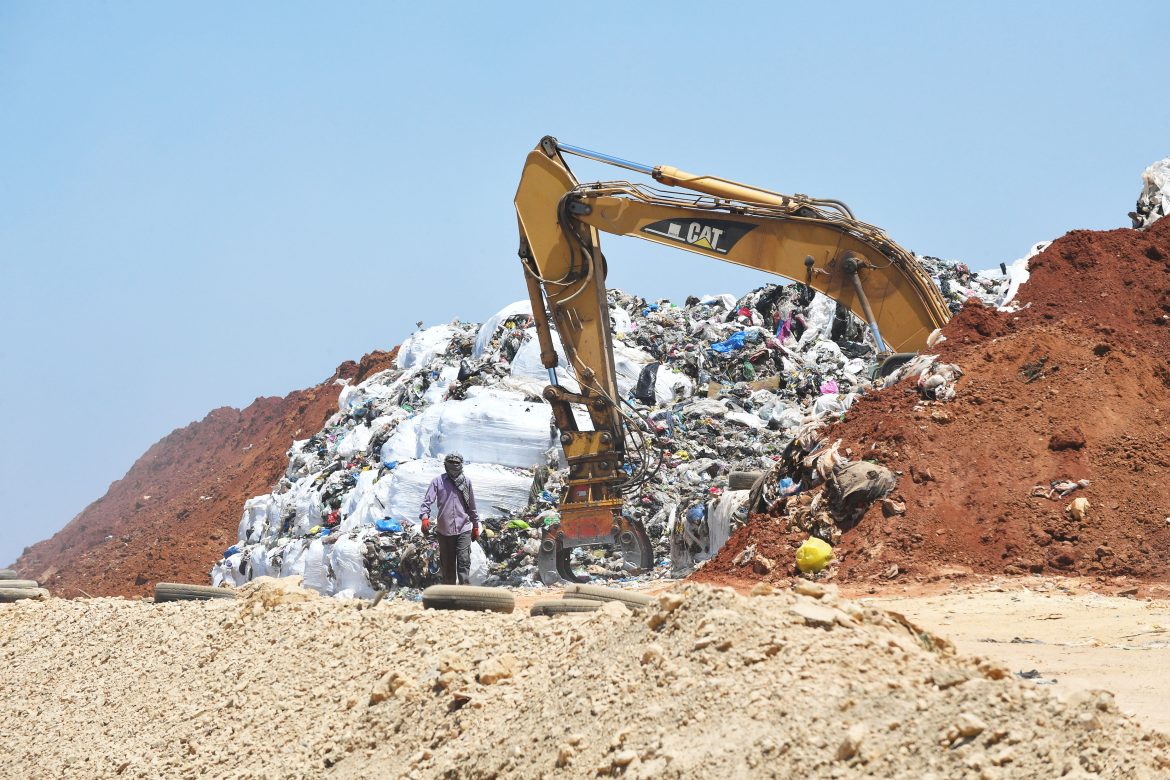
Talking trash, sorry: discussing political solutions for solid waste management, is a parliamentary tradition in the Lebanese Republic. Ten years ago this past summer, the long overdue closure of the overfull Naameh landfill south of Beirut sent Sukleen’s trucks home empty, and within weeks the capital’s streets were lined with rotting garbage. The “You Stink” movement that followed pulled tens of thousands of people onto the streets — at its peak, an estimated 250,000 on a single day in August 2015 — and turned trash into perhaps the most visceral symbol of state failure Lebanon had produced since the civil war.

A decade on, Lebanon is still mired in largely unrecycled trash and also in unresolved waste management debates at both the public square of opinionating and the parliament halls. In the latter, the bone of political contention is the text of a January 2026 law amendment – known as Law 38 of 2026 – and the role of a newly appointed government entity, The National Solid Waste Management Authority (SWMA) headed by Marwan Rizkallah.  

Questions pertaining to the waste management debates include who gets to run Lebanon’s waste sector as well as the less overt matter of who profits both financially and politically from keeping it broken. As is true of many dysfunctional sectors in Lebanon, the solutions to the entrenched solid waste problem require as much political will as they do resources, capacity building, and awareness of what best practices might look like for Lebanon.

After zooming in on the trash problem over the past few weeks, Executive editors have concluded that, broadly speaking, the solution seems to hinge on decentralization, depoliticization, transparency and regulation, and a fundamental shift in the Lebanese mindset that moves from viewing garbage as waste and liability to garbage as an economic resource.

Lost in centralization

For most of the post-civil-war period, Lebanon ran waste collection as a tightly centralized affair, split across three separate functions that, from an outsider’s perspective, seemed to lack coordination or communication amongst eachother. The Ministry of Environment set policy and strategy, the Council for Development and Reconstruction (CDR) contracted out collection to a handful of private operators (Sukleen until 2018, then RAMCO and City Blu) and the whole system was bankrolled through the Independent Municipal Fund (IMF) under the Ministry of Finance (MoF).

The MoF-IMF collected funds for solid waste collection, processing, and disposal on behalf of municipalities and redistributed the money without their input, per the government’s own National Integrated Solid Waste Management Strategy documentation as per an Executive Summary of a study conducted in coordination with the World Bank in February 2024. Municipalities themselves, of which Lebanon has 1,065, one of the highest per-capita counts of any country its size, according to Ministry of Interior and Municipalities figures from last year, had essentially no legal say in who collected their waste, what it cost, or where the money went.

Lebanon generates somewhere around 6,500 tons of municipal solid waste a day nationally, per UNDP estimates, though the economic collapse pushed daily volumes down by roughly a quarter between 2018 and 2022, from about 7,300 tons a day to around 5,600, according to a 2024 CDR report. Of that, only a small fraction is recovered. Estimates range from about 8 percent recycled nationally to 15-20 percent once composting and material recovery are folded in. Most of the rest is landfilled or, worse, dumped illegally in Lebanon’s valleys or burned. A 2023 World Bank technical note found that most municipalities were spending more than 75 percent of their entire budgets on waste collection and disposal, pushing some into deficits and dwarfing capacity to provide other services.

Meanwhile, the country’s existing waste infrastructure has consistently underperformed its design capacity. The Karantina sorting facility in Beirut, for instance, was built with a rated capacity of 1,800 tons a day, which is nearly a third of the country’s entire daily waste output concentrated in a single site, and yet it sat effectively non-functional for years after the 2020 port explosion, and is only now approaching a partial reopening, at a reduced 1,250 tons a day, following a Germany- and EU-funded rehabilitation that UNDP expected to wrap up around October 2025. A single facility carrying that much of the national load is a fragility problem subject to Lebanon’s political and financial winds.

This is one core argument for decentralization, and it found legislative traction on January 5, 2026, when Parliament passed Law No. 38, amending Article 28 of the original 2018 waste law to let municipalities collect service fees directly from households and businesses and contract collection companies on their own terms. Municipalities can now also outsource fee collection itself, not just physical collection, meaning even under-resourced councils have a practical path to implementation without building expertise from scratch.

Skeptics note that many of Lebanon’s municipalities are barely functioning institutions at all. As per information from election monitors at the most recent municipal polls, at least 134 of the country’s 1,065 were formally dissolved ahead of its first municipal elections in nearly a decade, finally held in May 2025, and many more were described as de-facto inactive due to political disputes or lack of funds. In order for the new waste law’s municipal responsibilities to work, skeptics, including this magazine, contend that the central government would urgently need to provide support in the form of capacity building to convert refuse to resource, regulation to prevent increased use of illegal dumps and promote transparency as a starting point.

Depoliticization: a sector built for capture

If decentralization addresses who runs the system, depoliticization appears as the key for addressing the thorny question of why it keeps failing regardless of who’s nominally in charge. The story of the Naameh landfill, opened in 1997 as a “temporary” solution meant to hold roughly 2 million tons, and closed in 2015 after having taken in some 15 million tons, is an illustrative example.  Political actors spent nearly two decades unable to agree on an alternative site in large part because every landfill decision in Lebanon carries sectarian and territorial weight.

The financing structure has compounded that problem. Routing sector funding through the Independent Municipal Fund and the general treasury rather than through fees tied transparently to actual service cost meant the money moving through the sector was difficult to trace to a specific outcome and remained opaque to the municipalities. That kind of centrally gate-kept resource is easily politicized, which is a large part of why reform efforts stalled for years even after Law 80 was first passed in 2018 establishing the legal framework for integrated solid waste management.

Depoliticizing the sector is a means of means confining the central government to the roles it can, hopefully, legitimately play, such as setting and regulating binding technical standards, monitoring compliance, enforcing penalties, and then moving implementation and financing to the municipal level, where the incentive to deliver a functioning service is strongest, because voters and business owners can see the results directly and locally.

Separating the roles

The sector’s institutional structure has, at least nominally, kept the functions of the Ministry of Environment, the CDR, and the IMF under the MoF separated. In practice, none of the three answered meaningfully to municipalities or to the public, and Lebanon’s National Integrated Solid Waste Management Strategy itself acknowledges that the sector has lacked a dedicated regulatory body, which is one reason the strategy calls for establishing a National Solid Waste Management Authority (SWMA) as a central oversight function.

That authority’s board and director were appointed alongside the government’s approval of its updated national strategy at the turn of 2025 into 2026, and government documentation describes the SWMA’s intended role in explicitly regulatory terms. What isn’t yet publicly documented is how the authority’s financing, contracting and regulatory functions will actually be divided and implemented in practice, or what its operating budget will be. Whether the SWMA’s mandate will match that stated design when and if it becomes fully operational remains to be seen.

Migrating trash from refuse to resource

The capstone of any sustainable solid waste management solution, and arguably the piece of trash reasoning with the most potential to change public sentiment, is the one that seems to be the least discussed. Recent debates have focused mainly on how to fund the treatment of recoverable waste; specifically, who should pay, and how much. This particular debate – which Executive editors perceive as convoluted, politicized, and overall not productive – misses the point that Lebanon’s waste is an untapped resource.

A September 2022 Q&A conducted by entreneurial ecosystem Berytech with longtime waste-management expert Samar Khalil put the country’s potential recycling-sector turnover at somewhere between $65 million and $272 million a year while estimating that Lebanon currently loses roughly $64 million a year in unrecovered e-waste material alone, plus further losses in unrecovered paper and organic-waste value, largely because so little of the waste stream is sorted at the source. The same analysis put the job-creation potential of a properly functioning recycling sector at somewhere between 1,900 and 2,500 new positions over roughly nine years.

One timely example where utilizing this potential is a matter of urgency—though one still complicated by Israel’s ongoing bombardment—is in the area of rubble. Lebanon generates roughly 1.65 million tons of construction and demolition waste a year, with 40-45 percent of it concentrated in Beirut and Mount Lebanon alone while only ten percent is recycled, according to a policy brief published by the American University of Beirut (AUB)’s Nature Conservation Center in August 2025. The brief models a phased national recycling program reaching an 80 percent recovery rate by 2036, and projects that a properly regulated rubble-recycling industry that turns debris back into aggregate, reclaimed asphalt and recovered metals could amount to a $20-25 million annual market. Most importantly, it directly reduces the need to quarry raw material from Lebanon’s mountains.

A second example is Lebanon’s iron and steel exports, which alone were worth $120.3 million in 2024, according to UN Comtrade trade data, out of total national exports of $4.29 billion that year. That revenue stream built substantially on scrap and recovered material could plausibly grow with better domestic sorting and collection, though comtrade classifications don’t allow a precise breakdown of how much of that $120.3 million specifically originated as recovered scrap versus other iron and steel products.

The last decade has seen many valiant attempts to instill a comprehensive local culture of recycling, with varying rates of success. Ventures like Recycle Lebanon, founded in 2015, and its EcoSouk retail arm, which describes itself as the first zero-waste shop in the Middle East, have spent a decade attempting to make circular, locally sourced alternatives to imported, disposable goods work commercially in the Lebanese environment. What these types of ventures need is greater market access in the form of  public procurement rules that prioritize recycled or reused domestic material and predictable supply. Municipalities could provide that supply in a decentralized sorting and management scenario.

Trash talk need not be far from trash action

None of these proposed solutions necessarily require reinvention of the entire waste management sector. Lebanon already has more waste-treatment infrastructure than it currently uses, and as of January 2026, it has a legal pathway for municipalities to finance and contract collection directly. It has its own national strategy calling for a decentralized, transparently regulated, cost-recovery-based model. What’s urgently needed from this moment onwards is for the sector, and the National Solid Waste Management Authority in particular, to operate effectively and accountably as regulator, monitor, and enforcer.

Over ten years after the 2015 garbage crisis, the sector is still, for the most part, financing waste management centrally and treating it as a liability, but based on Law 38, it could slowly be moving towards looking at waste management as a local public service that can sell its byproduct back into the economy. Whether it does will depend on whether the SWMA publishes a transparent budget, cost breakdown and contracting rules and whether citizens and anyone outside government will wield their power to keep corruption and our reusable resources far apart.

September 14, 2026 0 comments
0 FacebookTwitterPinterestEmail
Analysis

Joining a race without owning a course

by Jamile youssef September 3, 2026
written by Jamile youssef

It is the no-brainer of the century. No one tracking the headlines and global debates can today deny that Artificial intelligence is a technical revolution progressing at never-before-seen speed, an unprecedented global investment focus, and a hyper-divisive social phenomenon.  As such, the emergence of AI is indubitably reshaping the global economy – not to mention disrupting human life as it has been known over millennia. In the specific case of this country, its denizens are faced with rethinking everything that has been governing lives and livelihoods in one of the longest-standing continuous human habitats. After six millennia of urban settlements, tomorrow’s Lebanon that emerges today, may never look the same.

Only three years ago, in 2023, a report by consultants McKinsey & Company on ‘The economic potential of generative AI’ speculated that generative AI combined with other automation technologies, could contribute 0.5 to 3.4 percentage points to annual labor productivity growth. Since 2023, much more visible and tangible indications have been the rollout of AI infrastructures and the astronomical capital expenditure, or capex, in AI projects around the world. Highly touted current estimates of AI-related capex from Jan 2024 to mid 2026 range slightly north of one trillion dollars, or possibly 1.1 trillion.  In a fateful contrast to the initial global capex rush into anticipated AI bonanzas, Lebanon meanwhile has still remained a near-pariah of extreme risk in the world-spanning financial ocean of investment flows and has in the exact same 30-month even suffered two episodes of severe war with far-ranging physical destruction and economic disruption.

World-leading investment banks such as Goldman-Sachs and JP Morgan are projecting that cumulative five-year AI project and infrastructure capex from beginning of 2024 to end of 2028 will reach almost $3 trillion in today’s money. As large economic shapers and hosts of countries – for which increased economic productivity is a dream scenario and all but seven of which achieve less than $3 trn in annual GDP – accelerate investments in AI, Lebanon faces a fundamental question: can it transform its exceptional talent into lasting economic advantage, or will it remain an exporter of expertise while others build the ecosystems that capture the rewards?

Artificial intelligence has rapidly evolved from a technological innovation into a strategic driver of economic competitiveness. Governments are no longer asking whether AI will transform their economies but how quickly they can position themselves to benefit from it. The global competition is about building the institutions, infrastructure and ecosystems that allow AI to generate innovation and economic development.

This shift is particularly visible across Gulf countries. Saudi Arabia’s National Strategy for Data and AI aim to attract around 20 billion US dollar in data and AI investment by 2030. Meanwhile, Abu Dhabi Government has allocated approximately 3.5 billion U.S. dollar under its Digital Strategy 2025-2027 to become the world’s first AI-native government by 2027. AI is seen as central to future economic competitiveness.

Years of economic collapse, institutional fragmentation and underinvestment in Lebanon’s digital infrastructure have left the country without the financial resources or enabling ecosystem that support AI development elsewhere in the region. Interviews for this article consistently pointed to one competitive advantage: its people. Despite these challenges, Lebanon continues to produce highly skilled engineers, entrepreneurs and technology professionals, many of whom lead global companies, build AI startups or work remotely for international firms while maintaining personal connections to Lebanon’s innovation ecosystem.

This contrast between abundant talent and limited institutional readiness defines Lebanon’s AI challenge and frames the central question explored in this article: what will it take for Lebanon to move from being AI-capable to becoming AI-ready?

Talent is Lebanon’s greatest competitive advantage

International discussions about artificial intelligence often concentrate on computing power, data centres and technological manufacturing. Those investments of course are important, but Lebanon’s comparative advantage lies elsewhere. Yousif Asfour, Chief Information Officer at the American University of Beirut, leads enterprise technology and digital transformation across both university and the Medical Center. From that perspective he confirms to Executive that “our strength is on the talent. Where we need to develop is the ecosystem around that. Lebanon’s opportunity in AI is less about technology and more about application, innovation and entrepreneurship.”

Artificial intelligence is already part of Lebanon’s economy. Businesses are experimenting with generative AI, university students in Lebanon are learning to build AI models, and Lebanese engineers are contributing to international technology companies in notable ways. Some examples are Karim Atiyeh, co-founder and Chief Technology Officer of fintech company Ramp, which is valued at US$32 billion. Entrepreneur May Habib leads Silicon Valley AI company Writer, one of Forbes’ top AI startups. Samer Abu-Ltaif heads Microsoft’s Europe, Middle East and Africa (EMEA) operations, while 23-year-old Rayan Dabbagh launched AI startup Bounty, backed by Andreessen Horowitz. Yet Lebanon remains largely absent from the institutions, infrastructure and investment flows shaping the global AI economy.

Rather than competing with countries investing billions in AI infrastructure, Lebanon has an opportunity to focus on developing specialised applications, AI-enabled services and entrepreneurial ventures that build on its strengths in education, healthcare, finance and software development. Asfour argues that this should become the country’s strategic direction.

Kamel Alghossainy brings both entrepreneurial and public-sector experience. He is Mayor of Baakline, CEO of Park Innovation- a Shouf-based innovation organisation- and a signatory to the Global Urban Data Centres Pact – a global initiative promoting sustainable and resilient digital infrastructure. He summarises Lebanon’s challenge succinctly: “We are AI-capable, but we are not AI-ready.”

Talent can build companies, create products and generate research. But talent alone cannot create an innovation economy. That requires institutions capable of supporting innovation at scale, the foundations that Lebanon still needs to build.

Building the foundations of AI

Lebanon is not starting from zero. The country has universities, software developers, entrepreneurs and businesses experimenting with AI. The challenge is that these assets operate in isolation rather than as part of a coordinated and integrated innovation system. This gap between talent and an enabling structural support system is perhaps the biggest obstacle hindering Lebanon’s AI readiness.

AI readiness extends far beyond access to tools such as ChatGPT and Claude. It encompasses the institutional, legal, technological and economic foundations that enable AI to be developed, deployed and scaled responsibly. Countries that succeed are distinguished not by the number of programmers they produce, but by reliable infrastructure, effective regulation, high-quality data and effective governance.

In the 2026 Global Index on Responsible AI, a project launched by the Global Center on AI Governance based in Switzerland which looks at metrics such as inclusion, sustainability, trust and safety to measure ethical use and governance of AI, Lebanon ranks 117th out of 135 countries and jurisdictions, with an overall score of 34.26, well below the Middle East and North Africa average of 45.51. The country performs comparatively well in data quality and AI technology diffusion, both above the regional average, suggesting growing adoption of AI technologies. However, it scores substantially below the regional average in the institutional foundations that enable AI to scale, particularly in government digital policy, compute capacity and e-government delivery. The results reinforce a consistent message: Lebanon’s greatest challenge is not adopting AI but creating the conditions that allow it to scale.

Rudy Shoshany, digital transformation expert with more than 20 years of experience advising organisations on digital strategy, cybersecurity and fintech transformation, shares: “Our national AI ecosystem is very weak, the problem is not a shortage of technical talent but the absence of the governance, infrastructure and institutional support needed for AI to scale.” AI ecosystems depend on reliable electricity, high-speed internet, cloud computing, cybersecurity, digital identity systems, interoperable government databases that have high water needs for cooling purposes, and clear regulation. Asfour argues that Lebanon’s infrastructure remains fragmented. “You need connectivity. You also need governance and a legal framework.” That fragmentation extends well beyond electricity shortages. Government systems remain fragmented, digital services are uneven and perhaps the majority of government data has not been digitalized or consistently maintained, and many organisations still lack the integrated digital infrastructure needed for AI adoption.

Much of the debate around AI focuses on sovereign clouds, supercomputers and national data centres. While these investments may eventually become important, Lebanon’s immediate priorities are more fundamental: reliable electricity, affordable high-speed internet, secure government systems and modern data-management practices. “We don’t even have basic proper internet connectivity across Lebanon,” Christophe Zoghbi, founder and CEO at ZAKA confirms. ZAKA is a Lebanon-based AI education and innovation company that helps individuals and organisations across the MENA region adopt artificial intelligence.

Infrastructure alone, however, will not create a functioning AI ecosystem. Clear and balanced regulation is equally important. AUB’s Asfour argues that legal frameworks should protect citizens without discouraging experimentation. “You have to have the legal frameworks to protect people from predatory services and give them enough room to take risks and innovate.” He also makes the point that AI regulation should be considered alongside intellectual property, company formation and bankruptcy rules that shape the broader innovation environment.

Good regulation creates certainty for investors, facilitates entrepreneurship and encourages responsible innovation. When asked about this, Shoshany notes that “the private sector also needs protection, a national data centre, governance, policy and laws to protect it in case any problem happens. All of these are non-existent to this date.”

AI begins with data

“AI means data, without a clear data collection strategy, organisations cannot make effective use of AI ” says Zaka founder Zoghbi, summarising what is perhaps the most misunderstood aspect of AI adoption. The statement appears deceptively simple but has profound implications.

Organisations cannot deploy AI effectively if they do not know what information they possess, whether it is accurate, how it is stored or whether different systems can communicate with one another. Rather than creating value from disorganised information, AI amplifies the quality of existing data and the maturity of the systems that manage it.

“A lot of companies nowadays don’t even have clear data collection strategies,” Zoghbi explains. “They don’t know what data to collect, how to store it, how to structure it or how to make use of it.”

Paper-based records remain common, particularly across public institutions. Data are frequently scattered across departments, stored in incompatible formats or duplicated across multiple systems. In many cases, organisations are still completing the digital transformation that should precede AI adoption. This absence of a data culture limits AI adoption before organisations begin discussing machine learning or generative AI. Without reliable, structured and accessible information, AI systems produce unreliable results, reducing trust in the technology and discouraging further investment.

Another related concern regarding the paucity of digitalized data in Lebanon in particular, but perhaps across other countries in the Arab region, is that AI knowledge can only operate on inputs, and when the archives of Arabic knowledge and culture cannot be accessed, they cannot become part of the source materials that feed into the ways that AI is transforming global learning and behaviour.

Countries with mature AI systems treat data as strategic infrastructure. Data are collected using common standards, stored in compatible formats and governed by clear rules on ownership, privacy and access. This allows information to move securely across organisations, reduces duplication and improves the quality and reliability of the data used to train and operate AI systems. In contrast, when organisations rely on paper records, disconnected databases or inconsistent data collection practices, AI tools become less accurate, less reliable and more difficult to scale.

Lebanon’s Digital Transformation Strategy 2020-2030 recognises many of these challenges. It calls for stronger interoperability between government systems, common digital platforms, improved data governance and wider adoption of open APIs. These recommendations remain highly relevant because digital transformation and AI readiness are not separate agendas. Digital transformation creates the institutional and technological foundations on which AI depends. Without it, even the most advanced AI tools cannot deliver sustained innovation.

Strong data governance also creates confidence. Businesses are more willing to invest in digital systems and AI applications when they know that data are accurate, protected and can be shared securely under clear legal and technical frameworks. Governments play an important role by establishing common standards for data collection, interoperability, cybersecurity and privacy, allowing both public institutions and the private sector to build AI solutions on trusted digital foundations rather than fragmented information.

“The more mature a country is on AI,” Zoghbi observes, “the more data culture you see.”

Government must become an AI user, not only a regulator

Much of the public debate surrounding AI focuses on regulation. Governments are expected to establish legal frameworks, protect citizens’ rights and address emerging risks associated with artificial intelligence. Those responsibilities are essential, but they represent only one part of government’s role.

AUB’s Asfour argues that governments should demonstrate AI’s value by applying it within public administration rather than limiting their involvement to legislation. “The government can both help advance AI by putting in the legal frameworks… but the government can also very quickly demonstrate how AI can be useful by applying it within the government itself.”

The opportunities are numerous. Administrative processes such as driving licensing, permits, document processing, civil registry services and citizen communication are tasks that AI can streamline while maintaining appropriate human oversight.

When public institutions become early adopters, they create demand for local technology firms, encourage innovation and provide startups with opportunities to develop solutions for real operational challenges.  Lebanon’s Digital Transformation Strategy proposes dividing large ICT projects into smaller contracts that are more accessible to SMEs, creating a Digital Marketplace Platform to increase SME participation in government contracts, and expanding the use of APIs to support startups and digital innovation. If implemented, these measures could allow public procurement to support Lebanon’s technology ecosystem while accelerating digital transformation.

Rather than pursuing ambitious national projects that require substantial investment, smaller AI initiatives can demonstrate tangible results, build institutional confidence and generate lessons for wider implementation. Asfour summarises the philosophy: “Small frequent successes are much better than a big vision that never gets there.”

Municipalities offer an equally important opportunity. Drawing on his experience as Mayor of Baakline, Alghossainy argues that local governments can become practical example for AI adoption. While acknowledging that most municipalities still lack the digital infrastructure, technical expertise and financial resources needed to implement advanced AI systems, he has begun introducing AI into Baakline’s daily operations. The municipality has used generative AI to analyse historical budgets, review contracts, and draft standard operating procedures. There are projects initiative to train municipal staff in the use of generative AI. AI-powered legal assistance, administrative tools and citizen services can improve municipal operations without requiring billion-dollar investments. Small-scale projects addressing clearly defined problems often generate faster results than highly ambitious national programmes. It could also reduce waiting times, improve service quality and increase public confidence in digital government.

For Lebanon, the next phase of digital transformation should depend less on announcing ambitious strategies and more on implementing practical AI solutions across public institutions. AI readiness is ultimately not a measure of technological sophistication but of a country’s ability to convert algorithms into productivity, talent into businesses and innovation into sustainable economic growth.

From strategy to execution

Drawing from personal perceptions and conversations, general attitudes around AI adaptation in Lebanon seem to be enthusiastic. Recent years have seen the establishment of the Ministry of Technology and Artificial Intelligence, work towards a national AI framework, consultations with stakeholders and initiatives such as NUMŪ, Lebanon’s National Digital and AI Capacity-Building Programme, to strengthen digital and AI skills. These developments demonstrate growing recognition that AI will shape future economic competitiveness. Yet awareness alone does not create readiness.

“There are talks and discussions,” says digital transformation expert Shoushany, “but there is no action.” While the strategy sets out an ambitious vision for digital transformation, it does not include a dedicated implementation budget or financing plan, making execution more dependent on shifting government priorities and external funding. Implementation has often been limited by institutional fragmentation, political instability and limited administrative capacity.

Progress requires consistent implementation across successive governments, and sustained coordination across government, academia and the private sector. International experience reinforces this point. Singapore has complemented its AI strategy with initiatives such as the Global AI Assurance Sandbox, Privacy-Enhancing Technologies Adoption Guide and the Data Protection Trustmark to strengthen trust, privacy and responsible AI adoption. The United Arab Emirates has introduced a National Artificial Intelligence Security Policy establishing minimum requirements for AI governance, infrastructure security and risk management, while Estonia has embedded data protection, privacy and human oversight into its national AI strategy. These examples illustrate that AI readiness depends not only on innovation, but also on building trusted institutions capable of governing its use.

Lebanon’s is demonstrating that institutions can translate strategy into measurable progress. Success will depend less on ambitious announcements than on consistent implementation, practical partnerships and a willingness to build capability one step at a time.

An opportunity still within reach

Perhaps the greatest misconception surrounding AI policy is that every country should attempt to replicate Silicon Valley. For Lebanon, this would be both unrealistic and unnecessary, and arguably detrimental. The country cannot match the financial resources, global technology, foundational AI research and large-scale computing infrastructure like the United States, China, Saudi Arabia or the United Arab Emirates.

On the other hand, Lebanon does not begin from zero. It has universities, communities of developers, technology companies, entrepreneurs and a large diaspora. It now has a government office explicitly responsible for technology and AI, a public strategy process and capacity-building initiatives. These developments deserve recognition, but they should not be confused with readiness itself. Lebanon’s comparative advantage lies elsewhere: in its skilled people and entrepreneurial ambition.

Lebanese professionals already contribute to international AI projects while working remotely from Lebanon. That model generates valuable income and strengthens technical expertise. However, sustainable economic transformation requires more than exporting skilled labour.

AI will continue advancing regardless of Lebanon’s economic circumstances. The real question is whether Lebanon will create an ecosystem that transforms talent into innovation and economic growth or continue exporting the very people who could build it. Lebanon has already demonstrated that it is AI-capable. The challenge now is becoming AI-ready not through larger ambitions, but through stronger institutions, better implementation and sustained investment in the people who remain its greatest competitive advantage.

September 3, 2026 0 comments
0 FacebookTwitterPinterestEmail
Comment

The rebound is real

by Michael Zoghzoghi September 1, 2026
written by Michael Zoghzoghi

Lebanon’s property market spent the first months of 2026 absorbing the shock of renewed conflict. Credit Libanais’ economic research unit, reporting at the end of June 2026, put the number of real estate transactions down 32.25 percent year-on-year over the first five months of the year, at 19,097 against 28,189 a year earlier, with total transaction value down 17.79 percent over the same stretch. The bank tied the slowdown directly to the fighting that reignited in early March.

The recovery, when it came, was fast. Credit Libanais recorded the first sign of a turn in May, when transactions ticked up 4.64 percent month-on-month following the mid-April ceasefire announcement. June then accelerated sharply, with 4,999 transactions, per BLOMINVEST Bank’s reading of Land Registry data, before July added another 6.18 percent to reach 5,308 deals — the highest monthly level recorded so far in 2026, according to Credit Libanais’ August 18th reading of Land Registry data.

The rebound should not be confused with a full recovery. Credit Libanais’ cumulative figures, reported mi-August 2026, show 29,404 real estate transactions recorded through July, still 25.54 percent below the 39,490 registered over the same period in 2025. Transaction value, however, was down by a much narrower 5.36 percent, at roughly $3.25 billion. For those of us active in the market, the shift was visible before the latest numbers confirmed it: inquiries that had gone quiet during the spring disruption began converting again as conditions stabilized.

Financing tells a slower story. Banque de l’Habitat, the state-backed lender that relaunched its subsidized housing loan program in 2024 after more than five years of suspension, has gradually expanded its activity. As of July 2, it had granted 1,059 loans worth $74 million, including 980 loans for apartment purchases worth $68.9 million, according to figures reported by the bank to L’Orient Today in July.

The bank also cut the annual interest rate on loans financed through the Arab Fund for Economic and Social Development from 6 percent to 5.75 percent from July 1, after Banque du Liban waived a 0.25 percent management fee, L’Orient Today reported. The Arab Fund credit line, worth roughly $165 million, had already enabled Banque de l’Habitat to raise the maximum subsidized housing loan from $50,000 to $100,000 in 2025.

It is real progress, particularly for the low- and middle-income households the program is intended to support. But the scale remains modest beside the size of Lebanon’s property market. For many buyers, particularly those looking in the country’s most expensive districts, the availability and size of financing remain a significant constraint.

That constraint interacts with geography in a way that deserves more attention. DoorEast, an AI-powered real estate marketplace that I co-founded, releases Market Trends & Insights data which tracks advertised asking prices across hundreds of locations. This data shows just how wide Lebanon’s price spread has become. Downtown Beirut averages around $6,402 per square meter; Ras Beirut sits closer to $4,415. In Achrafieh, the Carré d’Or pocket runs at about $3,700, against roughly $3,091 for the district overall. Move further out and the numbers fall quickly: Jounieh averages around $1,744 per square meter, Dekwaneh about $1,378, Jbeil closer to $972, and Dawhet Aramoun roughly $842.

These are asking prices, not closed-sale figures. In Lebanon’s negotiation-heavy market, the difference can be substantial, and individual properties can sit well above or below an area’s average depending on age, condition, floor, view, finish and exact location.

But the spread still tells us something important about where financing has meaningful purchasing power. At DoorEast, the pattern we see across listings and buyer inquiries suggests that part of the premium in central Beirut reflects the concentration of dollarized and cash-backed demand in prime locations, including demand from Lebanese buyers abroad. Further from the capital’s most expensive districts, asking prices are considerably closer to the budgets of buyers who depend more heavily on local income and financing.

This is where the financing story and the price-geography story meet. Banque de l’Habitat currently offers purchase and construction loans of up to $100,000. Measured against DoorEast’s asking-price averages, that amount is equivalent to roughly 16 square meters at Downtown Beirut prices or 23 square meters in Ras Beirut. The same $100,000 is equivalent to around 57 square meters in Jounieh, 73 in Dekwaneh, 103 in Jbeil and 119 in Dawhet Aramoun.

The comparison does not mean that a borrower with a $100,000 loan can only purchase a property of that size. Buyers can, of course, contribute their own equity or other funds, and Banque de l’Habitat’s financing can form only part of the purchase price. Rather, it illustrates how dramatically the purchasing power of the same financing facility changes depending on location.

LocationAvg. / m²$100K equivalent*$500K buys
Downtown Beirut$6,40216 m²78 m²
Ras Beirut$4,41523 m²113 m²
Carré d’Or, Achrafieh~$3,70027 m²135 m²
Achrafieh (district avg.)$3,09132 m²162 m²
Jounieh$1,74457 m²287 m²
Dekwaneh$1,37873 m²363 m²
Jbeil$972103 m²514 m²
Dawhet Aramoun$842119 m²594 m²

*Approximate floor-area equivalent of Banque de l’Habitat’s $100,000 maximum housing loan and of a $500,000 budget, calculated using DoorEast’s advertised asking-price averages. The $100,000 figure represents the purchasing-power equivalent of the loan amount, not the maximum property size a borrower can purchase. Figures are illustrative and do not represent specific listings or closed transaction prices.

In practice, that makes the current subsidized lending program considerably more powerful in Mount Lebanon and outer-suburban markets than in central Beirut. The loan can materially close the affordability gap in lower-priced areas; in prime Beirut, it is much more likely to function as one component of a purchase requiring substantial additional equity.

That difference matters beyond individual buyers. If meaningful housing finance has greater purchasing power outside the capital’s most expensive districts, it can gradually reinforce demand in those areas. That could have implications for where residential development, infrastructure needs and services grow over time. Central Beirut, meanwhile, is likely to remain more dependent on buyers with significant cash or equity unless financing products become large enough to bridge a greater share of its price levels.

The geography of Lebanon’s property market makes the limits of a uniform financing ceiling clear. A $100,000 loan represents a meaningful share of the purchase price in some areas and only a fraction of it in others. That does not make the program ineffective, but it does mean its impact on affordability varies considerably depending on location.

At the same time, recent transaction figures suggest that activity can recover relatively quickly as market conditions stabilize. The harder question is whether that rebound can extend beyond buyers who already have access to substantial cash or equity.

That is the distinction worth watching. A recovery in transaction volumes is one measure of a healthier property market; broader access to financing is another. In Lebanon today, the two are not yet moving at the same pace.

September 1, 2026 0 comments
0 FacebookTwitterPinterestEmail
Analysis

Improbably spared

by Marie Murray August 18, 2026
written by Marie Murray

This analysis was written for a Spring 2026 Special Report on the repercussions of conflict on local economies

On March 30, 2026, acting president of Syria Ahmed al-Sharaa, flew to Germany to discuss the return of Syrian refugees, post-war reconstruction, and economic cooperation with Chancellor Friedrich Merz and President Frank-Walter Steinmeier in a visit aimed to strengthen bilateral relations and secure investment, focusing on Syria’s economic stabilization.

It was only the second visit of a Syrian head of state to Germany after then-chancellor Gerhard Schroeder afforded a controversial welcome to Syria’s now-deposed Bachar Al-Assad to Berlin in 2001. At the time, a German proposal for “change through [economic] collaboration” and a peace plan for the “Near East” were discussed amidst ruckus over reported anti-Semitic ranting by the Syrian ruler. In hindsight, there can be no denying that subsequent progress towards peace through an immediate halt to violence and “essential” restoration of trust between the government of Israel and the Palestinian Authority along the lines of a Sharm-El Sheikh agreement from 2001 (referred to in Germany as Mitchell plan) didn’t come to be. Instead, the official German ambassadorial presence in Damascus was suspended from 2011 to 2025 and economic sanctions were imposed in response to brutal oppression of the Syrian population by the Assad regime.   

This time, the hope was for a very different outcome, even as the regional context was deteriorating from severe to disastrous. Around the time of al-Sharaa’s Berlin visit, US President Donald Trump started threatening Iran with a bombardment “into the stone age” and an erasure of Iranian civilization overnight. Closer to Syria, the Israeli settler assaults against their Arab neighbors in the West Bank were reaching fever pitch. The number of civilian casualties under the Gaza ceasefire remained unconscionable. The IDF targeting of Hezbollah operatives in Lebanon was relentless and far beyond the scope of international law precedents with destruction and damage of 62,000 housing units between March 2nd and April 22nd, according to the Lebanese National Council for Scientific Research (this is in addition to the Ministry of Environment’s estimate of 200,000 damaged and decimated homes between 2023-2025)  and mounting civilian casualties beyond measure. And Iran tightened its grip on Hezbollah decision-making in Lebanon.   

From a big picture perspective, things this April 2026 look very different for al-Sharaa’s Syria, in sharp contrast to the regional turmoil. The country was mostly spared not only cross-border military assaults; the risks of new conflict seem subdued and the investment climate appears the most benign in many decades.

The new narrative of Syria is, however, still untested. When the Assad regime collapsed on 8 December 2024, Syria stepped out of 13 years of civil war and economic isolation and into what its transitional president has hyperbolically called “a land of opportunities.” Prospective investors, primarily from the Gulf states, are presumably well aware that the gap between the promise and the reality of Syria’s economic reconstruction is vast. Moreover, so far there are no signals of Arab investor reticence in face of a regional context that has become increasingly complicated, as a result of the joint US-Israeli war on Iran and its complexification of the very regional dynamics that were supposed to hasten the development opportunities for the new friends of the hegemonic power axis Washington-Tel Aviv-Riyadh.

Meanwhile, prospects for regional integration with Lebanon are simultaneously and paradoxically poised for growth and weighed down by the Israel-Hezbollah war systematically demolishing its south, devastating more than just the southern suburbs of its capital city, and shoving the country towards deeper internal divisions amid mass displacement and extreme loss of lives, land and livelihoods. Geography and history indicate that future investments into Syria will have massive implications for the – significantly smaller but also significantly more mature – Lebanese economy. This suggests that Israel’s actions in Lebanon make for an additional complication of any Syria investment gambit. Syria’s position of cautious neutrality might be safeguarding new investments, but the turbulence of the region at large is raging ever closer.

The Gulf bet

One challenge for investors looking to gauge the Syrian economy is that it cannot be confidently measured. A March 2026 policy brief released by the Syrian Center for Policy Research (SCPR) found that the Sharaa government presents indicators of economic performance which imply a rapid recovery of GDP and an imminent return to pre-conflict levels. These governmental data, published without a clear methodology, did not distinguish between GDP at current prices and constant prices, or clarifying the effect of multiple exchange rates and inflation on the announced value. According to SCPR, the use of undocumented macroeconomic indicators hints at possible exaggeration of potential investment returns. It reveals the marginalization of the national data system and the treatment of GDP as an instrument of political discourse, which is not likely to improve investor confidence or public trust.

The SCPR estimates that real GDP in 2025 achieved only nominal growth of about 0.3 percent compared with 2024, while real GDP per capita declined by about 6 percent. The less than impressive bottom-line performance of the first full year under a new government is owing to weak organic growth combined with strong population growth associated with the return of refugees. The actual size of GDP in 2025 did not exceed about 45 percent of its 2010 level at constant prices.

Absence of recent organic growth (coming from investments of domestic savings and/or governmental budgets and economic stimuli), expanding, youth driven market size, and massive demand for anything from housing and infrastructure to consumables in principle denotes both a vacuum of unmet household needs and a fantasy scenario of virgin investment. Into this void, Gulf states have moved in speedily and ambitiously. Qatar, Saudi Arabia, and the UAE were among the first nations to endorse Syria’s new leadership, with President al-Sharaa invited to visit all three countries multiple times since taking office in a bid to secure economic support. Major commitments include a $7 billion energy infrastructure deal led by Qatar’s UCC Holding, a $6.5 billion aid pledge from international donors, and an $800 million port development agreement with Dubai-based DP World.

Already in the first half of last year, Syrian investment projects by potent Arab economies were piling up impressively into aggregate numbers not previously reported from Syria. At the Syrian-Saudi Investment Forum in Damascus in July 2025, 47 initial agreements and MoUs were signed between Syrian state institutions and Saudi companies, with a total value of $6.4 billion, covering infrastructure and real estate development, telecommunications, information technology, industry, tourism, and health. This is according to a September 2025 report by the New Zealand-based consultancy Karam Shaar, which covers Syria’s political economy.

Not only Gulf governments but also Arab-led transnational development action forums such as the Future Investment Initiative (FII), a sort of desert power play on the tiring Davos paradigm of the World Economic Forum, have shifted into high investment promotion and readiness gear. At the FII conference in Riyadh in October 2025, al-Sharaa announced that Syria had attracted foreign investment pledges estimated at around $28 billion during the year, with signed contracts nearing $14 billion, focusing on infrastructure, transport, and several major development sectors according to North Press Agency.

BOX

Perhaps the ambitious scope of Arab corporate investment into future Syria is most physically visible at Damascus International Airport, the country’s primary gateway. Qatar-based conglomerate UCC Holdings’ $4 billion redevelopment and expansion program of the crucial aviation facility — one of the flagship deals anchoring the investment surge — is already underway. Younes Sayed, a Paris-based architect who is serving as program manager and lead architect on the project, describes an endeavour that is self-consciously about more than runways and terminals.

“The objective is not only to re-establish Damascus as a regional hub, but to position it at a continental and even international level, by aligning with global standards in terms of capacity, connectivity, and passenger experience,” Sayed tells Executive. The project is a phased modernization of Terminals 1 and 2, with a future Terminal 3 designed in collaboration with Zaha Hadid Architects and Dutch aviation consultancy NACO — a pairing that signals the al-Sharaa government’s intention to project international-class ambition to potential investors and diaspora returnees alike.

Sayed acknowledges that the project is “evolving in a complex environment,” deploying a fast-track approach that runs design and construction in parallel to maintain momentum despite what he calls “ongoing changes,” an understatement for the US-Israel war on Iran which is hurting Gulf Cooperation Council (GCC) economies and could threaten their investment commitments.  He is pragmatic about timelines: “All stakeholders are making every effort to ensure that the current situation does not lead to delays. We are continuously adapting to evolving conditions and adjusting our planning as needed.” Asked about the project’s connection to the country’s broader reopening, Sayed is optimistic, stating that the airport’s renovation and expansion is “a strategic catalyst that, if aligned with broader stabilization, can significantly contribute to reviving tourism and restoring Syria’s position internationally.” But, he emphasizes, that outcome depends on a set of preconditions — stability and security, resumed airline connectivity, and, crucially, restored investor confidence in tourism, hospitality, and services.

The issue of underdeveloped economic infrastructure is a heavy caveat. The scale of announced investments far exceeds Syria’s underlying economic capacity: the value of MoUs ($25.4 billion) dwarfs total government investment expenditures between 2010 and 2024, which, according to Karam Shaar’s September 2025 report, stood at $16.6 billion. These are not the conditions of an economy on the cusp of absorbing tens of billions in foreign investment.

END BOX

The war on Iran, Syria’s precarious insulation, and Gulf disillusionment

No factor has more immediately reshuffled Syria’s investment calculus than the US-Israeli war on Iran, which erupted in early 2026. But already before this regional and global shock event, Sharaa-led Syria has taken steps to curtail Tehran’s influence within and without its territory, including limiting Iran-aligned armed groups, tightening controls along Lebanese and Iraqi borders, and cracking down on smuggling networks long used to move weapons, cash, and supplies to Hezbollah.

Caution was also evident on the part of prospective Arab partner states such as the Gulf Cooperation Council (GCC). The GCC’s approach has been deliberately conditioned: the first GCC-Syria joint ministerial meeting in Makkah in March 2025 emphasized that disarming militias and concentrating weapons in state hands would be an important part of Syria’s reintegration into the Gulf’s security architecture. Gulf investment is based on a wager that a stable, Gulf-oriented Syria is worth the political risk. It must not be forgotten that Syria’s relations with many Arab states have historically been no less complicated than those with states in the EU, such as Germany. 

While the successful recalibration of Syrian external relations cannot be seen as a cut and dry affair – far from it – there are signs that this rapprochement strategy is bearing fruits not only in big infrastructure projects but also in vital services, such as the financial services sector. Lebanese banker Riad Obegi, a senior executive at Bank Bemo Saudi Fransi — Syria’s largest private conventional bank — offers a banker’s reading of Damascus’s position in the regional constellation. “Apparently, the Americans have said that the Syrians should be left out [of the conflict],” he tells Executive. “The whole region is in turmoil but Syria — it is as if it is in Europe.” From his vantage point, Syria’s deliberate distancing from the Iran axis, and the tacit US endorsement of the transitional government, is providing a degree of fortuitous geopolitical insulation.

The economic disturbances from the Iran conflict, however, are harder to insulate against. The conflict has driven a sharp rise in global energy prices and disrupted key shipping routes through the Strait of Hormuz. But old export routes for Syrian hydrocarbons, which could ride profitably on the Hormuz conundrum, have been degraded over the decades that the Assad regime had been sanctioned and negligent in preserving fossil fuel assets. Amid this maelstorm, Syrian media organization Enab Baladi reported that as of March 31, 2026, Iraq has reopened the al-Waleed border crossing with Syria, enabling crude oil to be transported across Syrian territory to the Mediterranean, with an estimated 500 tankers expected to pass daily via the al-Tanf crossing towards the Baniyas terminal for onward export.

Activation of Syrian oil was also proposed in a presentation by US Special Envoy to Syria (and US ambassador in Ankara) Tom Barrack during a March 26 conference in Washington hosted by the Atlantic Council and Syrian American Business Council. The idea floated by Barrack – and also reported by Enab Baladi – was to revive the concept of Syria and Turkiye as joint energy centers in The Four Seas corridor first theorized in 2009. A dual Turkish-Syrian hub for transporting crude oil and gas would theoretically link the Arabian Gulf, the Mediterranean Sea, the Caspian Sea and the Black Sea, and—conveniently for Washington-affiliated opportunists—serve as an alternative to the Strait of Hormuz.

The broader context of the Iran conflagration is not only major hits to GCC economies, but also a fracturing of the strategic architecture that ties Gulf states to the US government and, by extension, to American-backed regional security. With the launch of the first missiles and bombs on February 28 of this year, Gulf states were dragged into a war they never chose, to serve an agenda that was never theirs, while their security was traded away to protect Israel rather than them — a reality that has fundamentally exposed the true nature of Washington’s alliances in the region. This erosion of trust in American reliability might be, paradoxically, a structural tailwind for Gulf investment in Syria. As the US security umbrella proves unreliable and Israeli aggression generates its own blowback, the Gulf states’ incentive to build self-sustaining regional economic architectures — with Syria as a key node — has intensified.

Syria’s Banking System: The Foundational Bottleneck

If geopolitics frames the macro-context, the banking system is one of Syria’s most immediate structural bottlenecks. No reconstruction investment can be effectively deployed, and no investor can repatriate returns, without a financial sector that meets international compliance standards. The International Monetary Fund (IMF) warns that lifting legal sanctions does not automatically translate into Syria’s return to the global financial system — due to ongoing de-risking policies whereby international banks avoid dealings with post-conflict countries because of weak compliance systems, money-laundering risks, and a lack of institutional transparency. The IMF’s February 2026 staff visit to Syria cited a small fiscal surplus and tentative stabilization, as well as improved exchange-rate conditions alongside authorities’ steps toward introducing a new currency framework to address distortions in the monetary system.

Bank Bemo Saudi-Fransi’s Obegi has a front-row seat to this transition. Bank Bemo Saudi Fransi — a joint venture between Lebanon’s Bank Bemo, Saudi Arabia’s Banque Saudi Fransi, and Syrian shareholders — is the largest private conventional bank in Syria, and holds stakes in two other Syrian banks. His assessment of the current landscape is guardedly optimistic. “Syria is no more sanctioned. The Caesar Act has been withdrawn,” he says. “It is true that international banks are not yet coming; they are waiting a little bit. But things are improving by the day.” He draws an analogy that practitioners will recognise from any frontier banking market: “We take our decisions quite slowly, but the day we take the decision we like to act fast. It is a necessary inertia, but it will come. International banks are going to come in droves to Syria.”

“The regulations are much better in Syria than they are in Lebanon,” says Obegi, who is intimately familiar with both regulatory regimes. “You do not have as much professionalism [in Syrian banks] as in the banks in Lebanon. And what is strange is that on the other hand, the regulations are much better in Syria than they are in Lebanon.” The implication is that Syria’s banking framework, while underdeveloped in human capital and balance sheet depth, has not been embroiled in a state level corruption scheme the way Lebanese banks have. Crucially, he notes that Syrian depositors, unlike their Lebanese counterparts, “did not lose any deposits” in the crisis — a distinction that preserves a baseline of institutional trust that Lebanon has catastrophically squandered.

Syria’s reconnection to global payment system SWIFT in November 2025 after a 14-year suspension is also a step forward. The demand side of the equation, however, is a work in progress. “The Syrian clients were not accustomed to working with banks,” Obegi explains. “Until 2004, there were very few banks. Syrian clients preferred either to be their own bankers or to bank in Lebanon. After 2004, Syrians began to work with banks but the rate of bancarisation was not very high.” He sees mobile telephony as the accelerant that will compress the timeline for broader financial inclusion: “If you look at the penetration of mobile phones in Syria, it happened relatively fast. You have to expect that banking will follow. It will take maybe 4-5 years before bancarisation is comparable to Lebanon.”

His broader prediction, taking stock of Gulf investment movement into Syria is that,”what is going to happen to the banking sector in Syria is going to be the locomotive for the finances in the Levant.” According to SCPR’s March 2026 report, gaining sustained investor confidence will require a credible anti-money laundering framework that is implemented rather than merely promulgated; transparent and enforceable property and contract rights backed by a genuinely independent judiciary; consistent regulatory practice by the central bank freed from political interference; and the reconstruction of an independent and transparent national data system as a primary precondition for recovery.

Global Competition, Regional Integration, and Lebanon

Syria in April 2026 occupies a paradoxical position: simultaneously the most talked-about investment frontier in the Arab world and one of the least investor-ready economies on earth. The SCPR’s data are unsparing: real GDP at 45 percent of its 2010 level, agricultural output in near-collapse, manufacturing at one-fifth of pre-war capacity, and governance structures treating economic statistics as propaganda instruments. The $28 billion in pledged investment is a signal of regional intent, though not necessarily a bankable pipeline.

What Syria has working in its favor is a convergence of factors that did not exist three years ago: full sanctions relief, Gulf patronage now marked by deepening disillusionment with American reliability, a transitional government that has adopted the rhetoric and some of the substance of reform, and a regional conflict that has, so far, spared Syrian territory while possibly elevating its value as a transit corridor. Flagship projects like the Damascus airport expansion demonstrate that serious international professionals are betting on Syrian recovery, even while managing the contradictions of a fast-track approach in a still-fragile state.

Factors of attractive investment return potentials, strategic territorial alliances, and cultural affinity have visibly positioned public and private (and public-private) Arab investments on advantageous starting blocks for capitalizing on the Syrian economy. Within the opacity of conflict timelines, what can be predicted is that competitors for the Syria-plus development opportunity will hit the ground running from the moment that the lose-lose logic of regional war will be overtaken by the more pragmatic logic of economic competition and political coexistence. The question of whether political signals by European governments will be strong enough to overcome perception risks on the Syrian side and old or new colonial attitude barriers on the European side, cannot be reliably gauged.

Syria’s most consequential if not deeply complex near-term economic relationship is with Lebanon, and both Sayed and Obegi point to signs of pragmatic re-engagement even amid political complexity. Strictly segregated development paths in the face of synergetic development needs do not seem to make sense. Banking and financial services on the other hand could offer entry points.

Obegi notes that Lebanese banks were the dominant private foreign players in Syria after the 2004 liberalization — Bank Byblos, Bemo, and others moved in on the assumption that Syria was Lebanon’s natural hinterland for financial services. For the experienced banker, this historical flow of financial interest is now on the cusp of being inverted.

Sayed, working on the Damascus airport project, describes what he sees from the ground level of a practical cross-border professional: “There are clear signs of a gradual and pragmatic re-engagement between Lebanon and Syria, although it remains complex and cautious. Recent dynamics suggest a willingness on both sides to rebuild more institutional, state-to-state relations based on mutual interests such as border management, economic exchange, and security coordination.” He qualifies this carefully: “At this stage, it is more a form of pragmatic cooperation than a fully structured strategic alignment.”

Obegi, whose bank sits at the intersection of Lebanese, Saudi, and Syrian capital, points to the deep financial interdependencies that predate the political rapprochement. “There is a lot of closeness between Lebanon and Syria. In the banking sector, if you look at the 40 banks in Lebanon, you have at least five banks owned by Syrian-origin people. There are also a lot of trading companies in Lebanon that are Syrian-owned.” The directional flow of capital, he suggests, is about to reverse: “Before the problems in Lebanon, Syrians banked in Lebanon. I guess now Lebanese will bank in Syria.”

Energy integration may be the most tractable entry point. Lebanon, currently deadlocked by bombardment and delayed reform, could, in a so far still distant peaceful future, explore the potential of joining interconnection initiatives with Syria, Jordan, and Egypt, and reviving negotiations on electricity connectivity — projects previously strangled by Caesar Act sanctions that penalised any entity transiting Syrian territory.

Meetings between Lebanese Prime Minister Nawaf Salam and President Sharaa in April 2025 in Damascus and July 2025 in Qatar, as well as a September 2025 meeting with Lebanese President Joseph Aoun, among other phone calls and videoconferences, have convened on border management, refugee affairs, and economic cooperation, reflecting a strategy of pragmatism and institutionalism focused on practical issues directly affecting security, economy, and society. Unresolved grievances persist, such as the over 2,000 Syrian detainees held in Lebanese jails, though local news reported that Lebanon has begun a process of returning around 300 of them in mid March 2026.

Obeji flags a macro constraint that overhangs all of these dynamics: “The war with Iran is not a small thing. Not only because Iran is a large country of 100 million inhabitants with a lot of natural resources, but also because it has repercussions with China. As long as this is not resolved, we are not going to have clear-cut advances.”

August 18, 2026 0 comments
0 FacebookTwitterPinterestEmail
Analysis

The new geopolitical economy

by Thomas Schellen August 17, 2026
written by Thomas Schellen

This analysis was written for a Spring 2026 Special Report on the repercussions of conflict on local economies

For a group that is as notoriously divisive in their analyses and divided in their predictions as the global top-gun advisory class of economists, the consensus is glorious. The current global economic climate worries all expert voices into pointing to gathering storms of universal uncertainty. But this unanimity on the global economy in spring of 2026 is nothing glowing. It is only gloriously universal. The analogy? Everyone takes notice of a deliberate mega-truck crash. 

The economic hurricanes of spring 2026 have been attributed overwhelmingly to one pivotal event and a single point of origin: the US-Israeli “preemptive” war on Iran and the resultant and predictable confrontation in Arabian Gulf maritime trade with its bottleneck at the Strait of Hormuz. Beginning with the strike against the Iranian supreme leader and the short-lived justification of targeting regime change for the liberation of the Iranian people, analysts of short-term economic estimations and predictions into a cacophonic chorus chanting “risk”.

Most of these downward risk alerts stem from the underestimated economic impact of war in the Middle East. Some, however, carry over from warnings already raised last year.

In this multi-year context, the outlook carries different weight for different economies. High-income countries — around 65 UN members and 20+ small territories — will feel the strain but are better positioned to cope. For low-income and least-developed nations, the outlook reads like a horror story. And for the more than 100 countries stuck in the ‘Middle Income Trap’ for two decades or more, it is deeply alarming.”

The message for the last group of countries appears to be that their inclement geoeconomic climate outlooks of the 2020s have been further negatively accentuated in March and April of this year by sudden, unpredictable and often contradictory swings of hyper-sensitive economic indicators that will badly affect them. This is the case even though these were distant swings driven by actions and harsh threats entirely out of their control.

The granular picture

In step one of shock impacts from the Iran war, global markets internalized their uncertainty by fluctuating. The first big swings were seen in markets for crude oil and gas, with leading oil prices surging month-on-month from end February to end March by around $35 and $23 for the two benchmark categories Brent & West Texas Intermediary (WTI). By the end of March, and specifically in the wake of political remarks at that time, crude oil prices leapt up about 40 (WTI 30) percent per barrel (bbl).

Moreover, the volatility continued throughout the month of April. Not only were crude oil prices skyrocketing by approximately 20 further percentage points over the course of the full 61 days from Feb 28 to Apr 30, vacuous political and security rhetoric was additionally mirrored in two temporary price drops from more than $100 bbl to less than $90 (and back up again) in March, and two further massive swings in April.

That rigmarole was enough to ring inflation alert bells in global oil markets and it did, loudly. But already before the first bells over the price increases of March 2026 even stopped ringing, international crude prices reverberated in the form of inflationary influences across developing and developed, national energy and transportation sectors. In the developed world, notorious price jumps were flagged by media from gasoline at the pump in the US to heating oil prices predictions for the UK winter that is at least half a year away. Yet, such sensational developed market consumer shocks were just the starting shots of serial worry signals ringing out perhaps more quietly but also more seriously from countries around the world.

Normally attracting at best minor attention in daily reporting, prices for industrial feedstocks and chemicals, as well as the rare gas helium produced as sideline by-product of natural gas extraction, rose at varying speeds and peaks. Apart from helium that is crucially required in medical and technical manufacturing, industrial manufacturing commodities such as ammonium, naphtha and Sulphur, benzene, and styrene, ethylene, propylene and methanol suffered inflationary pressures. All this extreme volatility and peaking of source prices, which occurred in tandem with Strait-of-Hormuz related supply disruptions, continued on international markets through the month of April and into May as of the time of this writing.

National-level repercussions were felt, with wide differences, across countries on all six permanently populated continents, in sectors from travel to healthcare, hospitality to manufacturing, mortgage finance to agriculture. Quickly, international organizations engaged in the fight of improving food security for the global precariat, rang their own alarm bells. International NGO Mercy Corps warned in mid-April “The food security consequences of this war are already written into harvests that have not yet been planted.“

Price inflation in energy markets drew the heaviest attention but price spikes and supply disruptions for commodities swapped further: they surfaced as volatility across equities markets, drove up costly bond yields, impaired mortgage rate outlooks, impacted currency markets and consumer price trends. In the two-month bottom line, inflation pressures and economic demand-supply twists since outbreak of the Iran war have by end of April hurt many economic actors and favored some.

The lesson of it all might forcefully remind the peoples of the world of the intense interdependence and interconnections of the globalized economy. After a month of war, immediate inflationary pressures and turnover contractions were reported from the most ostentatious boudoir of the rich as well as the most private bedrooms. Specifically, the CEO of a leading global market producer of condoms in Malaysia warned in late April of impending 20 to 30 percent price increases for their products that would obstruct household family planning mostly in poor populations. About a week earlier, the head of conglomerate LVMH warned of an impending crisis of the group – under whose umbrella such symbols of wealth as Bulgari, Dior, Givenchy, distillery Hennessy, Kenzo, Louis-Vuitton, winery Moet, Tiffany, etcetera are held – if the Iran war does not find its end quickly.

Profiteers of the Iran conflict include energy companies, defense exporters, stock exchanges, investment banks, financial advisors, management consultants, currency and commodity traders, prediction market platforms, and renewable energy firms — though their gains stem from a mix of causes, not solely the conflict itself.

“It’s clear that artificial intelligence, global fragmentation and inflation will continue to permeate through economies and the markets,” comments financial group JP Morgan, one of the large banks writing extraordinary profits in the first quarter of this year (net income was up 13 percent year-on-year to $16.5 billion), says in its 2026 mid-year outlook. Premiums on security and technology moreover are expected to persist and governments, corporations, and wealthy citizens are demonstrating their willingness to pay extra for being warned against an economic shock, according to JP Morgan’s May 8th statement.

According to Kriti Gupta, global investment strategist at JP Morgan Private Bank, energy risk premiums, unrelenting inflation ranges, and security-driven rerouting of supply chains are likely to sick to markets over long term.

In its dichotomous way, the story of the Middle East 2026 shock thus reiterates how the value of the markets is that of a universal decentralized computer with an operating system coded by utility and profit. Thus, as much as the logic of social values and human priorities has been impaired by all that was instigated by each and every conflict actor, large and small, state and non-state, in the Iran war, the capitalist logic of the markets emerges unscathed.

 A strong voice in the midst of even stronger winds

It would be spurious to assume that this narrative unfolded without throwing its shadows ahead. At time of this writing, the assessment of impending risk accumulations of inflation, technology, global competition and even trade wars  are confirmed by the International Monetary Fund (IMF), arguably the world’s most vocal and best-reputed public economy powerhouse. But already in advance of the IMF 2026 spring meetings, three international agencies of import – IMF, World Bank, and the International Energy Agency – announced the formation of an action group to monitor developments, align analysis, and coordinate support to policymakers to navigate this crisis.

“At these times of high uncertainty, it is paramount that our institutions join forces to monitor developments, align analysis, and coordinate support to policymakers to navigate this crisis,” a joint statement of IMF, WB, and IEA said on April 1.

The IMF’s latest analysis of the world economy is augmented by a critical term that puts the situation in context of uncertainty. “After withstanding higher trade barriers and elevated uncertainty last year, global activity faces a major test from the outbreak of war in the Middle East,” reads the laconic opening statement of the April 2026 World Economic Outlook (WEO) on the IMF homepage.

Uncertainty is the huge caveat in the IMF’s scenarios for 2026. Even the WEO’s less pessimistic scenario, described as a reference forecast and apparently based on a lot of hopeful assumptions, predicts a slowing of global growth to 3.1 percent – modestly revised downward versus a scenario of 3.3 percent not even six months ago. Twenty basis points may sound inconspicuous but comes to an amount north of $250 billion over a World Bank/IMF global nominal GDP estimate of $126 trillion at the end of this year. Headline inflation is expected to rise to 4.4 percent, in the best case.

On top of representing a lower growth expectation than economies achieved in the past two years, this prediction acknowledges that pressures of inflation and growth constrict loom most painfully over emerging markets and developing economies.

Moreover, this already subdued growth picture is stuffed with massive downside risks, the dominant and most severe risk being a prolonged and/or expanding Middle East war. More intense and longer war could slice between estimated 0.6 and 1.1 percentage points from 2026 growth and speed inflation up by 1 to 1.5 percentage points, the IMF says.

Other looming risks – worsening trade conflicts, increasing geopolitical fragmentation, and disappointing productivity gains from the global AI hype – are in line with consensus views of economists even as they are denied in political discourses. Future disruptions in an increasingly uncertain global environment need to be prepared for, the fund advises. In short, the ominous truth of uncertainty seems to settle in as operative geo-economic term.

In the words of unflappably enthusiastic IMF Executive Director Kristalina Georgieva at her curtain-raiser speech for the 2026 spring meeting, the assembled governments would have to focus on weathering the latest, war-induced shocks to the global economy and ease the pain of the people. She follows this up by warning the 191 IMF member countries to “get their house in good order, because when this shock [of the Iran war] dissipates, there will be another one to come”. 

Her cautious note of hope against the miasma of war, trade conflict and uncertainty calls for member countries’ cooperation. Despite all tensions and fragmentation, “there is so much potential in working together within regions, across the globe,” she enthuses. 

Shocks, aftershocks and ripples across the region

Across the vast Middle East – Central Asia territory (comprising 32 countries in the Middle East, North Africa, Pakistan, Afghanistan – MENAP – as well as the Caucasus and Central Asia, or CCA), the shock of the Iran war affected Arab countries, especially GCC economies, in vastly divergent ways. GCC member Qatar experienced the largest downward correction for the year, at 14.7 percentage points, whereas GCC peers Saudi Arabia and Oman saw their predictions contract by 1.4 and 0.5 percentage points.

On Lebanon, no comparable numerical impact estimation of the regional downturn is available. “For Lebanon, the ongoing war poses acute risks by intensifying pressures on trade, foreign reserves, and humanitarian conditions, for example, stemming from internally displaced people, while further heightening uncertainty”, is the single whole sentence dedicated to the country in the 22-page update.

In regional terms, the fog of uncertainty was so dense for so many weeks that the leading heads of the IMF’s Middle East and Central Asia department concede at the end of this year’s spring meeting that economic trajectories appear to be vacillating in deeply uncertain territory between the WEO’s “reference” and “adverse” scenarios.

The regional outlook by IMF estimates and projections is now 1.4 percent GDP growth in 2026, says Middle East and Central Asia department head Jihad Azour. According to Azour, this downward adjustment of 2.3 percentage points in the space of only a few months marks a record for such region-wide revisions.

Announcing gravely that “the shock is deep, broad and still unfolding” at time of the discussion with media on April 16, Azour and his deputy Roberto Cardarelli explain that their latest findings’ level of uncertainty is high and tilted towards downside risks. They also argue that non-energy scars left by the war’s disruptions in the regional economy could be bigger and more difficult to read than the scars inflicted on the energy sector.

What they can state with confidence in press briefing on the newly updated regional development report is the very uncomfortable observation that, in the words of Azour, the war outbreak on February 28 “disrupted three pillars of stability” that are vital for the regional and global economy – namely energy markets, trade routes, and business confidence.

A volatile geoeconomic outlook

 In sum, the IMF’s expectations for economic growth across the diverse and dichotomous region have been lowered by an astounding two thirds essentially because of the single, but massive, war shock – but even this downward revision is not a confirmed last word on the multi-actor confrontation’s economic fallout. The WEO overall reinforces widely shared expectations in the global mind-spheres are that the tremors will linger, perhaps even for years, and that the global impacts will be worse for the planet’s poorest nations.

The first expectation could become a self-fulfilling prophecy and the second is wholly unsurprising. But in any case, notwithstanding the apparent resilience of the capitalist system under pressures of wars and trade conflicts, the results of the Middle East war appear by May 2026 to be coalescing into a global recession that in opinion of many experts is rivaling the Great Recession of 2007-8.

But reliable analysis is nearly impossible to produce. There have simply been too many reversals or inconsistencies in the war actors’ initiatives and thus too many contradictory signals by respective commanders-in-chief. In the economic realm there is too little reliable data, too little time for reliable analyses, and far too much deliberate opacity.

Without all the needed data, the volatility of political minds and associated propaganda – predominantly in form of ethically uncommitted but vague statements with perfect deniability alongside some VERY BIG LIES – converges with the unpredictability of war and the overwhelming complexity of economic relationships into supply chain disturbances, economic uncertainty and market volatility. 

A recession risk is being built from two converging forces: runaway military spending and an AI bubble marked by massive infrastructure investment, workforce upheaval, and valuations not yet backed by real profits. On top of this, trade wars and populist governments redirecting money from social spending into arms races could deepen and spread any downturn, especially in an already fragmented global economy.

The social flip-side of the conflict coin

Ordinary people don’t live in stock markets or tax havens — and for them, the global community created a shared yardstick of progress. First launched at the UN around 2000 as the Millennium Development Goals, and renamed in 2015 the Sustainable Development Goals (SDGs), these frameworks measure how well societies are developing and whether everyday life is becoming more sustainable for the world’s majority.

The SDGs are targeting and measuring sustainability creation. Although the transmission of the SDGs happens largely via measurable economic vectors, the SDGs do not follow the swings of the markets or incorporate the paradigm of creative destructive.

Sustainable development, after generating several decades of encouraging signals, has been hit by a series of regressions. The heaviest impacts of the pandemic of 2020-21, the Ukraine conflict that rages since 2022, the Gaza war and Middle East conflicts of 2023-24, and the ongoing Iran crisis and regional violence can be seen through the SDG lens. And in terms of sustainable development, the impact of the Iran war is the next nail in the coffin of timely realization of SDGs.

This is made crystal clear by studies of the impact of the Iran crisis on first the Gaza strip and secondly African economies. In Palestine, the government’s central bureau of statistics (PCBS) established a directorate of records and statistical monitoring to surveil progress of SDG achievements.

A national review on the implementation of the 2030 SDG agenda was issued in preparation of Palestine’s participation in the UN’s high-level policy forum in 2018. While cautioning that the 2030 agenda slogan to leave no one behind “cannot be realized in a country that the whole world is leaving behind”, the paper reported modest national improvements for several SDGs in the years 2009 to 2017, disclosing that 109 of 244 SDG indicators were being, albeit imperfectly, monitored.

New reports on the situation of all SDGs in the first quarter of 2026 appear unavailable. Yet a 2025 UNDP assessment of Gazan food sustainability in the SDG envelope sees “growing evidence” that reaching the sustainability goals is difficult in circumstances that are “characterized by both unprecedented natural and human-made extraordinary challenges”.

According to the study, 15 SDGs in the social, environmental, and economic sustainability pillars have been damaged across Gaza in the conflicts that started in October of 2023, which contributed to destabilization of neighboring countries and their SDG processes. “The economic collapse in Gaza has far-reaching regional and global implications. Environmental degradation caused by the war, including pollution and soil contamination, does not respect borders and poses significant risks to neighboring regions,” the report elaborates. 

On the local SDG front, sustainability achievements have indeed been impeded. “In terms of SDG country positioning, Lebanon as of 2025 was ranked 134th over 167 countries, but I think that we today honestly rank [lower] than that,” Deenah Fakhoury, executive director of Global Compact Network Lebanon, tells Executive.

She explains that SDG impacts of the Iran conflict on Lebanon and the world are two different things. “If I talk globally, the UN is warning that the current war and systemic shock is reversing development gains. We are in reverse action in terms of poverty, we are in slowdown in terms of economic growth, and we have a widening gap in terms of equality,” she says and adds, “In Lebanon, conflict here is damaging the ecosystem, life on land and life under water, and infrastructure. It also is felt in the pillar addressing social cohesion and governance, which means SDGs 10 and 16. “

In evaluating the SDG dimension of Iran war, it must be remembered that the 2030 agenda was a third millennial milestone and focal point of education, promoted proudly by UNICEF as “the world’s largest lesson” to pupils and student cohorts in thousands of schools around the globe. According to the eponymous UNICEF programs home page, from 2015 8 million children in over 13 countries were made familiar with the 2030 SDG agenda each year.

But broken promises and deferred hopes notoriously destroy trust and can even literally sicken mind and body.  That unfortunate truth has especially been proven when the trust of young minds in their leaders was turned into disappointment over a fake promise or surreal societal goal.  

Young people — the first truly digital generation — are losing faith in global institutions that promised sustainability, democracy, and equality while delivering little. That loss of trust may be the decade’s biggest hidden economic cost: the slow collapse of the United Nations’ credibility and the democratic world order it represents.

Which leaves the central question: Is this just another rough economic cycle? A slow-motion disaster for poorer nations? Or could the collision of so many competing crises finally shake the global system hard enough that a genuinely more sustainable order — environmentally, socially, and economically — actually takes hold?

August 17, 2026 0 comments
0 FacebookTwitterPinterestEmail
Analysis

The violent bending of Lebanon’s economic backbone

by Jamile youssef August 17, 2026
written by Jamile youssef

This analysis was written for a Spring 2026 Special Report on the repercussions of conflict on local economies

Lebanon is a country famously burdened by a culture of corruption, financial collapse, institutional paralysis, and years of imported conflict. But entering 2026, there were tentative signs of stabilization: a modest rebound in tourism, some renewed political momentum, and cautious hopes for a new virtuous cycle in the economy.

The escalation of war in April 2026 between Israel and Hezbollah interrupted this fragile recovery, shifting pressure again to the most immediate dimensions of economic life: energy supply, consumer prices, and environmental conditions. Economic pressures in Lebanon never unfold in isolation. But in the unfolding of two overlapping and interrelated conflicts, the first the was between the US/Israel and Iran, the second between Israel and Hezbollah, three intertwined core pillars of the economy were dislocated – energy, agriculture, and the environment.

Rising fuel costs increase transportation and operating expenses all along the supply chains. The badly insufficient electricity provision forces households and businesses to heavily rely on private generators which depend on imported, highly polluting fuel. Agricultural producers have to cope with a range of higher costs in conjunction with deliberate destruction of lands. Retail prices increase and inflation hits households from the working poor to a nominal middle class that is barely hanging on. Environmental consequences of two consecutive Lebanese wars waged from the air and on the ground are becoming more pronounced.

Lebanon has become adept, in a manner of speaking, at switching from a marginal peace economy with a high rate of informality to a war economy that survives by merit of informality and ingenuity. The result of the concurrent regional and cross-border wars at this time, however, is not simply a war economy in the abstract, but a spiral of daily deteriorating livelihoods. Economic, social, and environmental conditions are being degraded by a series of multi-source shocks, a chain disruption in which each shock reinforces the other.

Conflict is reshaping daily and future life  

Inflation in Lebanon cannot be explained by the current crisis and fuel prices alone. It reflects the interaction of domestic structural weaknesses, global inflationary pressures, and continuous uncertainty. Alissar Nasser, team leader of the Consumer Price Index at the Central Administration of Statistics (CAS), tells Executive that food prices had begun rising already before the regional escalation, driven in part by seasonal demand during Ramadan and Easter.

According to CAS, Lebanon’s Consumer Price Index increased by 6.9 percent between January and March 2026. The sharpest increase was recorded in transportation, which rose by 21.6 percent, reflecting the direct effect of higher fuel costs. Prices for water, electricity, gas, and other fuels increased by 17.6 percent. The index for food and non-alcoholic beverages rose by 8.4 percent. Within food categories, the lowest inflation of 5.1 percent was recorded for bread and cereals, but meat, vegetable, and fruit prices increased by margins of almost 14 to over 16 percent.

Agricultural land under fire

These economic and social pressures are being intensified by conflict damage to the agricultural sector. Southern Lebanon, one of the country’s most important farming regions, has experienced extensive fires, soil degradation, and direct damage to farmland, greenhouses, and irrigation systems. According to the Ministry of Agriculture’s weekly report released on March 27th, 22 percent of the country’s agricultural land has been affected by the bombing, though the report did not specify whether this includes damages accrued since October 2023 or during the current escalation since March 2026. 

Both environmental experts interviewed for this article stress that the March 2026 escalation did not create a new environmental crisis; it added to existing environmental degradation. “We barely got out of the [last] war,” says Christina Abi Haidar, a lawyer who is specialized on energy and governance. “We did not recover, and the March escalation increased the burden.”

Beyond agricultural losses, the new war forces the transformation of entire communities. In places such as Bint Jbeil, Abi Haidar says, “you cannot recognize the village at all.” She explains that some areas in South Lebanon have been damaged to the point that familiar landmarks in several municipalities are no longer recognizable.

For farmers, the consequences are both immediate and long term. In addition to direct damage, many were unable to access their land to harvest crops. Olive growers in particular, lost an important production season. Nadim Farajallah, chief sustainability officer at the Lebanese American University, explains that in orchards the loss extends well beyond one year. “It takes four to five years for a tree to resume its production,” he says.

The use of white phosphorus, documented extensively by human rights and aid groups, experts, and international media, has heightened concern about long-term contamination. Farajallah offers an important distinction: “White phosphorus is not an issue in the soil. It is an issue of burning.” In other words, the main damage comes from the immediate destruction of crops, trees, and vegetation rather than persistent soil toxicity.

The economic implications extend beyond agriculture itself. Damage to agricultural land reduces domestic production, increasing Lebanon’s reliance on imports at a time when shipping, insurance, and transportation costs are also rising, according to the World Bank’s 2026 Lebanon Overview. Lebanon’s Central Administration for Statistics (CAS) recorded a 14.19 percent annual inflation, a 24.81 percent jump in transportation costs and a 20 percent rise in energy costs in March 2026. The result is a reinforcing cycle: environmental damage lowers local output, greater dependence on imports raises costs, and higher prices squeeze both households and farmers. With fewer resources to replant, repair infrastructure, or replace lost assets, the capacity to recover becomes increasingly constrained.

In much wider damage impacts, bombing can destroy wells, pumps, reservoirs, and irrigation pipes, preventing cultivation even after the fighting ends. Greenhouses may need to be rebuilt entirely. Livestock and poultry operations are also highly vulnerable. Dairy cows must be milked daily, and poultry are sensitive to stress. “We only think of crops and trees,” Farajallah says. “But we also have dairy production, meat production, and poultry production.”

Water infrastructure and systemic vulnerability

Water systems are among the most structurally fragile components of Lebanon’s economy, and the current conflict has exposed the extent of that vulnerability. Even before the 2026 escalation, the sector was under strain from decades of underinvestment, weak governance, and the financial collapse.

Farajalla notes that the 2019 economic crisis severely weakened the water sector by cutting the value of revenues and reducing the ability of utilities to cover operating costs. “We had to rely on donors just to keep the sector afloat, barely functional,” he says.

The recent conflict has added direct physical damage to an already weakened system. Oxfam International reports that at least seven critical water facilities, including reservoirs, pumping stations, and distribution networks, were damaged in the early days of the escalation in 2026.

Additionally, the significance of this damage lies in the close link between water and energy. Water systems depend heavily on electricity and fuel to operate pumps and treatment facilities. As a result, disruptions to energy supply can interrupt water access even when infrastructure remains physically intact.

Abi Haidar notes that many solar-powered pumping systems installed in recent years were also damaged, particularly in southern Lebanon. These systems had helped municipalities and farmers reduce dependence on diesel generators. For businesses, especially in agriculture, food processing, and small-scale manufacturing, water insecurity directly affects productivity and cost.

Debris, pollution, and long-term health risks

The accumulation of debris and hazardous waste is another major consequence of the conflict for natural environments and human habitats. Airstrikes and widespread destruction generate large amounts of rubble, including broken concrete, metal, dust, and other materials that must be safely managed.

Farajallah emphasizes that Lebanon is still struggling to manage debris from previous crises. Rubble from the 2020 Beirut port explosion remains stored near Electricité du Liban, underscoring the country’s limited capacity to process large volumes of waste. “The problem of the debris is the immense amount of volume that we have,” he says.

The disruption of waste collection adds another layer of strain. As displaced populations move into host communities, the volume of waste can exceed the capacity of municipal contractors, leading to garbage accumulating in public spaces. At the same time, dust generated by damaged buildings and debris can worsen air quality, increasing health risks, particularly for children and older people.

Abi Haidar warns that these environmental effects may have lasting consequences for public health. Lebanon already faces elevated rates of pollution-related illnesses, including respiratory diseases and certain cancers linked to poor air quality, waste mismanagement, and environmental contamination. Additional pollution from debris, damaged infrastructure, and contamination of soil, water, and air could further increase these risks over time. Even after the fighting ends, the health impacts may persist for years, creating a less visible but potentially significant burden on the country’s recovery.

The fiscal cost of energy disruption

The conflict has also exposed other layers of Lebanon’s energy vulnerability. Abi Haidar distinguishes between other layers of losses.

The first is direct physical damage to substations, transformers, transmission lines, and distribution networks. The World Bank estimated that energy sector damage from the previous war reached approximately 200 million U.S. dollars. Because reconstruction has been limited and some facilities that were repaired have since been damaged again, current losses are likely to be substantially higher.

The second is indirect domestic losses, particularly unpaid electricity bills from households that were displaced or can no longer afford to pay. Abi Haidar estimates that unpaid bills linked to the conflict may have reached between 42 million and 45 million U.S. dollars.

“Lebanon had a bouquet of everything,” Abi Haidar says. The country is absorbing the direct costs of bombing, including the destruction of infrastructure and productive assets, while simultaneously facing the inflationary effects of higher global energy prices.

Who bears the cost?

In legal terms, both experts are clear: responsibility rests with the party causing the damage. In practice, however, compensation remains uncertain, and the economic burden is largely absorbed within Lebanon itself.

“Farmers have been bearing the cost,” says Farajallah. For agricultural producers, losses include destroyed crops, damaged orchards, irrigation systems, and farm infrastructure, as well as years of lost income while productive assets recover. Consumers bear the cost as well through higher food, water, and energy prices. Public institutions face rising reconstruction needs at a time when state resources remain severely constrained.

Reconstruction is likely to depend on a combination of donor financing, public borrowing, and private losses, shifting much of the burden to households and future generations.

Both experts emphasize that systematic documentation is essential. Lebanon should quantify agricultural, environmental, and infrastructure losses and formally pursue reparations. Damage to farmland, water systems, electricity infrastructure, and public health should be documented and submitted through international channels, including the United Nations.

Yet this process remains inadequate. Despite repeated cycles of conflict, Lebanon has not consistently documented losses into effective international claims or compensation. Without rigorous documentation and sustained legal follow-up, environmental and economic losses risk becoming another unrecorded cost of conflict, absorbed domestically and financed through debt, aid, and reduced living standards.

A structural dimension of the crisis

The surge in global oil prices is one of the clearest channels through which the regional conflict is affecting Lebanon. In an economy that depends almost entirely on imported fuel, higher oil prices quickly translate into higher transportation costs, more expensive electricity generation, and rising prices for food and other essential goods. According to CAS data from March 2026, transportation prices rose 25 percent year-on-year in March 2026, while housing, water, electricity, gas and other fuels — the largest category in the CPI basket — rose 20 percent over the same period. This pass-through was direct: fuel accounts for roughly 82 percent of private diesel-generation costs in Lebanon, and the official generator tariff jumped from USD 0.34/kWh in February 2026 to USD 0.45/kWh in March 2026 as diesel prices spiked according to an April 2026 report by Arab Reform Initiative.

These effects are amplified by direct damage to agricultural land, water facilities, and energy infrastructure. Lower domestic production increases reliance on imports, while damaged public services raise operating costs for households, farmers, and businesses.

The burden of these shocks is largely absorbed within Lebanon. Farmers lose productive assets that may take years to restore. Public institutions face growing reconstruction needs with limited resources. Households confront higher costs for food, electricity, water, and transportation, while health risks associated with pollution and environmental contamination may persist long after the fighting ends.

August 17, 2026 0 comments
0 FacebookTwitterPinterestEmail
Comment

The homogenezation trap

by May El Hachem July 8, 2026
written by May El Hachem

In May 2025, three management scholars at MIT’s Sloan School, David Wingate, Barclay Burns, and Jay Barney, published a paper whose title arrived like a cold shower in the middle of the loudest conversation in business: Why AI Will Not Provide Sustainable Competitive Advantage. Their argument was not that AI is overhyped, or that its disruptions are exaggerated. It was something more unsettling: that the race every company in the world is currently running is, structurally, a race to a tie.

I have been thinking about that paper a great deal since because it names something that most AI strategy discourse tends to avoid. I am a Lebanese lawyer working across a region where the pressure to adopt AI is near-total, where the topic permenates boardroom conversations, and where the question of whether to adopt has seemingly been settled in favor of how fast. The MIT Sloan argument shifts the question again. And this time, the shift matters.

The gold rush has a catch

The case for adoption is not in dispute. According to global management consulting firm McKinsey’s 2025 State of AI survey, which drew responses from nearly 2,000 participants across 105 countries, 88 percent of organizations now use AI in at least one business function, up from 78 percent the year before. Research by the London School of Economics and consulting firm Protiviti, published in October 2024 and based on surveys of nearly 3,000 workers, shared their compelling findings that professionals using AI save an average of 7.5 hours per week.

But Wingate, Burns, and Barney identify a structural problem that no amount of enthusiasm about these numbers resolves. Every serious technical advance ultimately becomes equally accessible to every company. Algorithms commoditize and open-source models erode proprietary offerings within months of their release. The MIT Sloan paper’s argument is that talent is plentiful, hardware competition is fierce, and what may be proprietary at time of release becomes table stakes within months.

“Far from being a source of differentiation,” Wingate, Burns, and Barney write, “artificial intelligence will be a source of homogenization.” When everyone runs the same engine, the engine is no longer the race.

The homogenization trap

This is the paradox that most AI strategy fails to confront directly. The universality that makes AI valuable as a category makes it worthless as a differentiator. If your competitor has access to the same models, the same automation capabilities, and the same tools, the advantage does not accumulate to either of you, and your market ranking remains more or less the same.

What rises in value when the tools flatten out? As Harvard Business School’s Institute for Business in Global Society argued in September 2025, AI cannot reliably distinguish good ideas from mediocre ones. It cannot guide long-term business strategy. It cannot replicate the kind of cultural intelligence and contextual judgment that determines whether a decision is right for a specific market, a specific organization, a specific moment in time.

The economists Ajay Agrawal, Joshua Gans, and Avi Goldfarb, writing in IMF Finance & Development in June 2025, argue that AI is fundamentally a prediction machine. It processes inputs and generates probabilistic outputs at extraordinary scale and speed. But between the prediction and the decision sits judgment, the weighing of values, context, uncertainty, and stakes that cannot be reduced to pattern recognition.

As prediction becomes cheap, judgment becomes scarce. The antidote to AI homogenization is not more AI. It is better human thinking.

Automating mediocrity at scale

The problem is that most organizations are doing the opposite.

The RAND Corporation, in a report published in August 2024, found that more than 80 percent of AI projects fail to reach meaningful production deployment, at almost twice the failure rate of conventional IT projects, with the primary cause traced not to technology but to the broken organizational foundations underneath.

Nicholas Carr mapped the deeper cost of this dynamic in The Glass Cage, his 2014 study of automation across aviation, medicine, and financial trading. His argument echoes one prominent concern around AI adaptation, which is that when machines absorb skilled tasks, humans lose the capacity to perform those tasks independently. The pilot who delegates to autopilot loses situational awareness; when the system fails, the judgment needed to recover has already atrophied. The financial analyst who defers to algorithmic outputs loses the interpretive muscle that once gave those outputs meaning. Competence, Carr demonstrates, is something that must be practiced. Practices that go unused erode. And in the current race to automate as much as possible as fast as possible, entire categories of human capability are going unpracticed.

For this region, the stakes are specific. McKinsey’s 2025 research on the GCC shows that close to 90 percent of CEOs report using GenAI, above global averages. Yet only 11 percent are what McKinsey calls “value realizers”: organizations that have genuinely scaled AI and can attribute meaningful earnings to it. The gap between adoption and value creation is a readiness problem, and underneath the readiness problem is a human capital problem that no amount of software procurement resolves.

The cultural intelligence, relational depth, and contextual market knowledge that define competitive advantage in this part of the world cannot be generated by any model. They were built over decades. They are precisely what AI cannot replicate, and precisely what is most at risk in an undiscriminating adoption sprint.

Human-Centered AI Is Strategy, Not Philosophy

The phrase “human-centered AI” has acquired the texture of a values statement, the kind of language that appears in sustainability reports between carbon targets and inclusion metrics. It is neither. It is the only AI strategy that holds up structurally.

The companies that will extract durable advantage from AI are not the ones with the most tools. They are the ones that use AI to do more of what only humans can do, not less. That means fixing the process before automating it. It means investing in the quality of human judgment before deploying the tools that will amplify it. It means treating creative culture, contextual expertise, and institutional knowledge not as costs to be optimized away, but as the moat that gives AI outputs their value in the first place.

AI amplifies whatever it finds. A company with sharp human judgment and strong creative culture, deploying AI, becomes exponentially more capable. A company with broken processes and atrophied thinking, deploying the same tools, becomes exponentially more broken, faster, and at lower cost.

The questions for every business leader in this region is what, exactly, is the AI going to amplify? Is what you have built worth amplifying? And what essential skills might be lost in the process?

July 8, 2026 0 comments
0 FacebookTwitterPinterestEmail
Comment

Institutional Resilience in Lebanon

by Youmna Zod July 6, 2026
written by Youmna Zod

In Lebanon, instability is a daily operating burden that businesses are increasingly forced to absorb on their own. Institutional resilience is vital for small and medium enterprises in this national context, where economic collapse and recurring security crises compound to create cascading failures in electricity, banking, supply chains, and administrative systems. For every single SME, it means deciding which functions cannot be allowed to fail and then rebuilding them at firm level when the wider environment cannot support them reliably.

From my experience in leading corporate strategy, digital transformation and business development,  this usually comes down to a few core continuity points: energy, payments, procurement, documentation, workforce coordination, and client trust. The companies that remain dependable are not simply the ones that work harder. They are the ones that redesign their internal systems so these functions continue to operate despite external breakdowns.

Electricity is the clearest example of this private substitution. Before the recent solar boom, a 2019 IMF country report drawing on World Bank enterprise data found that 97 percent of surveyed businesses in Lebanon reported experiencing electrical outages, while 84 percent said they used private generators, which supplied almost half of their electricity needs. That figure should now be read as a pre-solar baseline rather than a current description of the market. But the management lesson remains the same: firms have had to build parallel energy systems because the public one is not dependable enough.

The response to the collapse of state electricity has been striking. According to the Lebanese Center for Energy Conservation’s 2023 Solar PV Status Report, installed solar PV capacity rose from 92 MWp at the end of 2020 to 1,081 MWp by the end of 2023, with cumulative investment reaching nearly $1.4 billion (LCEC, 2023). During Beirut Energy Week in September 2023, LCEC-linked figures indicated that decentralized solar capacity had already surpassed 1,000 MW and was tracking toward roughly 1,300 MW by year-end. Because EDL’s effective generation capacity had dropped so sharply, that meant installed solar capacity represented more than 40 percent of the country’s available electricity generation capacity at that moment. In the finalized 2023 report, LCEC said solar contributed 15 percent of Lebanon’s actual electricity generation mix for the full year, up from 2.2 percent in 2021.

This matters because solar in Lebanon is not only an energy story. It is an institutional story. It shows what happens when households, businesses, and institutions are forced to replace a missing public function through private coordination, private investment, and private risk-taking.

The same dynamic became visible in finance. Lebanon’s banking collapse is often discussed in terms of savings, currency, and macroeconomic loss. At company level, it also became an operational disruption. When conventional banking channels became unreliable, businesses could no longer treat billing, payment logic, procurement timing, and supplier coordination as back-office routines.

In our corporate security firm, maintaining uninterrupted service required us to rethink those systems quickly. The issue was not simply whether money moved. It was whether service continuity could be preserved while the financial infrastructure itself was failing. In that sense, banking disruption did not only create financial pain. It forced firms to redesign commercial processes in real time.

Data and institutional memory

Another function that becomes more important as public institutions weaken is documentation, specifically the capacity of private sector SMEs to maintain reliable internal records when government systems and public documentation cannot be relied upon. In stable environments, documentation is often treated as administration. In unstable ones, where the state cannot be counted on to maintain records or provide documented proof, it becomes continuity infrastructure. When teams are under strain, sites are harder to access, staff availability shifts, and compliance still has to be maintained, records become part of the operating backbone.

This is one reason I do not see resilience as improvisation alone. Improvisation helps in the moment, but it does not create reliability. Reliability comes from converting lessons into process: traceable records, stored reports, accessible histories, clearer handovers, and systems that do not rely entirely on memory or one individual’s availability.

From my experience, firms that function more reliably under instability tend to rebuild the same six capabilities at company level. They learn to sense faster by tracking market, infrastructure, financial, supplier, and client signals in real time; to decide faster by shortening decision-making chains before problems intensify; and to adapt processes within limits by giving staff enough flexibility to respond without losing accountability. They also learn to protect continuity points, especially billing, procurement, compliance, workforce coordination, and client service; to preserve trust visibly through clearer communication and steadier client support; and, over time, to turn constraints into operating advantages by using crisis-driven adaptations to build leaner and more responsive systems.

What policymakers should note

The lesson for policymakers and lenders is straightforward. If Lebanese SMEs are privately rebuilding continuity in energy, payments, logistics, and compliance, then they are carrying costs that are often invisible in conventional business analysis. Support for SMEs cannot be reduced to finance alone. It has to account for the institutional burden businesses are already absorbing through backup systems, duplicated workflows, added coordination, and self-funded continuity measures.

That is why institutional resilience in Lebanon should not be romanticized. It is expensive, inefficient, and often exhausting to privately reproduce functions that should be publicly reliable. But it is also one of the clearest explanations for why some firms remain dependable while others become fragile. The most resilient Lebanese SMEs are those that can ensure institutional continuity from the inside out.

July 6, 2026 0 comments
0 FacebookTwitterPinterestEmail
Brand Voice

YOU HAVE THE RIGHT TO UNDERSTAND YOUR RIGHTS.

by asklex June 29, 2026
written by asklex

At some point, almost everyone encounters a legal situation. A contract that doesn’t feel right, a dispute with a landlord, a workplace issue, an inheritance that’s become complicated…In those moments, most people do one of three things: they pay for advice they can’t easily afford, they rely on someone who “knows someone,” or they do nothing and hope it goes away.

This is the legal gap. It isn’t a gap in the law itself because legal frameworks exist precisely to protect people, but a gap in access. The legal system was never designed to be navigable without professional help, and professional help was never designed to be affordable or available to everyone.

For too long, legal clarity has functioned as a privilege; something you access based on what you can afford or who you know, not based on what you need.

Artificial intelligence is changing that equation. Not by replacing lawyers, but by doing something the legal system never could on its own: meeting people where they are. Understanding a situation in plain language. Cutting through complexity to show someone what they’re actually dealing with, what their options are, and what their next step should be.

This is the premise behind askLex. Launching in Lebanon on July 4th, askLex is a free app that listens, understands, and builds a path forward: turning what was once an overwhelming, expensive process into something navigable. And when professional legal help is genuinely needed, askLex connects users directly to the right people.

The impact goes beyond convenience. When legal clarity stops being reserved for those who can afford it, something more fundamental shifts: for individuals, for families, for communities. People who understand their rights are better positioned to protect them. 

askLex launches July 4th in Lebanon. Free, accessible, and built for everyone.

BULLETIN — Executive Bulletin

(Beirut, Lebanon) — June 2026 — askLex, a free AI-powered legal app, is officially launching in Lebanon, giving users access to legal guidance without the barrier of cost for the first time.

Designed around artificial intelligence that understands legal situations in plain language, askLex helps users make sense of what they’re facing, identifies a clear path forward, and connects them to the right legal professionals when needed, all at no cost.

The app addresses a gap that affects the majority: most people who encounter legal situations have no accessible, affordable first point of guidance. askLex was built to be that first step.

Lebanon marks askLex’s first market as the company begins its regional expansion. askLex will be available at asklex.app as of July 4th, join the waitlist now at asklex.app.

June 29, 2026 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • 2
  • 3
  • …
  • 708

Brand Voice

  • YOU HAVE THE RIGHT TO UNDERSTAND YOUR RIGHTS.

    June 29, 2026

Stay Informed

Facebook Twitter Instagram Linkedin Youtube

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE