• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Economics & Policy

Clearing the smoke

by Executive Staff December 3, 2011
written by Executive Staff

Little has improved in Lebanon since Executive’s last year-end report on the environment in December 2010. Air quality continues to deteriorate, urbanization advances almost totally unchecked and water resources remain poorly managed; and these are only a few of the steadily growing ecological problems the country faces.

For years, one of the major problems present in addressing Lebanon’s many environmental issues has been the near total lack of reliable and current data.

It has been more than a decade since the last comprehensive report on the environment here was released, so perhaps the most substantial development of 2011 was not an innovative field project or the passing of new environmental regulations, but rather the publication of a 355-page report titled “State and Trends of the Lebanese Environment 2010”.

The report, released in July by the Lebanese development firm ECODIT, was compiled with the assistance of the Ministry of Environment (MoE) and the United Nations Development Program (UNDP). It includes data culled from the Central Administration of Statistics, local and international non-governmental organizations, as well as various news reports. Together, this will add to the ability to clearly analyze the successes, failures and neglected areas of the environment in Lebanon. It can also serve as a platform from which to promote the adoption of new environmental laws.

Environmental governance

Any substantial changes to existing environmental laws in Lebanon must ultimately gain approval from the top — no easy task considering the epic bureaucratic hurdles of government. Najib Saab, secretary general of the Arab Forum for Environment and Development (AFED), says Lebanon’s biggest environmental issues, “such as air pollution, land and water degradation and coastal zones’ deterioration, can be easily solved in the presence of adequate governance, professionalism and vision.” He adds that “environmental matters are managed by amateurs.”

And not only are government agencies highly inefficient — in the case of the MoE at least, they are also understaffed. More than two years ago, the MoE was given approval to hire an additional 23 staff members for various positions, and salaries for an additional 20 contracted technicians were to be paid in part by a grant from the Italian foreign ministry’s local outreach arm, Italian Cooperation for Development in Lebanon. With government bureaucracy a chronic problem in Lebanon, on the surface, adding more staff to a ministry seems like an unwise decision. But adding analysts, technicians and other specialists to a long neglected ministry could be of great benefit in the future. To date, most of these positions have not been filled. [See Q&A with Minister of Environment Nazem Khoury on page 216]

Another urgent problem is the lack of an environmental law enforcement body. Without one, the task of enforcing regulations, cracking down on violations and monitoring and carrying out court rulings falls on municipal police departments and the Internal Security Forces — both of which have other priorities. The addition of even a modest environmental police force in Lebanon could begin a process of changing people’s attitudes toward the environment. “If the government would enforce laws, say, against throwing trash on the side of the road, I think Lebanese people would stop doing this because they don’t want to pay fines,” says Capricia Chabarekh, an environmental and air quality specialist at ECODIT.

The MoE has sought assistance from a broad range of NGOs in Lebanon, as Rayan Makaram, Greenpeace Lebanon campaigner, says: “When the new minister of environment was brought in this summer, right away he asked for feedback from civil society, NGOs and the media. This push toward greater cooperation with the government was a good success. But, it’s just a first step.”

Shortsighted land management

According to Rita Stephan, environmental and land management specialist at ECODIT, one of Lebanon’s most pressing issues is the poor management of its land resources. Given the country’s size, having responsible policies that curb urbanization and regulate land use is all the more urgent.

“We don’t have land for public gardens; we only have land to build towers and big commercial centers,” she says. “We are destroying our land heritage.”

An October 2011 report from the AFED, ‘Arab Environment: Green Economy,’ offers a blunt assessment of the region’s overall disregard for environmental sustainability: “Arab economies continue to unsustainably deplete renewable natural resources, motivated by short-term profits, causing environmental impoverishment of scarce land and water resources while discounting the value of these resources of future generations.” While meant to address the region as a whole, this statement could be used to describe practices in Lebanon alone, too.

And the figures are staggering: “The average annual cost of environmental degradation in Arab countries has been estimated to be $95 billion, equivalent to 5 percent of their combined GDP in 2010,” the AFED report adds. The last time a thorough cost analysis of environmental degradation in Lebanon was performed — 12 years ago by the World Bank — estimates put the cost at roughly $500 million, or 3.4 percent of Lebanon’s GDP.

Seeing potential in solid waste

According to data from the MoE, solid waste management, or the lack thereof, is one of the fastest growing problems for Lebanon. One possible solution, supported by both the UNDP and ECODIT, is the construction of four waste-to-energy (WTE) incinerators in Lebanon. ECODIT’s Stephan points out the positives — increased energy production for Lebanon’s ailing power grid and less solid waste piling up in landfills, among others — but acknowledges some activists and NGOs are against it. Building and maintaining incinerators “is costly and they need to strictly regulate it,” she says. Among the problems is to dispose of the ash produced from burning waste, which can contain highly toxic chemicals and heavy metals that are dangerous to water supplies.

Beginning in 2006, the government was expected to begin the construction of treatment plants and landfills as part of its WTE “master plan”, but it has so far failed to act. And it is not just a matter of building WTE facilities, it is about changing people’s habits, as Stephan explains: “You have to sort the waste well before incinerating it. So we need to reorganize our waste. We should be separating it in our homes.” She adds that “there is no public awareness for separating waste, and this is a major problem in Lebanon.”

Government stalling will cost Lebanon dearly in the near future. According to the ECODIT report, “waste generation in Lebanon is expected to increase by 1.65 percent annually to reach 2.3 million tons by 2030, notwithstanding potential waste recovery from sorting and composting facilities.” It adds, “Waste disposal is particularly difficult in Lebanon because of its rugged terrain and limited surface area.”

According to Saab of AFED, “Waste-to-energy is just one possible component in an integrated solution to the waste management challenge. Until now, the principles of reduction and re-use are totally absent. It’s as if consumers are encouraged to generate more waste. In this context, waste-to-energy is one option. But what is being considered by the ministry is restricted to generating energy through incineration. When up to 80 percent of municipal solid waste is composed of organic material like in Lebanon, many doubts are raised on the efficiency of combustion, how much energy it produces and how many pollutants. High content of wet organic material is not good for burning, will need addition of fuel to blaze and generates minimal energy.”

“We haven’t seen a study of an option comprising generating energy from organic waste, utilizing digestion to obtain methane. This might be the better option in the Lebanese case. Environmental affairs, including waste, are run by pretentious amateurs or shrewd salesmen,” Saab says.

The issue of waste-to-energy incinerators is highly divisive, with NGOs and activists who are against incinerators pitted against the Ministry of Environment and UNDP who support their construction. According to Makaram of Greenpeace Lebanon, “Our stance is that incinerators are still incinerators — they encourage the production of waste rather than the reduction of waste. Around the world, countries are shutting these incinerators down, and now we want to build them in Lebanon? The global trend is to close down. If we build these in Lebanon, we’re going against science and global trends.”

Additionally, the AFED report estimates that “greening the waste management sector would save Arab countries $5.7 billion annually.”

On the horizon

While there were significant steps taken to improve the environment in 2011 (such as the passing of the National Water Sector Strategy in April), tangible improvements have yet to be seen.

With assistance from the UNDP and NGOs, the government has several major environmental projects on schedule to begin in 2012. Jihan Seoud, environment and energy program associate for UNDP in Lebanon, says that a program with the ministry that will work toward reducing ozone-depleting substances will start next year.

The water sector strategy will be looking at options for renewable sources of water for Lebanon, as well as studying the effects of climate change on supply. “It’s quite comprehensive,” Seoud says. “Of course, implementing the strategy and finding the funding to do the work required is another story.”

The World Bank, in its June 2011 Country Environmental Analysis states that Lebanon is set to meet five out of eight Millennium Development Goals (MDG) set out by the United Nations by 2015. Among the three that are predicted to fall short is the reversal of environmental degradation, or as the report calls it, the Ensure Environmental Sustainability MDG.

So, while there is always more that can be done to improve environmental conditions across Lebanon, 2011 could be looked back on as a turning point in the understanding of the most crucial issues. Now it is up to the policymakers to act.

December 3, 2011 0 comments
0 FacebookTwitterPinterestEmail
Finance

Performance of Lebanese banks in 2011

by Maya Sioufi December 3, 2011
written by Maya Sioufi

Lebanese banks had to prove their resilience once again in 2011, though instead of dodging a global financial crisis, this time around they had to navigate a five-month government stalemate, the undoing of Lebanese Canadian Bank (LCB) and the continuing Arab revolutions.

For the first nine months of 2011, assets, deposits and profits all grew, albeit at much lower rates than those enjoyed in previous years. The total assets of the Lebanese alpha banks — the 12 banks with deposits in excess of $2 billion — stood at $143 billion, a 6 percent year-to-date growth, but a slowdown on the 11 percent growth in 2010 and 22 percent growth in 2009.

In February, the United States Department of the Treasury designated LCB as a “financial institution of prime money laundering concern,” accusing the bank of laundering hundreds of millions of dollars for a Lebanese-Colombian drug baron with links to Hezbollah, which Washington has designated as a terrorist group.

LCB was eventually bought out by Société Générale de Banque au Liban (SGBL) for an undisclosed amount, although banking sources in Lebanon put the figure at around $500 million.

The ordeal shook Lebanon’s banking sector, but several leading industry officials with whom Executive spoke said they were optimistic that there would be no recurrence of incidents of this sort.

“Definitely LCB was a big event, which was a concern for the market, but it was handled and now hopefully it is behind us,” says Walid Raphael, general manager of Banque Libano-Française (BLF).

Indeed, the general consensus is that the LCB debacle has nurtured, by necessity, a new culture of accountability on the road to transparency. “I think it was an individual case, and I think most banks have learnt a lesson,” says Jean Riachi, chairman of FFA Private Bank. According to Freddie Baz, chief financial officer at Bank Audi, “Important banks in Lebanon know their responsibilities and duties in terms of compliance.”

“LCB is an event that triggered some kind of extra focus,” he adds. “These crises can happen and they can quickly be resolved without collateral damage.”

But the Lebanese banking sector remains on the fence with regards to Syria, where the outcome of the uprising is still far from certain. While most in the industry say the impact on Lebanese banks has been contained thus far, they remain concerned going into 2012.

The US is also monitoring the Lebanese banking sector’s cooperation with Syria, and its official warning came during the visit in November of Daniel Glaser, the treasury department’s assistant secretary focused on illicit financing. He cautioned the Lebanese monetary authorities that banks in Lebanon were at risk of being blacklisted if they helped Syria dodge international sanctions.

“I think in 2012 the predominant local theme will be the Syrian situation. The impact has been contained so far,” says Khaled Zeidan, general manager at MedSecurities. 

“The issue is you never know what might happen tomorrow in terms of sanctions,” BLF’s Raphael says with regards to Syria.

According to Baz, Bank Audi’s assets in Syria shrunk by one third due to withdrawals of deposits but he casts doubt on an assertion made in a November Financial Times article stating that a continuous flow of Syrian money is being smuggled into Lebanon. “Audi is the largest bank in Lebanon, with the largest deposit base, and we have not seen any material deposit from Syria over the last nine months,” he explains.

But aware of the potential for further sanctions, banks claim they are taking measures to protect themselves. Francois Pascal de Maricourt, chief executive officer of HSBC Lebanon, said: “When we can not have a proper assessment of the origin of the funds and when [they] could put the bank at risk, we have to turn down some business and I believe most of the banks in Lebanon are very careful and are doing the same.”

In fact, deposits, which stood at $118 billion at the end of September 2011, only grew by 5 percent year-to-date, compared to the 2010 rate of 12 percent and the 2009 rate of 24 percent. Profits grew by a marginal 1 percent to reach $1.2 billion, which fades in comparison to the staggering 25 percent increase in profits in 2010 and 18 percent in 2009.

The three largest Lebanese banks with branches in Syria — Banque BEMO Saudi Fransi, Bank of Syria and Overseas (member of BLOM Bank) and Bank Audi Syria — saw their assets fall by an average of 24 percent and deposits drop an average of 29 percent through the first three quarters of 2011.

Beyond the region

Looking beyond Syria and other regional turmoil, the European sovereign debt crisis has dominated headlines throughout the second half of the year and severely shaken the global markets. However, its impact on the Lebanese banking sector has been minimal. Banque du Liban (BDL), Lebanon’s central bank, has strict regulations on local banks which, “In normal times restrict our capacity to originate profitability but in difficult times act as important buffers,” says Bank Audi’s Baz. For example, banks are forbidden from investing more than 50 percent of their equity abroad and require that only investment grade fixed income be held in banks’ portfolios.

“Banks are very conservative when it comes to investing customer deposits. We do not speculate… so we didn’t see a major impact from the European debt crisis,” said Alain Wanna, deputy general manager and head of Group Financial Markets at Byblos Bank. In addition to imposing stringent restrictions to minimize volatility, BDL maintains stability through its stash of foreign currency reserves, $31.3 billion as of the end of July 2011, and its gold reserves, which reached $17 billion as of mid September, the second largest in the Middle East and North Africa region after Saudi Arabia. BDL governor Riad Salameh, whose term was renewed for a fourth time in July, has said he intends to keep the gold reserves to protect the economy from regional unrest.

“Lebanon is immune to what is happening in Syria and worldwide because of the model we have, which is a highly liquid, prudent approach to credit and low leverage,” said Salameh at a September meeting of Arab central bank governors in Doha, Qatar. Loans provided by banks in Lebanon still increased despite the challenges faced in 2011. In fact, lending at alpha banks increased by 13 percent year to date, a slowdown relative to the 25 percent increase in 2010 and 16 percent in 2009, but still a strong rate given the obstacles encountered this year. In spite of the continuous increase in lending, a survey completed in July by The Banker magazine revealed that Lebanese banks had the lowest loan to deposit ratio among the 1,000 commercial banks analyzed globally.  “Who would you lend [to] in the absence of growth in the economy and a real government program to promote entrepreneurship?” asks Zeidan.

According to Saad Azhari, chairman of BLOM Bank, the figure that should be looked at is loans to gross domestic product: “Usually in underdeveloped countries, the ratio of loans to gross domestic product varies from 40 to 60 percent. In developed countries, it is between 80 and 90 percent.” Lebanon’s loan-to-GDP ratio is just over 90 percent.  Furthermore, Byblos’ Wanna argues, loans to the public sector should be factored in to the loans-to-deposit ratio, noting that, “all banks have large portfolios on the government, whether in local or foreign currency.”  According to the most recent report by the Association of Banks in Lebanon, claims by commercial banks on the public sector as of the end of August stood at $28 billion and claims to the private sector at $39 billion.

Of potential consequence to deposit flows is a measure within the pending draft budget proposed by Finance Minister Mohamad Safadi in October, which calls for a raise in the tax rate from 5 percent to 8 percent on the interest of deposits. The probable impact is not clear but it has sparked heated debate within the banking sector.

FFA’s Riachi is not concerned about the proposal. “I don't think it will affect flows, and I think people will think in terms of net interest and see where their advantage is relative to other banks.” 

But some are worried about the measure’s timing. “We are [already] witnessing lower growth of deposits and lower capital inflows. It is not a disaster but it is not the right time,” says Azhari.

“I think fresh capital will remain hesitant for some time. You don't introduce something like this during difficult times, particularly when there appears to be many challenges ahead, and when investor and consumer confidence are in a period of retracement globally,” says Zeidan.

The road ahead in 2012

The International Monetary fund has projected 2011 growth in Lebanon to be 1.5 percent. The prospects for limited growth can be further reflected through low consumer confidence. Household spending accounts for 79 percent of Lebanon’s GDP, according to Byblos Bank, and a recent consumer confidence survey undertaken by Byblos and Olayan School of Business reveals that consumer confidence has been consistently falling since 2007 and reached a low in August 2011. 

Looking towards 2012, and with excess liquidity sitting idle on banks’ balance sheets, the banking sector is hungry for growth opportunities. The prospects of deploying further capital in Lebanon seem poor, as expectations for 2012’s GDP are dim. The IMF is forecasting a pick-up to 3.5 percent but banking experts are concerned as many obstacles still lay ahead, namely political uncertainties such as disputes over STL funding, approving the draft budget and unresolved turmoil in Syria. 

“The real issue for the banks will be how to continue on growing after the exceptional period they have been enjoying for the past years. Further expansion in other markets may be one of the solutions to be explored,” said Zeidan. Case in point: Bank Audi’s new license to operate in Turkey. According to Baz, it is the first bank in 14 years to acquire a banking license in Turkey.

Despite riding the challenges of 2011 relatively unscathed, it is critical for the banking sector in Lebanon, which still sits on big piles of cash, to hunt for future growth opportunities — a precarious task in an environment of political instability both locally and regionally. 

December 3, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Investment guide MENA stock tips

by Executive Editors November 25, 2011
written by Executive Editors

Despite the release of third-quarter corporate earnings last month, the markets remained fixated on macroeconomic news coming out of Europe. With the European sovereign debt crisis still unresolved, the markets remained jittery with investors sitting on the sidelines. For recommendations on where to invest in such volatile markets,

Executive spoke to Georges Abboud, head of private banking at BLOM Bank, Nadim Kabbara, head of research at FFA Private Bank and Haitham Arabi, chief executive of Gulfmena Investments.

Georges Abboud

Bullish or bearish?

According to Abboud, most fund managers are sitting on a lot of cash at the moment as, at least in Europe and the United States, markets seem to be heading back into recession. “You can start building some positions now but you need to be careful,” says Abboud. He recommends investing in companies with solid cash flows, as Warren Buffett did when his investment vehicle, Berkshire Hathaway, acquired Burlington Northern Santa Fe in November 2009. “Buffett is intelligent, he saw what was coming, so he bought a company with secure cash flows for the long term.”

Favorite asset classes?

“Now is not the easiest time to ask me where to put my money,” admits Abboud, though he still recommends investing in companies with high dividend yields, low price-to-earnings (P/E) ratios and a vision for growth for the next five years. He believes that the high rates on deposits in Lebanon allow him to buy time and identify stocks to invest in. He would not invest in gold as it has “no transparency, we don’t know what we are buying, we don’t know who the market players are, we don’t know what the leverage is and the speculators are everywhere.”

Thoughts on the Middle East and North Africa, Lebanon and top picks?

Abboud would invest in the MENA region as well as the Lebanese market. His two favorite countries are Saudi Arabia, which has deep pockets and is diversifying away from oil through large infrastructure projects, and Qatar, which has strong development prospects, abundant gas and solid dividend yields. His top pick in the MENA region is Orascom Telecom, but he warns that it is a risky trade. Being a telecommunications company, it is defensive but it carries political risk. As for Lebanon, he does not believe Solidere is expensive but as there is no visibility within the current environment he prefers the local banks, which are cheap, diversified in terms of activities and offer solid dividend yields.

Other interesting ideas outside the MENA region?

 1) Indian government bonds —current yield is around 8 to 9 percent with potential currency appreciation, as he expects India to continue enjoying solid gross domestic product growth. 2) General Motors — recently unseated Toyota as the world’s number one automaker, maybe the most compelling turnaround story in this sector. 3) Eurotunnel Group — operator of the Channel Tunnel between Britain and France. It is now profitable (started paying dividends two years ago) and should benefit from a significant cash flow boost through 2014.

Nadim Kabbara

Bullish or bearish?

 Kabbara is cautious but optimistic. He is concerned by the recent reports coming out of the US, Europe and Asia which show that the global economy is slowing. He is also concerned that we have not yet seen companies materially increase their revenues.

Favorite asset classes?

Kabbara highlights the disconnect between dividend yields on equities and coupons on 10-year treasuries. He believes that “Once we move out of this fear situation, there will be a return to fundamentals,” and investors will start buying equities again. He recommends owning stocks in defensive sectors — such as telecommunication, utilities and staples — but says “If you think we are going to go back into recession, then invest in fixed income and hold cash instead.”

Thoughts on the MENA, Lebanon and top picks?

 According to Kabbara, MENA markets are moving in the right direction but one must be careful when looking at individual names, “as there remains a lack of corporate governance, transparency and regulatory apparatus.” He likes Saudi Arabia, Qatar and the United Arab Emirates. For Saudi Arabia, it is because of increasing investment in the social framework of the country. As for Qatar and the UAE, they are sheltered from the regional turmoil, are increasing infrastructure spending and might be upgraded to MSCI emerging market status from their current frontier-market ranking. Mobily, telecom operator in Saudi Arabia, and Industries Qatar, producer of petrochemicals, steel and fertilizers, are Kabbara’s top picks in the MENA. BLOM Bank is his top pick in Lebanon due to what he calls their risk averse culture, solid operating metrics and capacity for growth. He would remain cautious this year as local banks have, prudently so, put growth projects on hold due to the turmoil in some parts of the MENA.

Top pick globally?

Barrick Gold, the world’s largest gold producer, as Kabbara believes investors have not paid enough attention to gold miners as compared to the physical (gold).

Haitham Arabi

Bullish or bearish?

Arabi is slightly bearish in the short term as “the European crisis is not entirely over and the Eurozone’s GDP is around 27 percent of the world economy, the numbers in the US are looking anaemic and we keep hearing that China’s figures are exaggerated, and that we might see a hard landing. All of which clearly indicate a slowing global economy.” Arabi, however, recommends being selective and gradually building positions on valuation grounds.

Thoughts on the MENA and top picks?

Arabi is cautiously optimistic about the region as, “from a markets perspective, Middle Eastern equity markets have stronger embedded fundamentals.” However, he is concerned that the global macro-environment will impact investor sentiment in the MENA markets. He believes that “in general, it’s time for stock picking, with a 6 to 12-month horizon before markets start to perform again.” Arabi likes Saudi Arabia and Qatar, which are in an expansionary fiscal policy mode. On Saudi Arabia, he adds, “it has around $21 trillion of oil reserves and its total debt to GDP ratio is only about 10 percent while some countries now have debt to GDP ratios in the region of 160 percent to 170 percent, so if anything Saudi is a great hedge for investors if they can read its fundamentals.” As for stock picks, Arabi likes Saudi Basic Industries Corporation as he believes “it is way undervalued”, trading at a P/E ratio of 8.5 times earnings for the first time in several years compared to a usual ratio of 18. It is one of his largest holdings. He also recommends the banking sector in Saudi Arabia and Qatar. In Saudi Arabia, he recommends Rajhi Bank, Riyadh Bank and Saudi British Bank. In Qatar, he likes Qatar National Bank, Commercial Bank of Qatar and Doha Bank.

November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
Economics & Policy

For your information

by Executive Editors November 25, 2011
written by Executive Editors

Syria stutters

As Syria comes under further strain as a result of the ongoing uprising and government crackdown, a series of announcements last month reflected the effects on the country’s economy. In an interview with Bloomberg in late October, Adib Mayaleh, the governor of Syria’s central bank, said the country had spent $3 billion of a $5 billion emergency fund since the start of the uprising in March in order to defend its currency from devaluation and to finance trade. The fund’s existence was revealed in August when Mayaleh announced that $2 billion had already been spent. Mayaleh also noted that foreign currency reserves held by the central bank amount to around $18 billion.  European Union sanctions on oil imports from Syria are scheduled to start this month and are expected to deprive the government of an essential foreign currency source, accounting for 25 percent of total annual revenue. Last month Mayaleh also hinted the country may transition away from the euro towards the Russian ruble if the EU bans the country from dealing in their currency. “In the near future we will agree on parameters for switching to close cooperation with Russian banks and using the ruble for international settlements,” he told Bloomberg.  This year Syria’s economy is expected to contract by 2 percent, according to the International Monetary Fund. Other predictions are even worse for the Levantine state, with the Institute of International Finance positing a 3 percent decline. Syria’s finance minister announced in September the country was expecting gross domestic product growth to slow to around 1 percent this year from 5.5 percent in 2010. [See Dithering in Damascus]

Draft budget released

Last month Lebanon’s finance ministry proposed its draft budget for the year 2012, in accordance with the constitutional deadline for doing so. The budget proposed a series of new taxes including an increase in value added tax (VAT) from 10 percent to 12 percent, while removing VAT refunds on a series of fixed assets used to perform activities such as educational services, activities of non-profit organizations and manufacturing of books, newspapers and magazines. Last month Neemat Frem, president of the Association of Lebanese Industrialists, told Executive that industries have not been receiving their refunds from the VAT administration for over 18 months. “They are borrowing from the private sector without asking us, by force,” he said. The increase in VAT is expected to rake in around $262 million in 2012, according to the draft budget. However, last month Finance Minister Mohamad Safadi told a local radio station that the revenues from the VAT increase would  total $364 million. A 3 percent tax on sales of real estate was also proposed in anticipation of a tax on real estate profits by 2013. The budget also proposed raising the tax on gasoline by LL2,000 ($1.32) per jerry can (1 jerry can = 20 liters) after it was reduced by LL5,000 ($3.25) earlier this year. The budget also proposes a tax on the thorny issue of illegal privately owned maritime properties built on public land, without specifying the amount. The budget predicted real gross domestic product growth in 2012 at 4 percent with inflation expected to hit 5 percent. The total deficit was estimated to reach $4.1 billion, or 29.7 percent of total expenditure. Total debt servicing was estimated to come in at $3.86 billion, an increase of around $24 million on 2010. Other items proposed included exemptions from some fees for non-polluting vehicles and reducing late fines imposed on municipal fees by 70 percent for years prior to 2009. The budget did not account for the increase in minimum wage, decided upon by the cabinet last month, which Safadi stated would cost the government at least $700 million. The budget will have to be approved by cabinet and then sent to parliament to be debated before it is passed into law. Lebanon has been without a budget since 2005.

Lebanon gets thumbs up and down

A series of global economic rankings released last month provided a mixed outlook for Lebanon’s relative position in the region and globally. The World Bank/International Finance Corporation’s “Doing Business Report 2012”, released last month, ranked Lebanon in 104th place amongst the 183 countries surveyed, a drop of one place in the global rankings. The report is compiled according to a composite index of 10 sub-indices including availability of electricity, registering property, paying taxes and enforcing contracts, all of which are major problem areas in Lebanon. The country fared worse than the previous year in terms of getting credit, protecting investors and starting a business. Resolving insolvency was deemed to take around four years and 22 percent of a debtor’s total estate value on average, compared to 3.5 years and 14 percent in the region respectively.  Balancing this grim assessment was the right-wing Fraser Institute, based in Canada, which measures competitiveness and government intervention in global economies and praised Lebanon’s economic freedom, ranking the country second amongst 16 countries in the region last year, the same position as in 2009. The index measures five broad factors of economic freedom and 18 variables.

FDI down

Lebanon is experiencing a downturn in foreign direct investment (FDI) and will continue to do so for the rest of this year, in line with the regional situation brought on by this year’s uprisings across the Middle East. According to the Kuwait-based Arab Investment and Export Credit Guarantee Corporation (AIECGC), total FDI in Lebanon will fall by 39.5 percent this year, from $5 billion in 2010 to $3 billion. Thirteen of the 21 Arab countries will experience a downturn this year, according to the organization, with the Arab world tipped to experience an FDI contraction of 17 percent in 2011 to $55.1 billion. Countries which have recently experienced uprisings were particularly affected by FDI contraction, with Egypt expected to see a 92 percent slide to just $500 million this year. Tunisia is expected to receive 21 percent less FDI year-on-year in 2011, Syria’s figure will fall by 65 percent and Libya’s is expected to see an 87 percent plummet. A total of seven Arab countries were tipped to see growth in FDI, including Saudi Arabia with $29 billion (up from $28 billion in 2010) and Iraq, which should see investment inflows of $3.5 billion this year according to the AIECGC. 

3G prices and legal problems

Last month Telecommunications Minister Nicolas Sehnaoui revealed the pricing structure for Third Generation telecommunication services (3G), tipped to be launched in February. Users will be charged $19 dollars by the ministry for every 500 megabits (Mb) of data they use over the service. Mobile operator Alfa also released their pricing scheme for the service last month saying that the service will be introduced in the ”coming few months”.  The ministry is still embroiled in a court case at the Shura council, Lebanon’s highest court, with the private data service provider Cedarcom over licenses to operate the service. The council ordered the ministry to halt execution of the 3G project on September 15 for one month pending the submission of a request for information by the court. Sources close to the proceedings told Executive that the government had submitted the requested documents, which stated that the mobile operators do not need a license because they are government-owned. When it came to pricing the service, which for public companies would require a cabinet decision, the sources said the ministry intended to treat the mobile operators as commercial entities able to set their own prices.

Hunt again for energy

The cabinet seemed intent to restart on the road to hydrocarbon wealth last month as it prepared for a proposed bidding round at the start of 2012. Last month the cabinet authorized the launch of a tender process to survey onshore hydrocarbon prospects. It also recommended a new draft law to regulate onshore oil and gas exploration similar to the one passed in August covering offshore exploration. The energy ministry also revealed that it has launched a tender process to reassess the seven existing onshore wells drilled between the 1930s and 1960s.

November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
Real estate

For your information

by Executive Editors November 25, 2011
written by Executive Editors

Property sales taxed

The Lebanese government intends to introduce a 3 percent capital gains tax on real estate sales. The proposals come as part of the Ministry of Finance’s efforts to raise government revenues and increase next year’s expenditure by 13 percent, as revealed in the draft budget on October 4. In an interview in mid October, Finance Minister Mohammad Safadi said that the real estate tax, in principle, is acceptable as long as it is below 15 percent. In June 2010, under former Minister of Finance Raya al-Hassan, a draft budget proposed a hike on property registration fees from 5 percent to 7 percent on real estate valued over $500,000 as an alternative to a tax on real estate sales. It was not implemented before the collapse of the government in January 2011.

10 new levels of luxury

A Saudi Arabian firm, Al Shegrey Group KAS Investment, has opened the doors to its newly completed boutique hotel in the Beirut Central District, according to the group’s October 3 press release. Le Dix Hotel, named after the 10 suites which each occupy their own floor, was built at a cost of $25 million, and includes luxury amenities such as private butler service and limousine transport to and from the airport. Arguably built at the highest cost per room key for a hotel in Lebanon, the large suites include two or three bedrooms, kitchen and balcony with an unblocked sea view. Chief Operating Officer of the firm’s hospitality division, Abdulkader A. Hankir said in the press release,”We invite presidents, ministers, ambassadors and businessmen from all over the world to visit Le Dix and have a look at one of the most luxurious hotels in the Arabic region.”

Summerland’s back

The Summerland Village – Residential Apartments was launched October 20, as part of the mixed-use Summerland Hotel & Resorts Kempinski development in Ramlet al Baida, Beirut. Kempinski is the hotel operator, while the developer is London-based Sanbar Development Corporation, the architects are Samir Khairallah & Partners, and the main contractor is Gruppo Rizzani de Eccher. Set to open its doors in spring of 2013, Summerland Hotel will encompass 22,000 square meters of private land with 5000 square meters of private beach, a village composed of 73 residential apartments and a 60-boat-capacity marina. The original Summerland Hotel, which closed in 2001, was created by Société Générale d’Entreprises Touristiques SAL in 1967.

Saudi, king of construction in 2011

Saudi Arabia is dominating the Middle East and North Africa (MENA) construction market this year, having amassed $17 billion worth of new contracts in the first nine months of the year, a 152 percent increase from the same period last year, according to a Bank of America Merrill Lynch Emerging Markets report released October 20. The United Arab Emirates, meanwhile, experienced the steepest fall in new contracts for the same period, down 55 percent compared to the same period last year. For the whole MENA new contracts are up 19 percent year-on-year, but third quarter results were disappointing as contract awards were down 18 percent to $17.2 billion for the quarter. The report pointed out that major UAE construction firms like Drake & Scull International and Arabtec had succeeded in diversifying away from UAE markets, but that Arabtec’s “construction margins are weakening due to low contribution from high-margin projects reaching the end of their cycle and mobilization delays.”

Hilton to manage Habtoor

Al Habtoor Group, the Dubai-based construction giant, announced on October 17 that Hilton Worldwide will take over the management of the group’s two hotels in Lebanon.  The handover of the running of the Habtoor Grand and the Metropolitan Palace will be completed in early 2012. Although a Hilton Hotel in Beirut Central District has been ready for visitors for more than a year it is awaiting the necessary permits to open.  The deals between Hilton’s chief executive officer Christopher Nassetta and Habtoor’s chairman and founder Khalaf al-Habtoor were signed at a media conference in Dubai, where they also revealed that Habtoor’s upcoming 324-room hotel on Palm Jumeirah would be run by Hilton under their luxury Waldorf Astoria brand when complete in 2013. It will be the second Waldorf in the United Arab Emirates after the Ras Al Khaimah property is complete in 2012. Habtoor’s remaining four hotels in Dubai will remain under in-house management, but both speakers said they hope to conclude more contracts together in the future. “We have experience in running our own hotels and we did a great job ourselves, but now we thought it is the right time to hand over this new project to the people who are professional, who have more experience than us, who can provide worldwide experience and also to promote our property,” said Khalaf al-Habtoor.

Cement industry’s slower build

Cement deliveries in Lebanon reached 3.7 million tons in the first eight months of 2011, showing a 4.8 percent increase compared to the same period last year, according to Lebanon’s central bank. However, this growth is more modest than the 5.5 percent growth during that period in 2010, and the whopping 20.5 percent growth in that period of 2009. In August, cement deliveries reached 451,000 tons, indicating a year-on-year growth of 6.2 percent, according to Bank Audi. As for the major players in the local industry, Holcim Liban declared net profits of $19.9 million in the first half of 2011 versus $18 million for the first half of 2010, according to a Byblos Bank report. Net sales were at $97.1 million for the first half of 2011 compared with $92.7 million for the first half of 2010. Société Libanaise des Ciments Blancs recorded net profits amounting to $1.4 million for the first six months of 2011 versus $1.5 million in the first half of 2010. Sales revenues were $6.9 million in the first half of 2011 compared to $7.5 million for the same period in 2010. These figures indicate that after a slightly slower start this year compared to 2010 the rate on construction is finally picking up to its 2010 autumnal levels.

November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Lebanese capital markets

by Executive Editors November 25, 2011
written by Executive Editors

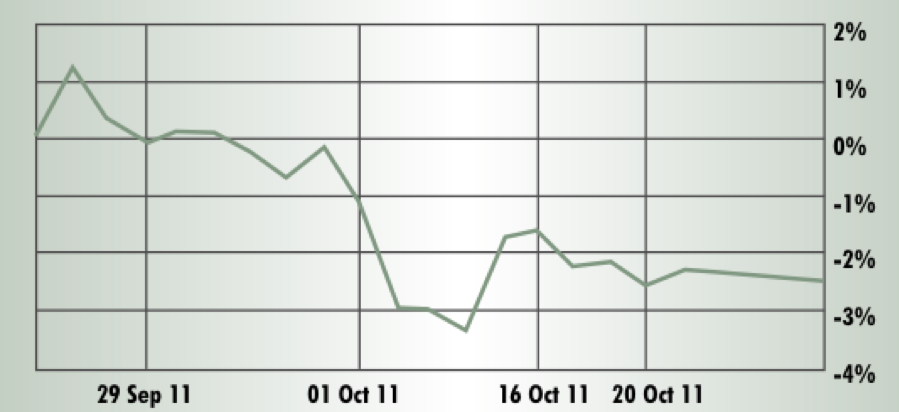
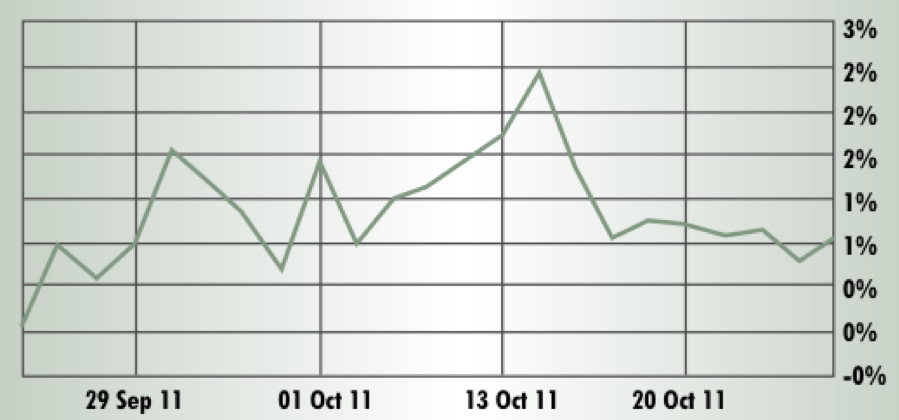
BLOM Stock Index (BSI)

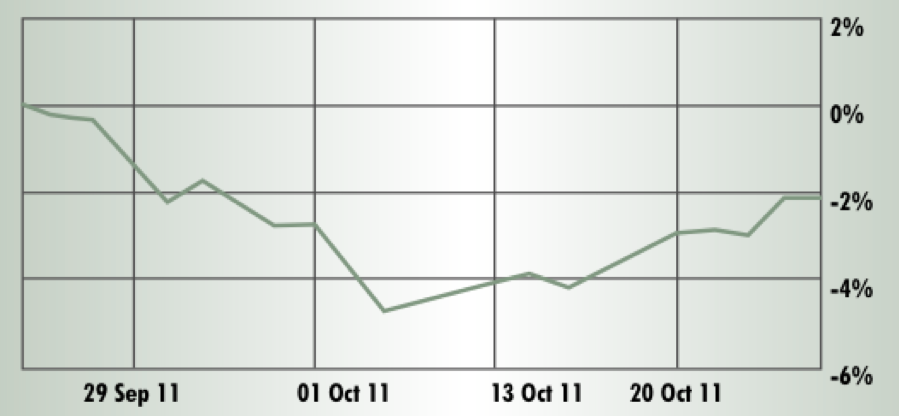
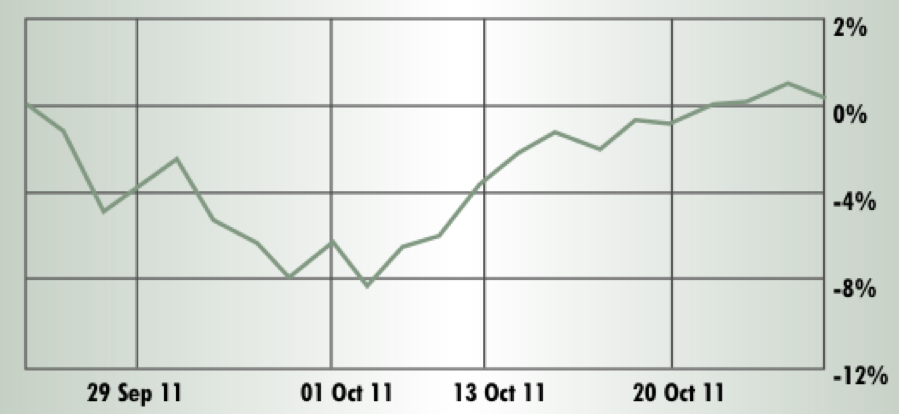
Weighted effective yield of Eurobonds

Equity update

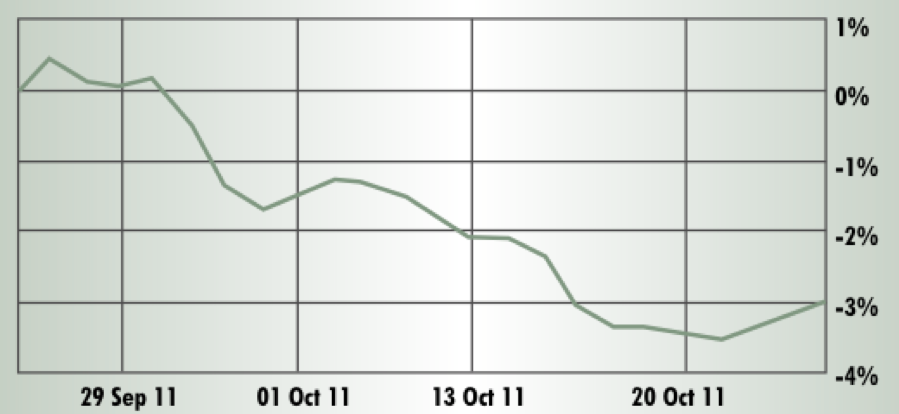
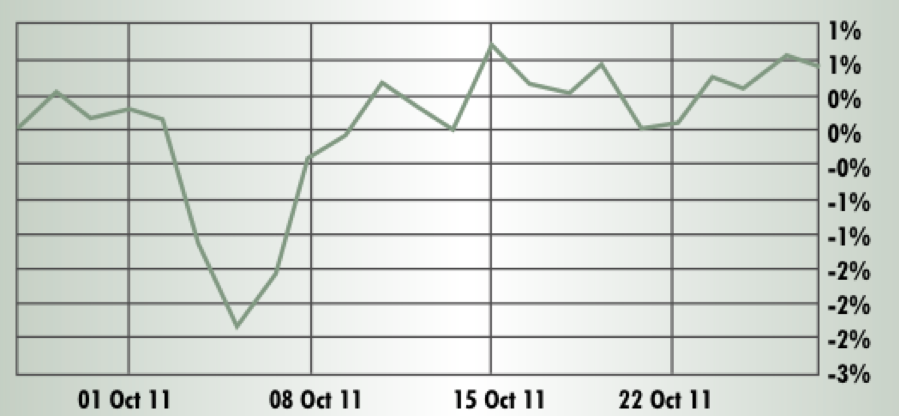
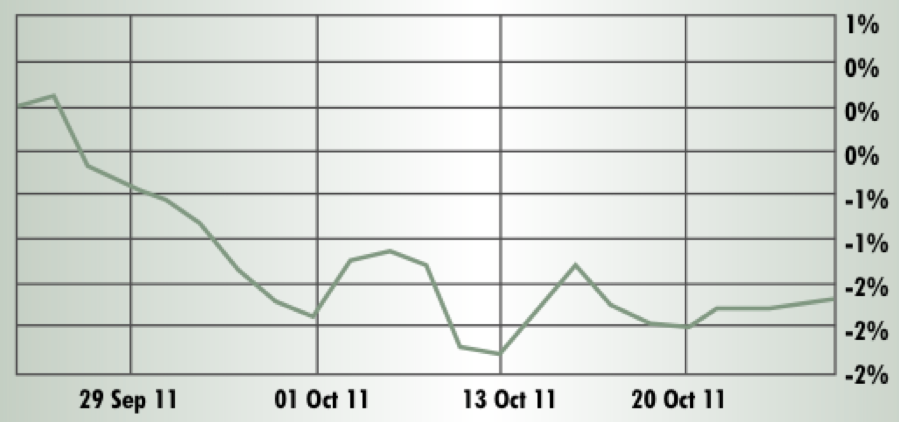
The shivering political situation in the Arab region, the gloomy economic situation in Lebanon and fears of another global recession weighed negatively on investors’ appetites for equities. This was reflected by the relatively low daily average volume of 150,811 shares valued at $1.02 million during the four-week period between September 16 and October 14, as opposed to an average 182,811 shares worth $1.72 million traded daily during the preceding four-week period. The BLOM Stock Index (BSI) hovered between a lower threshold of 1,205 points and a higher band of 1,244 points, before closing at 1,220 points on Friday, October 14, its lowest close since June 2009. The BSI closed around 2 percent lower than on September 16, and 17.3 percent lower than its value on December 30, 2010. 

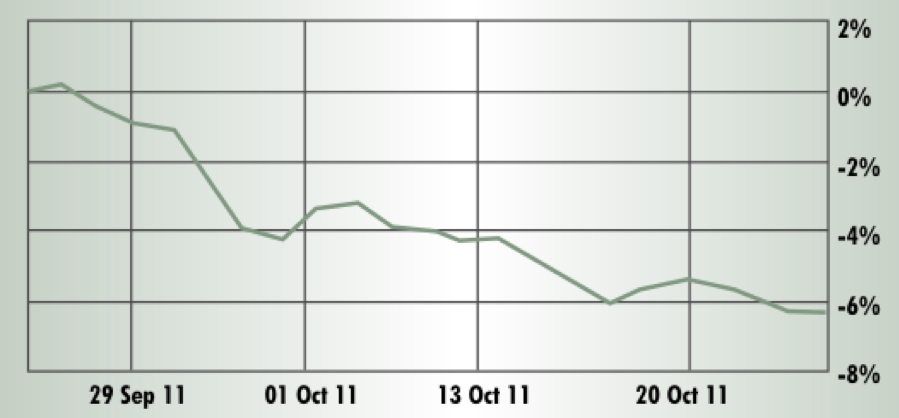
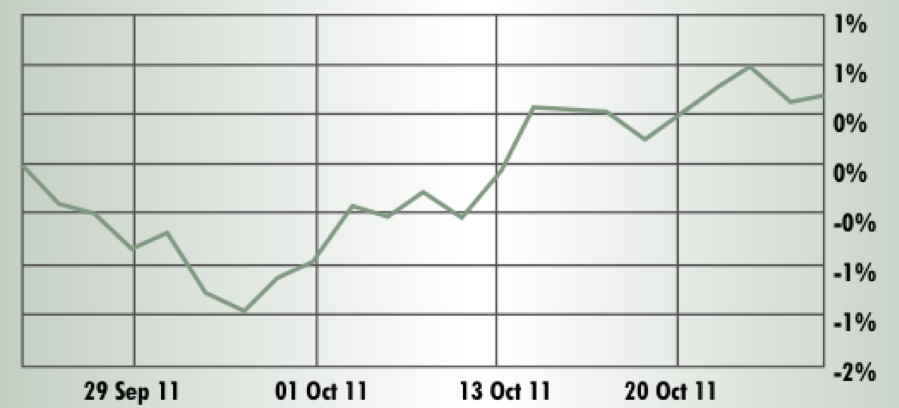
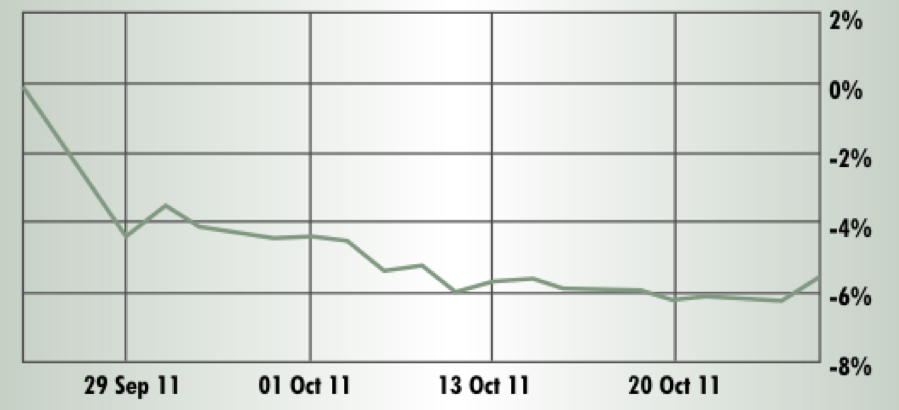
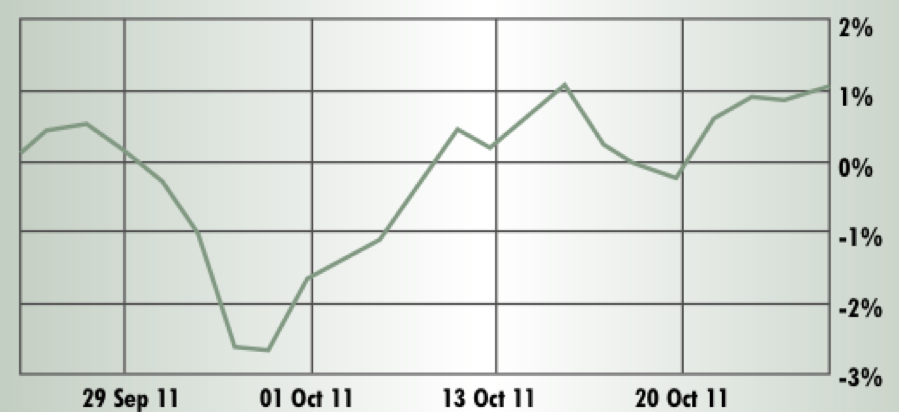
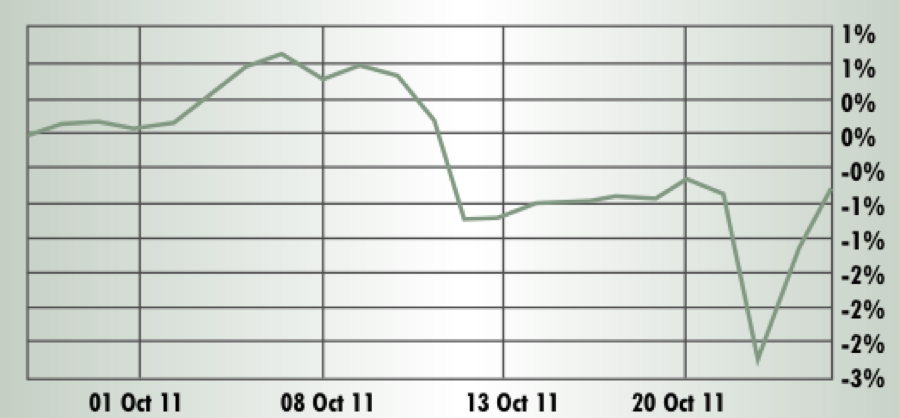
On the regional front, the BSI outperformed the Morgan Stanley Emerging Market Index (MSCI), which lost 3.5 percent, during the four-week period, to settle at 930 points after distressing economic developments in  Europe at the end of September. As for the S&P Pan Arab Composite LargeMidCap Index, it fell by 1.2 percent to 106 points.  

Banking stocks captured the bulk of trade between September 16 and October 14, representing 63 percent of the total value traded. BLOM Bank stocks retreated during the period, as its Global Depository Receipts (GDR) lost 3.9 percent to hit $7.85 and its listed stock declined by 4.7 percent to settle at $7.80. However, BLOM Preferred 2011 added 0.1 percent, to settle at $10.12. Bank Audi listed stock dropped 3.55 percent to $5.98, while its GDR reversed the trend, adding 0.15 percent to reach $6.83. Both Audi and BLOM common stocks touched their lowest values since their respective stock splits in May and October 2010. It is worth noting that Bank Audi listed an additional 1 million GDRs on the Beirut Stock Exchange that were converted from Audi listed stocks as of September. Byblos and BEMO common stocks decreased a respective 1.2 percent and 3.9 percent to $1.63 and $2.47, whereas Bank of Beirut common stock gained 1.2 percent to hit $19.50.

In the real estate sector, Solidere A and B edged below their support level of $15, losing 1.3 percent and 2.6 percent to stand at $14.95 and $14.9 respectively, their lowest level in more than two years.

In the industrial sector, cement manufacturer Holcim Liban added 1.7 percent to reach $16.99 after revealing an 11 percent year-on-year growth in profits. Ciment Blanc Class B hit $3.25, its highest level since March 1998.

Eurobond bulletin

The Lebanese Eurobond market saw some selloffs on profit taking from foreign investors during the last two weeks of September, in order to cover some of their losses incurred in emerging markets. The BLOM Bond Index slipped 0.15 percent to 111.07 points. The portfolio weighted yield remained almost unchanged at 4.77 percent, whereas the spread against the US benchmark yield widened 16 basis points (bps) to 388bps as investors rushed for fixed income instruments. Lebanon’s credit default swap (CDS) for five years — a proxy for a country’s risk of default — reached 402-432bps compared to 395-425bps on September 16. Comparatively, in regional markets, Dubai and Saudi Arabia CDSs were quoted at 453-464bps and 111-118bps respectively.

November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Market bulletin

by Executive Editors November 25, 2011
written by Executive Editors

Beirut SE  

>  Review period:  Closed October 24 at 1,212.74 points   Period Change: -1.69%

The Beirut Stock Exchange was a ghost town in October as investors hid from uncertainty in Syria and worrying indicators for the outlook of the Lebanese government, economy and banking sector. In the meantime, a raise in the minimum wage united business owners and employee syndicates against the government but did little to attract investors desperate for stability. Class A shares of Solidere, the developer of Downtown Beirut, fell 2.05 percent during the period while Bank Audi, which reported its slowest growth in net profit since 2007, held its ground.

Amman SE  

>  Review period:  Closed October 24 at 1,955.62 points   Period Change: -1.81%

A positive mood reigned over Amman stocks in October with a new political leader promising reforms even more feverishly than his predecessor. To investors, however, the ride back looks bumpy at best, but the 1.8 percent rise from the low point on October 10 is a good start. Regional instability is making it tough for the market, given the economy’s dependence on declining tourism. Royal Jordanian shares plummeted 7.8 percent on large full-year loss estimates but management and trading in banks was light, with Arab Bank falling 2.3 percent during the period.

Abu Dhabi Exchange  

>  Review period: Closed October 24 at 2,446.71 points   Period Change: -3.42%

The Abu Dhabi Exchange’s dismal performance in October proved that money can not always buy investor happiness. Abu Dhabi stocks, previously considered safe from the Dubai debt crisis, plummeted to a 30-month low as risk-aversion emanating from Europe left investors watching from the sidelines. Although the National Bank of Abu Dhabi reported strong third quarter earnings, the bank’s shares were met with little cheer at empty exchange hallways, leaving the stock to tumble to 5.2 percent, a minor loss relative to real estate developer Sorouh’s 15.7 percent plummet before reporting results.

Dubai FM  

>  Review period: Closed October 24 at 1,359.77 points   Period Change: -5%

Dubai may be safe from Arab uprisings but local woes proved enough to upset the markets. The Dubai FM index was the region’s worst performer during the period as rumors surfaced that the exchange would not be upgraded to MSCI Emerging Markets status in December 2011. If that were not enough, Emirates NBD, which was forced to take over fallen Dubai Bank, said profits fell more than half in the third quarter, sending its stock down 8.5 percent. Real estate developer Emaar fared even worse ahead of earnings, down 9.8 percent.

Kuwait SE  

>  Review period:  Closed October 24 at 5,918.5 points   Period Change: +1.46%

Kuwait’s market recorded another month of positive growth, as a new wave of optimism came from an increase in real estate transactions: National Real Estate witnessed an outburst of trading that drove the stock up 56.8 percent. Banks suffered the fate of their peers elsewhere in the region as National Bank of Kuwait reported dismally flat third quarter earnings and floated 3.78 percent upwards on low volumes. Ahli United Bank struck down investors with a 10.6 percent scorcher ahead of earnings.

Saudi Arabia SE  

>  Review period:  Closed October 24 at 6,132.25 points   Period Change: +0.33%

It appears nothing can shake the Saudi mammoth exchange, including the cancellation of the Zain Saudi Arabia takeover or the 53 percent drop in the company’s third quarter profit. Zain’s shares fell only 9.6 percent but the market remained buoyantly in positive territory. Banking stocks took the rudder, and with tailwinds of double digit growth in net profits in the third quarter, they brought in 2.3 percent from their bottom on October 4.

Muscat SM  

>  Review period:  Closed October 24 at 5,538.75 points   Period Change: -1.1%

The comeback from the end of September/early October slide was more difficult than expected for Muscat securities. Investors welcomed leaping profits at Bank Muscat, sending the stock up 3.4 percent, but kept National Bank of Oman flat despite increased third quarter earnings. The exchange’s newest comer, SMN Power, also received a warm welcome and a 3.6 percent rise over its subscription price. But the excitement remains limited by downbeat trading volumes, prompting brokerage firms to petition the Capital Markets Authority for more flexibility with margin trading rules.

Bahrain Bourse  

>  Review period:  Closed October 24 at 1,144.4 points   Period Change: -1.83%

Bahrain investors can take a breather from a marathon year of record losses. Mixed third quarter earnings kept some traders interested, but the cold pause in domestic politics and the rising tensions between Saudi Arabia and Iran do not bode well for the average capitalist. Arcapita’s rating was also downgraded and kept on negative watch by Moody’s as Gulf International Bank saw its profit dwindle 13 percent in the first nine months. Aluminum Bahrain fell 10 percent despite reporting growth in production, on fears of rising production costs and weaker global demand.

Qatar SE  

>  Review period:  Closed October 24 at 8,457.95 points   Period Change: +0.76%

It is not all good news for Qatari stock traders, but the worst is probably behind them. After an initial flop following rumors that the Qatar Exchange would not be upgraded to MSCI Emerging Market status in December 2011, stocks took comfort in strong profits at most companies and rallied 3.7 percent from their low point on October 5. Qatar National Bank, Qatar International Islamic Bank, Masraf Al Rayan and Commercial Bank of Qatar all bucked the MENA loss trend and reported healthy earnings, with the latter’s shares inching up 1.5 percent during the period.

Tunis SE  

>  Review period:  Closed October 24 at 4,538.41 points   Period Change: -2.74%

The victory of Islamic ‘renaissance’ party Ennahdha in Tunisia’s polls meant anything but a renaissance for Tunisian stocks. Although party leaders promised not to impose Sharia law or retract women’s rights, investors were cautious after several months of optimism. With lower tourist numbers, a crisis in nearby Europe and another round of elections in a year preceded by a re-drafting of the constitution, stocks fell. Tunis Air dropped 2.9 percent and Carthage Cement fell 3.8 percent during our review period through October 24.

Casablanca SE  

>  Review period:  Closed October 24 at 11,333.9 points   Period Change: -1.1%

Investors contemplated Moroccan stocks as they watched the forthcoming November 25 parliamentary elections on the horizon. A debate erupted over the construction of the country’s high speed train linking Tangiers to Casablanca. In choppy trading, Attijariwafa Bank, an exchange heavyweight, was off 3.42 percent during the period while Itissalat Al Maghreb held its ground. With the key tourism sector suffering, hopes are high for Gulf support after being promised full GCC membership.

Egypt SE  

>  Review period:  Closed October 24 at 4,311.88 points   Period Change: +4.22%

Egyptian stocks are again fertile land for investment. The resumption of negotiations with the IMF and World Bank over a subsidized $3 billion loan and 10 times more in promised funds by the G8 sent Egyptian stocks soaring to the top of MENA exchanges during the review period. The prisoner swap between Egypt and Israel and the recommencement of gas flows at revised prices boded well, and drove Orascom Construction Industries up 5.9 percent and Commercial International Bank up 12 percent.

November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Financial quotes of the month

by Executive Editors November 25, 2011
written by Executive Editors

“The biggest headwind the American economy is facing right now is uncertainty about Europe.”

Barack Obama, president of the United States

“Lebanon will not be affected by a recession in Europe as the Lebanese economy essentially is dollarized.”

Riad Salameh, governor of the Lebanese central bank

“You want to look for countries with relatively clean balance sheets, with AAA types of ratings and with the ability, importantly, to print money.”

Bill Gross, founder of Pacific Investment Management Co (PIMCO), the world’s biggest bond fund

“This is the most serious financial crisis at least since the 1930s, if not ever.”

Mervyn King, governor of the Bank of England

“It was a wrong decision.”

Khalaf al-Habtoor, chairman of Al Habtoor Group, on their decision to acquire a stake in British lender Barclays in 2008

“We are open to any investment opportunities in all parts of Europe.”

Mustapha al-Shamali, Kuwait’s finance minister

“Don’t be a dick.”

What an investor apparently told Glencore’s CEO Ivan Glasenberg after he asked about the possibility of a last minute increase in the list price of its $10 billion IPO

“They [the IMF] have very substantial resources that are uncommitted.”

Timothy Geithner, United States Treasury Secretary, on the US’s refusal to inject more funds into the IMF

“We do not look opportunistically at distressed assets or special assets that come up one way or the other.”

Mohamad al-Jasser, governor of Saudi Arabia’s central bank, when asked about buying European sovereign bonds
November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

For your information

by Executive Editors November 25, 2011
written by Executive Editors

Beirut Stock Exchange trades thin

Trading activity on the Beirut Stock Exchange (BSE) is dire so far this year. The total volume traded stood at 64.2 million shares as of the end of September, a 54 percent year-on-year decrease. Turnover stood at $467 million, down a whopping 72 percent from September 2010, and the BSE’s market capitalization decreased 14 percent to reach $10.6 billion. While the Lebanese equity market is being hit, the spreads on the country’s credit default swaps (CDS) — effectively the market’s perception of a county’s default risk — have been outperforming global peers. Spreads on Lebanon’s CDS have widened just 22 percent in the third quarter and stood at 429.7 basis points according to CMA Datavision, a CDS and bond-pricing firm. This is a much better performance than the widening of spreads in Denmark (216 percent), The Netherlands (176 percent), Italy (165 percent) and Austria (160 percent). Only the United States, Venezuela and Ireland performed better than Lebanon in the third quarter.

Merrill Lynch and Barclays recommend Lebanese Eurobonds

Merrill Lynch upgraded its rating on Lebanon’s external debt to “Overweight” from “Market Weight” within its emerging markets portfolio, placing Lebanon in the same category as Abu Dhabi, Qatar, Jordan, South Africa, the Philippines and Uruguay. The upgrade is driven by the low beta correlation of Lebanese Eurobonds to the international markets, due largely to an increased risk aversion. Merrill Lynch also raised Lebanon’s allocation in its portfolio to 3.9  percent from 3.5 percent and highlighted that Lebanon’s external debt returns were the only ones in positive territory among the 42 emerging economies in the portfolio. Barclays Capital maintained its “Market Weight” recommendation on Lebanese Eurobonds in its emerging markets credit portfolio but raised Lebanon’s allocation to 2.8 from 2.4 percent.

Tier one capital ratio to hit 12 percent

Lebanon plans to raise its tier one capital ratio, the core measure of a bank’s financial strength, to 12 percent within seven years, more than required by BASEL III, a new global regulatory standard on bank capital adequacy. Basel III requires banks to hold a tier one capital of 6 percent, up from 4 percent, by 2015. According to Riad Salameh, governor of Banque du Liban (BDL), Lebanon’s central bank, the new capital requirement imposed on Lebanese banks would place them “among the highest in terms of capital adequacy.” BDL will soon issue a directive requesting a 10 percent target for tier one capital within four years, rising to 12 percent three years later. During meetings at the International Monetary Fund, Salameh indicated that he does not expect Lebanese banks, which have an insignificant exposure to European sovereign debt, to be affected by the European crisis. He added that current regulations encourage solvency and liquidity in line with Basel III.

Gulf investors drop bid for Zain Saudi

Kingdom Holding, own- ed by Saudi billionaire Prince al-Waleed bin Talal, and Bahrain Telecommunications (Batelco) dropped their $950 million bid to buy a 25 percent stake in Zain Saudi, the kingdom’s third-largest mobile phone company which is owned by Zain, Kuwait’s biggest mobile phone company. The failure of the deal follows the collapse of two previous attempts to acquire a 46 percent stake in Zain: one in March for $12 billion by the United Arab Emirates’ operator Etisalat, and one in September 2009 for $13.7 billion by India’s Vavasi Group and Malaysian billionaire Syed Mokhtar al-Bukhary. Zain Saudi’s third quarter results showed accumulated losses of $2.5 billion, pushing the company to focus on capital restructuring. Zain Saudi recently appointed Khalid al-Omar as chief executive officer after the resignation of Saad al-Barrak. As of October 13, Zain Saudi’s stock price was down 27 percent on the year.

Commercial bank assets up

The total assets of Lebanese commercial banks stood at $138.1 billion as of the end of August 2011, a 10 percent year-on-year increase. Private sector deposits also increased 10 percent year-on-year and stood at $113 billion. Deposits in Lebanese lira stood at $37.8 billion, down 1.7 percent year-on-year while deposits in foreign currencies rose 17 percent to reach $75.2 billion. The dollarization rate of deposits rose to 66.6 percent, up from 62.6 percent a year ago. Loans to the private sector increased 17 percent year-on-year and amounted to $39 billion, of which $5.6 billion went to the non-resident private sector.

Emirates NBD takes over Dubai Bank

Emirates NBD, the largest lender in the United Arab Emirates, has taken over the struggling Islamic lender Dubai Bank for an undisclosed amount on the orders of Sheikh Mohammed bin Rashid al-Maktoum, the ruler of Dubai. The Dubai government, which holds a 55.6 percent stake in Emirates NBD, had acquired Dubai Bank in May after it was hit hard by the financial crisis. Before the takeover it was owned by both Dubai Holding, with a 70 percent stake, and Emaar properties, with a 30 percent stake. In an emailed statement, the government’s media office said the takeover was “in line with Dubai government efforts to enhance the banking sector in the emirate.”

Iraqi Telecommunications IPO delayed

Iraq’s three telecommunications operators, Korek Telecom, Zain Iraq and Asiacell, missed their planned deadline for floating on the Iraqi Stock Exchange (ISX). The companies were expected to be listed by the end of August 2011 but will not be penalized for missing their targets and now seem unlikely to launch an initial public offering (IPO) until the middle of 2012. The operators are first required to change from private companies to shareholding firms, which is expected to take a month to complete. The Iraqi exchange’s market capitalization stands at just $4 billion, with the average daily volume traded just $2 million — yet, technically, it is one of the world’s best performing markets this year. Taha Abdulsalam, chief executive of the ISX, expects the current market capitalization to double when operators list on the Iraqi bourse.

Qatar investing in gold and Luxembourg banks

Qatar Holding, a subsidiary of the gulf state’s sovereign wealth fund, the Qatar Investment Authority (QIA), is planning to create a standalone investment vehicle called “Qatar Gold” to invest in gold companies. It began by acquiring a 10 percent stake in British mining company European Goldfields at a cost of $775 million, of which $600 million will finance mine development in Greece. The Qatari royal family is also buying two banks in Luxembourg previously owned by troubled Belgian banks, Dexia and KBC. Precision Capital, a Qatari-backed firm based in Luxembourg, agreed to buy KBC’s private banking unit, KBL European Private Bankers, for $1.4 billion. Following the break up of Dexia by the French and Belgian governments, the Qatari royal family agreed to acquire Dexia’s troubled unit in Luxembourg, Dexia Banque Internationale Luxembourg (BIL), for an undisclosed amount. Qatar National Bank, which is 50 percent owned by the QIA, is in talks to buy the Turkish division of Dexia, Denizbank, in a deal that could potentially be worth $6 billion.

November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
Feature

Revolution reaches for the next level

by Executive Editors November 25, 2011
written by Executive Editors

Since February 11, Tahrir has been taken to the factories,” says workers’ rights activist and blogger Hossam al-Hamalawy. “The barometer for progress has been [thought of as] how many people gather in Tahrir, but that’s not true. The labor strikes that have taken place after former president Hosni Mubarak’s fall are phase two of the revolution.” 

Egypt has witnessed more than 120 different labor strikes since March this year, according to data from the Egyptian non-governmental organization (NGO) Awlad El Ard Association for Human Rights. This is in addition to over 490 sit-ins, demonstrations and protests. Experts estimate that roughly half a million workers participated in strikes in August and September alone.

The current wave of labor actions found its roots in December 2006, when the nation’s center of textile production in the industrial city of Mahalla El Kubra saw an outbreak of wildcat strikes. These protests in many ways helped pave the way for this year’s 18-day uprising and its perceived success after workers took to the streets during the final days of the revolution, ensuring Mubarak’s dethroning.

“The organization and awareness of workers is in itself outstanding… I think in the future, these workers will lead the way to change”

Unions unquelled

Labor agitation escalated in mid-September, most significantly when tens of thousands of teachers descended on downtown Cairo as part of a larger strike calling for increased wages. That same week, hundreds of thousands of doctors, nurses and health technicians walked out of public hospitals, while transportation networks ground to a crawl when workers from 25 bus depots across Greater Cairo staged a partial strike.

“The organization and awareness of workers is in itself outstanding,” says labor activist and journalist Moustafa Basyouni. “I think in the future, these workers will lead the way to change.”

Egypt’s labor force is more than 25 million people and worker protests have affected all sectors of the economy, most occurring in the public sector. Acting government officials eventually negotiated with teachers and transport workers. However, other strikers have been completely ignored.

“It just depends on the power of the strike,” says Hamalawy. “Look at the aviation workers; you can’t mess with them. They brought Cairo to a halt.” When air traffic controllers went on partial strike in early October, hundreds of flights were delayed and travelers stranded, forcing officials to address their concerns.

In what human rights activists consider among the more troubling responses to the strikes, workers have been arrested and tried in military courts. Many cite the authorities’ failure to address workers’ concerns in a consistent manner as an obstruction to a return to normalcy, wreaking havoc on the economy.

The government’s projected 3.5 percent economic growth rate for 2011-2012 is unrealistic given the unstable political and social environment, according to Magda Kandil of the Egyptian Center for Economic Studies.

“We know that growth rate has slowed to 1.8 percent,” she says, “and I’m not confident at this point that it’s back on track. The private sector remains at a standstill and foreign investors are concerned [about financial risk], so they’ve scaled down involvement.”

“The military is not dealing well with the labor strike movement,” she adds, referring to the Supreme Council of the Armed Forces (SCAF), the ruling junta that rose to power following Mubarak’s ousting.

“I think the frustration in the labor movement reflects [the fact] that many people are not happy,” says Kandil. “The best thing the ruling council can do is ensure a swift transition.” Parliamentary elections are slated to begin on November 28, but SCAF says it will retain power until a new president is elected, with this ballot now expected as late as 2013.

The number of civilians subjected to military tribunals by the ruling council exceeds the total number of people tried this way under Mubarak’s 30-year rule

SCAF’s bludgeon of ‘justice’

Within the confines of a military prison, Khamis Mohammad was stripped and beaten brutally. “I was treated as an enemy of the country, as if I was the reason for the poor economy,” says the young Egyptian who is one of many arrested on charges of public assembly in violation of an anti-strike law.

After being plucked from a 200-man sit-in outside Cairo’s petroleum ministry, Mohammad remained in a dingy jail cell for weeks until he was given a one-year suspended sentence by a military — not civilian — court. Such trials are just one aspect of post-revolution governance by the ruling military council that human rights organizations claim undermine a smooth transition to democracy.

“Military trials are a way of intimidating the opposition and are counter-revolutionary by nature,” says Shahira Abu Leil of the human rights group No Military Trials for Civilians. “The revolution was about freedom of expression and free speech. And the military has tried people who were exercising these rights.”

“SCAF is doing this because it’s a way to put people back into a disciplined state,” she adds.

Some 12,000 Egyptians have appeared before military courts since the start of the revolution; roughly 8,000 remain in prison and 4,000 have been released, according to Abu Leil. Courts have acquitted 795 of the total number of cases, equating to a conviction rate of 93 percent, Human Rights Watch (HRW) said in a September 2011 report; 1,836 individuals, like Mohammad, were released on suspended sentences.

“The judges are in a clear hierarchy, so one of the concerns we’ve had with the military justice system is there have been cases of clear political instruction,” says Heba Morayef of HRW. “In your average [civilian] courts judges make independent decisions, but in these cases SCAF is making the decisions.”

The ruling council has held their ground on the judicial system refusing calls to end military tribunals, citing increased crime rates and the need to prosecute baltageya — or thugs — who have been on the prowl since the January uprising.

“Military trials are easy and efficient,” Morayef says. The average length of each trial is between twenty and forty minutes and civilians are sometimes tried and sentenced in groups. “But decisions are often not based on proper examination of the evidence,” she argues.

The number of civilians subjected to military tribunals since the ruling council rose to power on February 11 exceeds the total number of people tried this way under Mubarak’s 30-year rule. Those convicted range from laborers to activists, such as blogger Maikel Nabil who went on a hunger strike after being sentenced to three years in jail for “spreading false information” and “insulting the military establishment”.

In early October, seven demonstrators were plucked from a protest in the Nile Delta city of Shabin El Koom while demanding improved factory conditions and increased job stability for workers at the Turkish textile company, Mega Textile. Those arrested were given 15-day jail sentences while investigations took place, an act allowed under Egypt’s Emergency Law.

“This needs to be changed because the people are considered guilty until they’re proven innocent,” says Egyptian lawyer Mohammad Hassan as he stands among a group of workers in the city.

Egypt’s widely reviled Emergency Law has long been a hot-button issue for activists because it gives the military government the right to detain people without charge and criminalize mass gatherings. Emergency law was to expire at the end of September but was renewed following a violent attack on the Israeli Embassy in Cairo.

“The recent crackdown is on political protests, labor protests,” HRW’s Morayef says, “and from a freedom of assembly standpoint, that’s very serious.”

SCAF is refusing to repeal emergency law despite requests not only by enraged activists but also by the Obama administration. United States Defense Secretary Leon Panetta raised concerns about the Emergency Law while visiting Egypt in October, and US President Barack Obama is urging Field Marshal Hussein Tantawi to repeal the action and put an end to military trials. As part of the widening crackdown, SCAF has placed a firmer grip on civil society, restricted press freedoms and carried out arbitrary arrests — all characteristics of Mubarak’s regime.

The Egyptian cabinet announced in September that more than 30 Egyptian NGOs are being investigated for receiving foreign funding without being properly registered. Should these groups be found guilty of “treason”, Egypt’s human rights network could effectively be shut down.

“The recent crackdown is on political protests, labor protests… and from a freedom of assembly standpoint, that’s very serious”

Silencing the press

Additionally, the military council is censoring media following months of relative press freedom. In mid September, plainclothes police  stormed the offices of Al Jazeera’s Mubasher Misr Channel , taking equipment and rouging up staff. Two weeks later, an edition of the weekly Sawt Al Umma and the daily Rose Al Youssef were prevented from going to print allegedly over controversial stories. In a subtler form of censorship, a writer at a popular Cairo-based magazine says management was told specifically not to write articles that criticize the military, or they would face punishment.

Most severely, military forces clashed with civilians on October 9 during a demonstration by Coptic Christians, leaving 24 dead and hundreds injured. The same evening, the US-funded Al Hurra television station was raided by military forces brandishing automatic weapons. Telephone, electricity and Internet services were also cut to one of Egypt’s leading newspapers, according to the Committee to Protect Journalists.

November 25, 2011 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 358
  • 359
  • 360
  • 361
  • 362
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE