• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Finance

In from the dark

by Executive Staff November 3, 2011
written by Executive Staff

The most significant innovation in the Lebanese insurance industry this year is transparency in on-time delivery. For the first time in roughly 60 years of collecting premiums and paying claims, the majority of insurers have made their quarterly headline numbers available for evaluation.

Starting with the first quarter 2011, Lebanese insurance industry data is published in a statistical review by the Association des Compagnies d‘Assurances au Liban (ACAL). They cover overall trends for premiums, claims and ratios as well as trends per business line — including life insurance, motor and others — for a total of nine areas of insurance activity.

“The insurance control commission at the Ministry of Economy and Trade started publishing the annual report on the insurance sector in 2005 and it was an important initiative,” said Jamil Harb, secretary general of ACAL. “However, we realized that it would be better for the companies and the public interest to gain faster access to this statistical information, so the ACAL Board proposed to the member companies to find an independent and trustworthy company to carry out the publication of the quarterly report.”

Harb told Executive that ACAL committed itself to the project as the two-year time lag in issuance of the official reports greatly reduced the usefulness of the information. The association commissioned reputed local auditing firm Fiduciaire du Moyen Orient to provide the analysis of data, while guaranteeing the full confidentiality of it to each individual company.

According to second-quarter data, Lebanese insurers underwrote risks represented by $623.3 million in gross premiums in the first six months of 2011. This compares with $1.11 billion in premiums in the whole of 2010 and when compared with the first six months of 2010, represents a year-on-year growth of 17 percent.

The trials of transparency

It is a common problem in international insurance markets that sector players are often more reluctant than other financial companies to disclose their information. Underwriting performance in terms of gross premiums is generally easiest to obtain, but an insurance market’s performance can really only be understood if information is available on aspects such as the net premiums after cession of risks to reinsurance companies, technical reserves, ratios and other issues.  

On the upside of transparency, however, sector companies can only assess their real positions vis-à-vis their peers and the actual market trends if comprehensive data is available quickly. Lebanese insurance leaders have so far reacted well to the first two editions of the report.

“It definitely helps to have the statistics,” said Fateh Bekdache, general manager of Arope Insurance. Before the introduction of the reports by the association, sector companies were limited to data the Arabic business magazine Al Bayan collected annually from the companies, and Bekdache noted that this was not always reliable given that they were unaudited.

Edward Traboulsi, general manager of Assurex Insurance, said statistics help to benchmark it against its peers. He hailed the reports as “an excellent tool which we didn’t have before. There are so many questions that are left unanswered if you don’t have benchmarking statistics.”

Claims & benefits 2011

The report for the second quarter of this year showed that Lebanese insurers paid out $258.5 million in claims and benefits to their policyholders by June 30. Like premiums, claims and benefits were up from the same period in 2010. However, the rate of increase in claims was 10 percent, notably below the rate of premiums growth. The year-on-year increase in claims and benefits at the end of the first quarter stood at 4 percent.

The two dominant business lines in terms of total turnover in the first half of the year were, as usual, medical and motor insurance, 33.4 percent and 25.7 percent, respectively. Life insurance was the third largest sector, representing 23.1 percent. The combined market share of the three lines left the other lines in general insurance — from workmen’s compensation and fire to marine and engineering — vying for less than one fifth of the total premiums pie.

The data on paid claims shows that motor and medical claims represent nearly 75 percent of everything paid out by insurers. The gap between the shares in total premiums and total claims payments for the two lines was thus about 15 percentage points in favor of claims. While illustrating the extreme importance of the two largest business lines for the industry’s revenues, the overweight of motor and medical claims in percentage terms also underscores the volatility of those lines.

In the smaller, more profitable lines such as fire, marine cargo and hull, engineering and construction, general liability and others, the statistics illustrate that these lines — due to their small size of total premiums — can be exposed to significant fluctuations on the claims side when just one major case occurs, such as an industrial fire destroying a multi-million dollar manufacturing facility.

The analysis of the insurance sector still has lots of room for improvement. Part of this evolution will occur naturally, as with the flow of time the issuance of reports will make the information published in the first two quarters more relevant and comparable.

Another value boost will come from increasing participation from insurance companies that have committed themselves to provide the quarterly information on a voluntary basis. The second-quarter report already reached a comprehensive 95 percent coverage of all non-life premiums, based on data reported by 42 of ACAL’s 53 members. However, the absence of one major life insurer’s data meant that the report’s figures captured a lower 80 percent of the activity in that sector.        

Insurer investments

One area in which the association is currently working to extend the statistical report’s coverage is in gaining a view of investment portfolios which insurance companies hold. The importance of insurance companies as institutions in financial markets is directly related to their muscle mass as investors. Wielding this investment power essentially on behalf of their policyholders, insurance companies provide a component of stability to both financial markets and society. 

The size, allocations to investment classes and profitability of the insurance sector’s investment portfolios are thus of interest to the public as indicators of the companies’ financial health. The portfolio data is also of interest to professional analysts across the entire finance industry as, for example, growing investment power by local insurance companies could provide a telling hint on the possibility of seeing more liquidity in Lebanon’s financial and equity markets.

Investments by insurance companies in relation to their insurance business play a preeminent role in developed insurance markets and estimates are that sector companies in Lebanon invest more than two dollars tied to their life insurance business for every dollar they invest related to non-life business.

Inclusion of insurance sector investment portfolio data overall, and their correlation to each business line, is on the agenda of the ACAL quarterly report for upcoming editions. According to Harb, the compilation and analysis of this data is still being worked out, as extrapolations of totals are not possible when analyzing investment activities that are distinct for each company.
November 3, 2011 1 comment
0 FacebookTwitterPinterestEmail
Finance

Q&A – Assaad Merza

by Executive Staff November 3, 2011
written by Executive Staff

The Association of Insurance Companies in Lebanon (ACAL) is the leading voice representing insurance providers in the country. Executive sat down with ACAL president Assaad Merza to learn about the challenges facing the industry.

E  What are the plans of ACAL, especially after we witnessed the passing away of former ACAL President Abraham Matossian in May?
What we are doing is always a continuity of what Mr Matossian was doing. He was a great man and it is very important to us to follow what he did. [However], every person has a different idea of how to develop the association. What we are doing now started with the statistics on the website, which is a very nice thing. We also have very good relations now with the Ministry of Economy and Trade and are working on the new insurance law with the ministry.

E  Are there any specific changes that you are seeking to implement in relations with the insurance commissioner at the Ministry of Economy?
There has been some trouble in the past [between us and the commissioner]. Now we are open for discussions, which is very important.

E  What other plans does ACAL have?
We are going to convene conferences within the association; [international reinsurance company] Munich Re is coming to do a conference and perhaps Swiss Re and Partner Re will be coming. We are going to do conferences with the big insurance companies, which is very important. We are activating ACAL more and more.

E  Global financial markets are in upheaval. In light of this uncertainty, what is the outlook for the Lebanese insurance sector?
[The uncertainty] is also on a regional level. We are concerned with what is happening in the Gulf and we are concerned with what is happening in the countries next to us — Syria, Egypt and Jordan. The situation in all these countries is bad for us.

E  How does the situation in neighboring countries affect Lebanon’s insurers?
Many Syrian people used to come [to Lebanon] to do shopping and many things but today we feel that even the car market is reduced. The statistics show that [sales of] expensive cars are much lower and the import of goods is lower. On the transport side, this reduced our production [of insurance premiums] and on the motor side, our production was reduced.

E  How are the developments in other insurance lines?
What is up a little bit is the medical but this increase is because we increased our premiums a little since hospitals have increased their rates. On the life side, there is a bit of an increase but it is still not a healthy business. I hope in the long run that the economic situation will be much better, we will do better and all the companies will be healthier.

E  You addressed the production of premiums, or turnover of the industry. How are things going in terms of profits?
Premiums are high but profits are not good. If we say that according to the commissioner’s report from 2009, we have about $40 or $41 million in profits — this is nothing; 51 companies with $40 million, this is peanuts. We are financial companies and we are making $40 million; this is not a healthy situation.

E  And the insurance sector is still extremely small when compared to the banking industry in Lebanon…
It is small also due to the situation; the Lebanese people, one can say, are poor. They are paying health [insurance] because it is something very important for their families but on the other [insurance needs] they are not doing anything.

E  Life insurance policies tied to loans have helped insurers increase business in the past. Could there not be potential in other areas related to banking such as developing credit insurance?
Let’s talk about the housing loans. The housing side was very important for us to develop our business due to the bank loans. But this year, banks have reduced their issuance of housing loans because of the economic situation and this has reduced our production.

E  Does the insurance sector have an official position regarding the government’s decisions on minimum wage?
Yes, we are with the [business community] and are not accepting [the government’s position to increase wages]; we cannot accept the increase in salaries. From the last salary increase in 2008 until today, the increase in the [inflation] index was 16 percent. We can increase [salaries] on a 16 percent [basis] but we cannot increase 40 percent. They said it is LL200,000 for the minimum salary, which is 40 percent.

E  Would the increase in minimum salary levels mean insurance companies will have to hike premiums?
Of course, and not only because of the salary increase.  Firstly, the hospitals, which have laborers working there, will increase their rates and then we will have to increase our rates. Secondly, there will be wide price increases. The situation on the minimum wage increases [is] already clear; supermarkets have started to raise prices, saying we have to see if salaries will go higher. We will have to increase our premiums.

E  You are trying to make insurance companies more efficient and to spread awareness on the value of insurance. How are these efforts proceeding, and what are the latest developments?
We are trying to change the image of the sector. We have to be much more open and we have to be, if you want, more solid. It is [important] to show the people that we are beside them and that we are not reluctant [to service policies]. This is very important. We are also trying to raise awareness through campaigns to save lives on the road in collaborating with NGOs such as Kunhadi. We see the need to support these types of NGOs because they create [traffic safety] awareness for all the Lebanese people, not only for the insured people. This is something new we are doing.

E  The sector today still includes more than 50 companies but there has not been much growth for all to share in. Do you think the Lebanese insurance industry will consolidate moving forward?
With the new law, I think there is something that can be done in the matter of consolidating companies. The new minister [of economy], Nicolas Nahas, is doing his best to implement this new law with our collaboration. This is what we heard from him.

E  Do you have an idea of the timeline for getting the new law approved and implemented?
Last month, [Minister Nahas] said [the new insurance law] was a priority for him but it may be delayed for six months or 12 months. I think it will happen in 2012.

E  In the past, ACAL has voiced criticism over some points in the draft for the new insurance law… 
There were 10 points and we sent this list to the new minister with our criticism on these points and he said he will take them into consideration.

E  And you feel that the relationship between ACAL and the ministry has been improving?
It is excellent and there is very good collaboration, even on a weekly basis.

November 3, 2011 0 comments
0 FacebookTwitterPinterestEmail
Finance

Q&A – Walid Genadry

by Executive Staff November 3, 2011
written by Executive Staff

Insurance customers rely on impartial authority to ensure that their insurance policy will be honored when they have to file a claim. For insurance companies, the supervision by a trusted public entity provides a shield of corporate credibility and a safeguard of companies’ financial solidity. Supervision, however, needs to be tailored expertly to meet both ethics and reality and even then dialog on regulations and requirements between insurance industry and insurance supervisor is often  tough and thorny. To better understand the local state of insurance, Executive sat down with Walid Genadry, head of the Insurance Control Commission at the Lebanese Ministry of Trade and Economy.  

E  When you outlined the concept behind proposed legislation for Lebanese insurance in 2004 you were not only convinced of the urgency of this matter but also enthusiastic about the law’s spirit and optimistic about a rapid adoption of what is still a draft law today. What happened?
I had less experience then [laughs]. Actually, there was reason to be optimistic, if things had gone like they would normally go in a normal country.

E  Under Lebanese circumstances, your optimism was a little bit…
…too high. But it was a reasonably good period at that time, before things took another turn. It is a shame because I see all the other countries in the region putting regulations in place.

E  But how important is regulation vis-à-vis having best practices? Lebanon, for example, has no actuarial association but we have more local actuarial competency in Lebanon than in most countries in the region. Is new regulation necessary where good practices already exist?   
Without regulation, it is not easy to have good practice. It becomes dependent entirely on who decides to have good practice. We would like everyone to implement good practices on their own and then we wouldn’t need a supervisor. This is not, unfortunately, how things usually go. On some issues, regulation is necessary. The issue is to determine which regulation you want through a law, which can be passed as a decree and which is best done through decision-making of the supervisory authority. That applies to most subjects, such as solvency and also actuarial issues. 

In terms of actuaries, yes we have more actuaries than others but we definitely don’t have enough, particularly since I am increasingly convinced of the necessity that some actuarial work needs to be done on non-life insurance.

E  Why do you see this actuarial work on non-life insurance lines as a growing need?
When I look at medical insurance, it is more risky in Lebanon than in France, or in Europe overall, because the government over there is the insurer of last resort. Under the French system, for example, it is quota-share by default and excess of loss without limit for anything serious, which means that the insurers have a very limited risk. We don’t [have this limited risk for medical insurers] and I would imagine that we need some actuarial work on this.

E  Has motor risk also been calculated with actuarial input?
Motor risk also, [but] I tend to be a bit less worried about motor. It is really high frequency and the nature of the accidents are almost always the same. Medical remains less controllable and you don’t know what types of diseases are being built in society. Today they are talking about cancer being not a genetic or a viral disease necessarily but a lifestyle one and we still don’t know what is hidden there. We are only realizing that cases of cancer are increasing significantly and we could not have forecasted this easily. That is why medical in my opinion is of concern.

E  Insurance balance sheets and risk calculations are widely seen as very difficult to understand even by accounting experts. From a regulator’s perspective, do the legislators sufficiently understand the needs for insurance regulations and how to legislate those terms?
This is not an easy business. People of course understand what insurance is and why it is needed, such as to avoid going bankrupt from being hit by a catastrophe. But when it comes to the mechanics of the insurance business and what a regulator ought to do, I would say that almost all of our legislators don’t understand that. This is a challenge because when you don’t understand you can be an easy target for inappropriate lobbying. You can get scared or influenced easily and with arguments that are seemingly logical. Unless you know how it really works and hear another point of view, it is very difficult not to be convinced that such arguments are right when they are not.  But we cannot change these things easily. We have to maximize whatever we can to introduce the proper legislation.

E  You have been criticized quite harshly at some points during the past seven years when the insurance law was being questioned repeatedly by the industry, and you have alluded in your speech to the fact that the supervisor, while never perfect, is regularly blamed when he does not deserve it. How do you view that criticism of your role?
I realized one thing at a point during these years: This was a change management process. In the beginning I never saw it that way. It took a discussion with a friend who had nothing to do with insurance but who happened to know a lot of insurers to clarify this to me, because he heard what insurers were saying. That woke me up and I realized that in fact I was organizing change management. Here was a sector that was active for decades without any supervision. There was some disposition in the law but it amounted to virtually nothing.

Then someone comes in and says we are starting to reorganize this issue. It is very difficult. Some people may feel threatened… There can be several processes within normality and we ended up in one process that, while not the most desirable was still a normal path: Confrontation. It could have been tough dialog but nonetheless dialog trying to convince [me], by showing data, where things failed or telling me where I am not seeing it clearly. But I think somewhere we were all growing; on both sides the visibility at times was not 100 percent.

A simple question: Do we want to bring in [the regulatory framework called] Solvency II in our region? This is for big sophisticated companies and complex insurance sectors whereas in the Middle East so far to a very high degree we have simple insurance. I think Solvency II as a framework is a beautiful thing but then we have to adapt and simplify it.

E  Solvency II has been criticized in Europe as being extremely complicated…
We cannot afford that. We need something that is understandable for the insurers and is feasible.

E  Would you say that there was a negative impact on Lebanese insurance companies from the fact that the law didn’t come into existence in 2004/2005?
Of course. The difference is between real loss and opportunities lost. Our human nature gives a very high weight to real loss, which could be $10. If you lose $1 million as opportunity cost, you may say ‘I am not sure if that would have ever come’. What we have here is a huge missed opportunity to grow the sector properly, to consolidate it properly and to show the region that we have serious companies that are well regulated.

The supervisor’s reputation of strength — and some companies realize that — is great publicity for the sector. This reputation is essential to the business of insurance companies. I wouldn’t say it’s free publicity because there is a cost to supervision, but it is publicity that you [as a company] don’t need to promote yourself. If you have a supervisor that has a reputation of being professional and capable of doing what he has to do, one who cannot be fought off easily, then you as an insurance company are seen as a very serious insurer.

November 3, 2011 0 comments
0 FacebookTwitterPinterestEmail
Finance

Treachery and trickery await online

by Executive Staff November 3, 2011
written by Executive Staff

The lure of an easy buck is tempting for many, and as online trading becomes ever more accessible in Lebanon there are many who are ready to put their savings on the table. As with everything that seems too good to be true, however, the pitfalls are plentiful and inexperienced traders will quickly find themselves prey to the sharks of the market.

The number of online brokerages in Lebanon has been steadily swelling in recent years, with four launched in 2011 alone. Banque du Liban (BDL), Lebanon’s central bank, has 13 registered financial brokers, of which nine have online services. Also offering online trading platforms are many of  Lebanon’s other financial institutions, including the major banks.

What online brokers offer investors is easy access to the financial markets and the opportunity to trade a wide variety of securities from anywhere in the world, through a desktop, laptop or smartphone.

“Everyone can have access to the markets and trade all types of financial instruments for as low as $500,” says Walid Abousleiman, chairman of Aksys Capital, referring to the standard minimum deposit required to open an online account. 

Mohammed al-Hamidi, managing director at AM Financials, says that for average Lebanese people without a large capital base to invest from, online trading can be a tempting way to make money.

Aiding the surge in online brokerage is the rapidly expanding access to Internet across the region. “When you look at the percentage of Internet penetration in various countries in the Middle East, all are on the rise and Lebanon is no exception,” says Karim Farra, chairman of Amana Capital. “The concept was proven elsewhere, with online brokers in the United States and in Europe flourishing, so there was less risk for online brokers in Lebanon as we are not reinventing the wheel.”

Size of the market

The foreign exchange market is the world’s largest, with an average daily turnover of $4 trillion as of April 2010, 20 percent higher than in 2007, according to a report by the Bank for International Settlements. The report reveals that the growth of foreign exchange trading is partly attributed to increased trading by retail investors, who account for $150 billion of the average daily trade total, or 4 percent of the forex market.

Taking into account the population of the Middle East and North Africa (MENA), its trading history and Internet penetration, as well as the lopsided market share of the US, United Kingdom and Japan, Farra estimates that just 1.25 percent of total global foreign exchange trades are carried out in the MENA, equating to $1.8 billion per day, or $470 billion per year.

“The potential for the MENA region is clearly there as we have to play catch up in market share to claim our rightful 5 percent share,” says Farra.

An interesting perspective put forth by Henri Chaoul, general manager of Master Capital Group, is that the significant amount of liquidity sitting idle in Lebanese banks has contributed to the increase in the number of online brokers. According to Chaoul, Lebanese banks hold between $20 billion and $25 billion of ‘risk capital’ — money investors are willing to play the markets with.

“Banks have been very slow to react and provide products for [the excess liquidity]; as a result, finance companies have mushroomed because they want to take that opportunity,” he says. However, Chaoul is concerned about the lack of development concerning the financial products offered: “You don’t get any degree of sophistication. For instance, there is hardly any asset management.”

Jamil Barrage, head of asset management at financial institution Levantum, agrees on the lack of sophistication in the market. He says he tries to offer clients long-term investment advice, but encounters many who prefer much shorter horizons.

“‘Should I buy gold? I want to make a quick buck’,” says Barrage, mimicking these clients. “Their mentality is geared towards instant gratification and trading and they want to win now.”

Every online broker Executive spoke to for this article said the vast majority of traders in Lebanon, and the wider MENA region, are speculators, looking to make a quick buck rather than invest for the long-term.

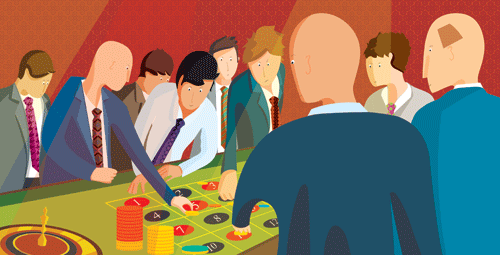
“They gamble and they like it,” says Chaoul. “The more you gamble, the bigger your bet is and the higher the risk that you lose. Think about the casino. When was the last time you went to the casino and made money?”

Online brokers note that the average retail investor lacks market experience and so tends to lose money, while experienced traders generate better returns as they perform in-depth analysis of the securities traded and have superior market awareness.

A leverage-powered casino

In Lebanon, clients are typically offered 1:100 leverage on forex, meaning that for every $1 deposited the client can trade up to $100. This significantly raises the risk of being wiped out quickly.

Say a trader wants to buy euros and sell dollars. He opens an account with $5,000 and his broker gives him 1:100 leverage, so he can trade up to $500,000. If the euro/dollar exchange rate stands at 1.36, he can buy €368,000; if it falls to 1.345, his €368,000 is now worth $495,000, meaning he has lost $5,000 — or his entire investment — for just a 1 percent change in the euro/dollar.

“If you take on too much leverage with a small account, you cannot hold positions, you are obliged to [exit],” says Marwan Riachi, senior financial consultant at Berytus Capital.

The US imposed rules last year to reduce leverage at US Forex brokers to 1:50 on major currency pairs and 1:20 on minor currency pairs. No such regulation exists in Lebanon and some online brokers offer leverage up to 1:400. According to Rayan el-Annan, chief executive officer of Royal Forex Trading, “stricter leverage rules, like in the US, would be very good in general to protect people from assuming more risk than they can handle.”

Given that clients are frequently wiped out, online brokers have to constantly be on the lookout for new ones. “Online brokerage is a very inefficient business model as you have to constantly get new customers,” says Chaoul. “If you are living in the US or Western Europe, there are plentiful amounts of clients. The problem here is that the number is limited.”

The darker side

Among the reasons for the rapid rise in online brokerage is that it has proven lucrative, but revenues do not stem from commissions alone.

It is a popularly cited statistic in the brokerage industry that 90 percent of retail investors lose their money; many online brokers in fact count on this to fatten their pockets.

The role of an online broker is to execute trades for clients in exchange for a commission. A widely understood practice in Lebanon, however, is for brokers to place their clients’ orders on their books and not send them to the exchange. These brokers are betting that the majority of their clients will lose their deposited capital, which is a form of market making prohibited by the BDL.

“What is happening in Lebanon is mind-boggling,” says Barrage, who describes an encounter he says he had with a salesman. “He asked us how many of our customers make money. When we said, ‘just a few’, he replied, ‘You see how much money you could have made if you had taken all these positions onto your books.’”

“It is the Wild Wild West,” he adds.

According to Chaoul, some online brokers will say “X is a stupid trader so we won’t send their trades to the market as we expect him to lose; so we will trade against him and hold the trade on our books.” In this case, when the trader loses money, the broker does not just take the commission on the trade, he takes the entire amount initially deposited by the client for the trade. The risk is that the trader makes money, in which case the broker will have to pay him from his own account. If they face a smart trader, then they will send the order to the market.

Rawad Halawi, head of Halawi Investment Trust — which focuses mainly on South Lebanon — says his firm faces competition from several unregulated online brokers, which offer very low commission fees.

“They must be winning something. They are relying on the loss of the client — that’s the source of their income so that’s why they can lower their commissions. They are killing the market,” he says.

Holding traders’ positions on their books is not the only shady business online brokers are up to. When a trader buys a contract of gold from his broker, that broker is meant to place that order with the appropriate exchange, which will require a margin from the broker as a buffer. For instance, the current margin required by the Chicago Mercantile Exchange for a contract of gold is $11,475, and that is a fixed amount required from any investor who wants to buy a contract of gold.

In Lebanon, some brokers are ignoring the margin requirements of the exchanges and asking for lower margins to induce the clients to buy. “If the exchange requires a margin of $6,000, they will give it to you for a margin of $1,000 and they will not send it to the market,” says Chaoul. “At best it is deceptive marketing, and at worst it is fraud, and it is happening all the time.”

What is not generally realized is that when a client buys a future contract on the popular platform MetaTrader4, which is used by the vast majority of brokers in Lebanon, the order goes to the broker and not directly to the exchange, meaning the broker is doing the execution.

According to Nusseima Taleb from BDL’s legal department, the central bank is aware of these issues and is trying to curb them: “We require reports from brokers and we monitor them onsite. If they are not abiding by the law, we take the necessary measures. If their breach is serious, we can close them down.”

When asked about plans for issuing a license for market making, she replied that “it is just talks for now,” and that there are no concrete plans to issue such licenses as yet.

Looking ahead

“Online brokerage in the Middle East is still in its infancy and it is going to grow tremendously,” says Hamidi.

The number of online brokers setting up shop is a reflection of the expectation of growth in this industry, and while the ease of access to the financial markets is a step in the right direction — allowing investors in Lebanon and the MENA to have the same investment opportunities available in other parts of the world — traders should tread with care to avoid pitfalls in the perilous world of online trading.


Sidebar: Picking an online broker

With the rise in the Middle East of brokerage firms dedicated to online trading, Executive helps you ask the right questions when choosing your online broker.

What service do you need?
Online brokers differ in the amount of services they provide. So to decide which type of service you need, think about how experienced you are as a trader. If you have significant experience, you can go for an execution only brokerage. If you are not experienced enough, you will need a full service broker who will offer investment recommendations. Keep in mind that these services are usually not offered to small accounts and when offered, they come at a fee, sometimes embedded in the commissions. It is highly recommended to take courses related to financial securities before starting to trade. 

What securities do you want to trade?
Online brokers also differ in the amount of securities offered. Some brokers are specialized in particular securities while others offer several types. Deciding which ones to trade should be based on your understanding of the security and also on your risk appetite. For instance, trading future contracts is much riskier than trading equities. A typical future contract would provide you with a 1:100 leverage, meaning that if you open an account with $1,000, you can trade with up to $100,000. Equities, on the other hand, typically offer a 2:1 leverage.

What trading platform is offered?
Some brokers offer their own proprietary trading platform but most commonly they offer a third party platform such as MetaTrader4, JT Trader and CQG Trader. It is essential to become familiar with the platform before starting to trade. Most online brokers provide demo accounts so that you can practice before going live. Some also offer platforms for your smartphones and tablets — a feature worth taking into account if you expect to trade on the go.

What are the rates on different securities?
Online brokers charge different commissions for the various securities they offer. In most cases, these rates vary depending on the volume traded. You will need to ask what rate you will be charged based on the volume you expect to trade. Also make sure you ask about the “hidden” fees as some brokers might charge fees for closure of an account, an inactive account or the transfer of funds out of the account.

What is the minimum deposit required to trade?
When deciding to open an account, you need to ask what is the minimum deposit required. For trading of futures, in most cases there will be a margin requirement set by the exchange that online brokers abide by. For trading foreign exchange and equities, online brokers will usually require a minimum deposit to open an account; nowadays, this can be as low as $500.

Who are the correspondents?
Online brokers use correspondents, financial institutions that have access to markets and place trades on behalf of the brokers. Make sure to ask who the correspondents used are. The higher the rating of the correspondent, the more you can be assured that your money will not evaporate.

How good is their reputation?
Before deciding on an online broker, ask around. As there are still no professional reviews of online brokerages in the Middle East, you need to rely on word of mouth. Also try calling the customer service of the brokerage to check how quickly they respond, check if they have live chat and if their response is efficient and helpful. Visit the broker personally before you open an online account to make sure it feels right.

With the rise of Internet penetration throughout the Middle East and the ease of accessibility to trading financial instruments, online brokers have been mushrooming. Gaining an understanding of the various securities and making an informed decision on which online broker to choose is fundamental in order to reduce the risk of losing your investment.

November 3, 2011 0 comments
0 FacebookTwitterPinterestEmail
Economics & Policy

For your information

by Executive Editors October 24, 2011
written by Executive Editors

Low growth, higher debt

The prospects of a second-half economic rebound appear dimmer than ever as Lebanon rounds out the third quarter, with predictions for gross domestic product (GDP) growth in 2011 from several economic institutions looking grim. According to the Economist Intelligence Unit (EIU), the country’s economy will expand by just 1.3 percent, representing a drastic drop in anticipated growth, from 4.6 percent in April. The EIU maintained its 3.6 percent GDP growth outlook for 2012. The agency cited several reasons for the revision, including the usual political instability in the country and elsewhere in the region. The report stated that while it believed reforms would occur due to relative accord within the cabinet, they would be slow to take effect as corruption, patronage and an over-bloated public sector prevent further economic growth. Barclays Capital also predicted economic growth in 2011 to come in at just 1.8 percent because of spillover effects from the Syrian uprising and a weakening services sector. Barclays said that the deficit this year should stay at around 7.6 percent of GDP, but a 15 percent expected increase in expenditures next year will have a harrowing effect on debt dynamics as the predicted deficit widens to 8.5 percent. The International Monetary Fund  (IMF) also weighed in with a projected growth figure of 1.5 percent, granting Lebanon the honor of the 16th slowest growth rate in the world. The IMF said that in the region Lebanon would come ahead of just Egypt and Tunisia in growth rates. Standard Chartered Bank also revised its previous 3 percent growth forecast downward to 1.5 percent.

Lebanon a little less risky

Lebanon has marginally improved its risk profile, if only in comparison to the rest of the Middle East. According to Euromoney magazine, Lebanon ranked 82nd out of 184 countries in terms of its risk profile and 11th out of 20 in the region. The rank is a 10-spot improvement on the June 2011 global rankings and represents the biggest leap in the region. The rankings were based on six weighted indicators: political risks (30 percent), economic performance (30 percent), access to bank finance and capital markets (10 percent), debt indicators (10 percent), credit ratings (10 percent) and a structural assessment (10 percent). Political risk declined by 1.3 percent since June, while Lebanon’s access to bank finance and capital markets rating increased by a whopping 288.7 percent.

Sharpening the stats

In an attempt to partially rectify the endemic lack of credible and timely data, the Central Administration for Statistics (CAS), Lebanon’s public bureau of statistics, is launching a new project that will form the basis of economic projections for some time to come. Last month the CAS announced that it will launch the National Household Budget Survey for 2011, the first such poll since 2004. The survey will cover a sampling of 4,000 households in cooperation with the World Bank and will quantify several elements related to the social, economic and demographic development in the country. The results will help assess poverty levels and provide a basis for updating the weights on different products used in the compilation of the consumer price index, the main indicator of inflation. Moreover, the survey will give a more accurate and timely reading on labor and unemployment levels.

Subsidy deal staves off strike

A nationwide strike by public transport sector workers was called off last month after a late-night deal to implement a subsidy for the drivers, which was agreed to during the previous cabinet’s term but never implemented. The subsidy will be doled out once a month and will cover the equivalent of 12.5 jerry cans (1 jerry can = 20 liters) of gas to around 40,000 licensed taxi drivers, as well as to an undisclosed number of truck drivers. The subsidy will provide taxi drivers with a total of LL470,000 ($311.77) per month, and truck drivers will receive LL350,000 ($232.17) over the next three months. The move comes after a reduction on the gasoline excise duty by LL5000 ($3.30) in February to a total of LL4,530 [$3.02] per jerry can.

EEZ finally rubber stamped

After a long wait, the Lebanese government is one step closer to future offshore oil and gas exploration. Last month the cabinet signed off on the borders of Lebanon’s exclusive economic zone in the Mediterranean Sea, which was ratified by Parliament in August. The declared border puts the country at odds with Israel after the latter declared a different border demarcation earlier this year. The cabinet decision follows an agreement between Tel Aviv and Nicosia that adopted “Point 1” as the ending point for Israel’s proposed border with Lebanon, which starts in Ras Naqoura and ends 133 kilometers off the coast at an angle of 291 degrees. Lebanon also signed an agreement with Cyprus adopting “Point 1” but never ratified it in Parliament. The new law proposes an end point around 17 kilometers southwest of “Point 1”, which corresponds to Israel’s existing northernmost contract blocs — areas where oil and gas companies can come to explore and extract hydrocarbon resources. The difference of opinion has resulted in a disputed area of some 854 square kilometers and has fueled fears of potential conflict.

Improving irrigation

The ongoing issues over a lack of irrigation in Lebanon’s rural areas will be addressed after an agreement between the ministries of agriculture, energy and water, the United Nations Food and Agriculture Organization and the Italian government was inked last month. The agreement will see $370 million provided by the Italian government go towards the rehabilitation of outdated water networks. The project seeks to deliver water to about 15,000 hectares (150 square kilometers) over the next five years. Irrigation accounts for around 60 percent of Lebanon’s water demand.

EDL hemorrhages ever more

Transfers from the treasury to Electricité du Liban during the first half of the year came in at $684 million, a 22 percent increase on the first half of 2010, according to the finance ministry. The increase in transfers, said the ministry, is due to higher prices for fuel and increased payments to the Egyptian Natural Gas Holding Company (EGAS) for natural gas delivered via pipeline. Payments to Lebanon’s two fuel providers, the Kuwait Petroleum Corporation (KPC) and Algerian energy conglomerate Sonatrach, totaled $620 million, constituting 90.6 percent of payments, while $36.4 million, or 5.3 percent of payment, went to EGAS, with debt servicing accounting for the rest. According to the Finance Ministry, average oil prices increased for the first half of 2011 by 14 percent, along with a 10 percent increase in the quantity of imports.

Striking for a higher lowest pay

As a general strike planned for October 12, called for by the General Labor Confederation (GLC), Lebanon’s largest union, looms on the horizon, a report released by the consulting and actuarial firm Muhanna and Co outlined the effects of increasing the minimum wage to the GLC’s proposed LL1,250,000 [$829.18] per month from its current level of LL500,000 [$333.3]. The report outlined the potential consequences the increase could have on different sectors of the economy and found that the increase would raise labor costs the most in agriculture, with a projected 99 percent increase, though operating expenditure in the sector would rise just 15 percent. Other sectors would also be hit by rising labor and operating costs, such as banking and insurance (24 percent and 12 percent, respectively), construction (72 percent and 15 percent), education and health (72 percent and 36 percent), energy and water (32 percent and 2 percent), industry (67 percent and 11 percent), market services (49 percent and 29 percent), trade (64 percent and 26 percent) and transport and communication (44 percent and 9 percent). The report proposed that the minimum wage should be raised to 150 percent of the poverty line, or LL750,000 ($497.51) per month. The labor ministry has formed a committee to study the effects of a minimum wage increase while, as Executive went to print, negotiations with the GLC to avert the strike were ongoing. 

October 24, 2011 0 comments
0 FacebookTwitterPinterestEmail
Real estate

For your information

by Executive Editors October 24, 2011
written by Executive Editors

In District//S, size does matter

The developer behind the 22-building residential and retail community District//S in Beirut’s Saifi area has launched a new initiative to satisfy those looking for pied-à-terres in the city in September. The launch, at Lebanon’s DREAM exhibition in the Beirut International Exhibition and Leisure Center, unveiled the plan for 20 one and two-bedroom studios. The studio apartments will be fully furnished and serviced (cleaning, laundry, concierge service, gym access), with the local interior design firm Nabil Dada and Associates offering four schemes. All of the studios, ranging from 65 to 160 square meters, will be offered within one five-story building of District//S, according to Estates co-founder Anthony el-Khoury.  Namir Cortas, chief executive officer of Saifi Modern, owner of District//S and co-founder of Estates, told Executive that there could be more than 20 studios if there is more demand in the future. The price differential of the studios is about $1,500 more per square meter than the $7,000 per sqm starting price of other apartments in the development. “The price differential is our estimated cost for furnishing them and equipping them,” said Cortas. Studio construction is expected to be complete within four years, in line with the rest of the project.

DREAM goes green

London-based green-building consultancy firm, G, has partnered with 45 buildings in Lebanon to lead them to Leadership in Energy and Environmental Design (LEED) certification. Nader Nakib, chief executive officer of G, told Executive at the DREAM exhibition in Beirut that for the first time investing in green technology in Lebanon is worth it for developers. “The cost of going green for a first level certification is around 2 percent extra of the construction cost,” he said, adding “but the central bank subsidy allows for up to 45 percent of the construction cost at almost zero percent interest fee.” G is the LEED consultant for a number of developments in Lebanon, including Audi Plaza, Beirut Terraces, Beirut Waterfront, Beirut Harbor, Saifi 178, Verdun Hights, the ESCWA Building and most recently Saifi Gardens. In the District//S residential community, G will ensure rainwater collection techniques, the use of recycled material where possible and the use of environmentally friendly gases for ventilation and air conditioning systems. 

Real Estate branches out

Jouzour Loubnan, an environmental non-governmental organization working towards the restoration of Lebanese woodland, is partnering with both private developers and government municipalities to continue planting trees in Lebanon on government land.  Raoul Nehme, president of the organization, told Executive at the DREAM exhibition that, in addition to 38,000 trees already planted since 2007, the group hopes its partnership with developers like Estates and HAR Properties will mean an additional 35,000 trees planted this year alone. The programs with real estate developers, launched two months ago, mean that “for every meter squared built and sold, one meter squared of new forest area will be planted,” Nehme said. The 2011 budget for the group is $400,000 based on an average cost of $10 per tree planted. Phillippe Tabet, chief executive officer of HAR Properties, the developer behind the AYA building in Mar Mikhael and UPark building in Ashrafieh, said at the exhibition that HAR’s contract with Jouzour does not directly help sales but is still part of the group’s “dedication” to green building.

Rejuvenating Iraq’s housing stock

Iraq has the biggest shortage of affordable housing in the Middle East and North Africa (MENA) region after Egypt, with about a million homes needed to bridge the gap, according to a September Jones Lang LaSalle report for the MENA region entitled “Why Affordable Housing Matters”. The National Investment Commission in Iraq is to construct 1 million affordable houses, and up to 430,000 of them are expected to be completed by the end of the first quarter of 2012, according to the report.  In related news, Faleh al-Ammiri, under secretary of the Iraqi Ministry of Housing and Construction, told Gulf News in a September 16 interview that the National Housing Plan currently includes 30 projects where units are to be sold to nationals at cost price or below. He added that financing for real estate is still in its infancy: “We look forward to a time when the private banking system takes part in financing investment projects and the limited housing projects with the cooperation of the state’s ministries,” he said.

Jordan’s unpaid builders

Local contractors are owed $282 million by developers and public sector institutions, President of the Jordan Construction Contractors’ Association Ahmad Tarawneh claimed in September. Tarawneh told The Jordan Times that the gap would force contractors to lay off staff if payment is not received in the short term. He highlighted major Turkish developer GAMA, which is carrying out the Disi Water Conveyance Project, but claimed that other projects like Andalucia and Abdali Urban Regeneration Project also failed to pay local firms. “For the past two years, developers have been promising to pay their financial obligations to contractors, but nothing happened,” he said. In a September 12 statement to Construction Week Online, Yahya Kisbi, Jordanian minister of public works and housing, disputed the figures claiming the government only owes local contractors $70.6 million, with the Ministry of Planning and Internal Cooperations owing $29.6 million. In related news, an official at the Central Bank of Jordan told The Jordan Times in a September 13 article that the loans extended to the property sector reached 2.2 billion Jordanian dinars ($3.09 billion) by the end of July, or 12 percent of the overall deposits at local banks. Commenting on the figures, President of the Housing Investors Society Zuhair Omari said that the availability of this cash at the banks, coupled with the improved lending policies in the local banking sector, should galvanize the property market in the final quarter.

Riding the wave in Oman

Consolidated Contractors Company Oman, a subsidiary of CCC group, headquartered in Athens, has won the contracting tender to build the Omagine mixed-use development of residences, educational buildings, hotels and theme park along Muscat’s waterfront near Seeb Al Hail in Oman. The total cost of the project is $2.59 billion, which will see the US-based Omagine Inc. developers create an integrated touristic and residential area on more than 1 million square meters that will complement the upcoming The Wave touristic marina and retail center in the capital. A total of 2000 homes will be built around a marina, which will have an array of hotels and resorts ranging from three-star to five-star. The centerpiece of the development includes a cultural theme park that will feature exhibition buildings and an open-air amphitheatre. According to the Oman Daily Observer in a September 17 article, Omagine’s equity holding in the project is 60 percent, while newly formalized shareholders include the Office of Royal Court Affairs (25 percent), Consolidated Contractors Company SA (10 percent) and Consolidated Contractors Co Oman LLC (5 percent). CCC boasts a 120,000-strong workforce in the region and is already commissioned to several other projects in Oman.

October 24, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Lebanese capital markets

by Executive Editors October 24, 2011
written by Executive Editors

BLOM Stock Index (BSI)

Weighted effective yield of Eurobonds

Equity update

Persistent political unrest in the region and volatility in the international markets continued to have a negative impact on the Beirut Stock Exchange (BSE). The BLOM Stock Index (BSI), Lebanon’s equity gauge, followed a downward path between August 16 and September 16, 2011, to hit a 27-month low of 1,244 points. The BSI was down 4.7 percent on the previous month, extending its year-to-date retreat to 15.7 percent. The BSE witnessed a daily average volume per month of 182,811 shares, worth $1.71 million, during the four-week period of August 16 to September 16, as compared to 153,424 shares, valued at $1.74 million, over the preceding four-week period.

When compared to regional equity markets, the BSI underperformed the S&P Pan Arab Composite LargeMidCap Index and the Morgan Stanley Emerging Markets Index. The former inched up 0.3 percent to 107.3 points and the latter slipped 2.6 percent to 963.7 points as investors remained wary. 

During the period, banking stocks dominated on the BSE, accounting for 64 percent of the total value traded. BLOM Bank’s stocks witnessed a mixed performance, with its Global Depository Receipts (GDR) falling 4.4 percent to settle at $8.17 while BLOM listed stock advanced 2 percent to $8.19. Audi Bank’s GDR and listed stocks fell, with the former declining 5.2 percent to $6.82 and the latter falling 9.9 percent to $6.2, hitting their lowest level since the 10 to 1 split became effective in May 2010. Byblos Bank’s common stock retreated as well, inching down 0.6 percent to $1.65, whereas Bank BEMO stocks slipped by 6.2 percent to an all-time low of $2.57. Bank of Beirut’s  common stock reached a peak of $20 on September 9 before ending at $19.26 on September 16, still 1.4 percent higher than its close on August 12. With regard to preferred stocks, Byblos preferred 2008 and 2009 lost 0.5 percent each to align at $100, while Bank of Beirut preferred D and E declined by 1.6 percent each to stand at $26. BLOM preferred 2011 rose 1.1 percent to close at $10.11.

Real estate leader Solidere saw its market dominance decline. Solidere A and B stocks tumbled an average of 9 percent to a 28-month low of $15.15 and $15.30, respectively.

In the industrial sector, cement manufacturer Holcim’s stock reached its highest level since October 2008, peaking at $17.88 on September 8 before settling at $16.70, 1.3 percent higher than its close the month before. Ciment Blanc Class B hit its highest level since March 1998, touching $3.25, before declining to $3.07, though still up 3.4 percent from August 12, whereas Ciment Blanc Class N rallied 11 percent to $1.72.

Rasamny Younis Motor Company stocks fell 7.4 percent to a one-year low of $2.50. 

Eurobond bulletin

The Lebanese Eurobond market has been volatile over the month. The market witnessed some selloffs on long-term maturities, especially on the 2021 issue between the middle and end of August before it rebounded, boosted by higher demand from local investors on the long end of the curve. Thus, the BLOM Bond Index rose 0.3 percent to reach 111.24 points. Consequently, the portfolio weighted yield fell by 14 basis points (bps) to 4.8 percent, while the spread against the United States benchmark yield widened 7 bps to 404 bps. Lebanon’s five-year credit default swaps (CDS) — which vary positively with the country’s default risk — reached 395-425 bps compared to 361-391 bps on August 12. Comparatively, in regional markets, Dubai and Saudi Arabia CDS were quoted at 415-430 bps and 111-113 bps, respectively.

October 24, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Financial quotes of the month

by Executive Editors October 24, 2011
written by Executive Editors
Josef Ackermann, CEO of Deutsche Bank

“We should resign ourselves to the fact that the ‘new normality’ is characterized by volatility and uncertainty”

Mohammad Safadi, Finance Minister of Lebanon

“Looking forward it’s gloomy and at best, the economies will not perform. Far Eastern economies and third-world economies like Lebanon will keep on growing, but not as fast”

Sheikh Mohammed Bin Rashid al-Maktoum, ruler of Dubai

“Dubai is well”

Georges Soros, billionaire investorV

“The German public still thinks that it has a choice about whether to support the euro or to abandon it. That is a mistake”

Mohammad Jleilati, Syrian Minister of Finance, on the GDP growth of Syria

“Now, it will be around one percent, because of the events… maybe between one to two percent”

Angela Merkel, German chancellor

“We’re facing a challenge which one can call historic. If the euro fails, then Europe will fail”

Mohamad al-Jasser, Saudi Arabia’s central bank governor on the future of the common GCC currency

“The economic situation in our countries is excellent and nothing is delaying the currency”

Riad Salameh, Lebanon’s central bank governor

“Lebanon is immune to what is happening in Syria or worldwide because of the model we have, which is a highly liquid, prudent approach to credit and low leverage”

Jacek Rostowski, Poland’s finance minister

“The risk of all sorts of authoritarian political movements, and therefore even war, in the long horizon, rises”

October 24, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

MENA stocks tips

by Executive Editors October 24, 2011
written by Executive Editors

With the European sovereign debt crisis taking center stage last month, the United States economy still in tatters and uprisings continuing in parts of the Middle East, uncertainty prevailed in the markets. Surrounded by such volatility, what is a Middle Eastern investor to do?

For an expert opinion on how to navigate the markets, Executive spoke to Ammar Bakheet, head of asset management at Audi Bank, and Khaled Zeidan, general manager at MedSecurities, a BankMed subsidiary.

The scoop

Bakheet remains very conservative in his approach, as he believes that the market turbulence will persist at least until the end of the year. However, he sees significant opportunities in the current environment and recommends buying high quality, fixed-income instruments rated triple B or better, and big blue chip companies with high dividend yields. Zeidan also favors fixed-income and equities; he believes equities are very cheap and advises to buy defensive names — such as telecommunications and utilities — as they have been beaten down badly along with the growth sectors like technology. Both Bakheet and Zeidan say they would avoid gold. Bakheet believes buying gold now is a gamble, and Zeidan prefers investing in productive assets.

Both Bakheet and Zeidan are optimistic about the investment opportunities they see in the Middle East and North Africa. According to Zeidan, the interesting thing about the region is that it offers solid names with high dividend yields. Saudi Telecom Company (STC), as an example, is one of the largest telecom companies in the region and in emerging markets generally, and has had a consistent dividend yield of 7.5 percent on a currency that is pegged to the US dollar. Zeidan pointed out that this is better than buying a corporate or government bond as the yield is more attractive. His favorite regional countries to invest in are Saudi Arabia and Turkey, as both countries have solid growth, relative political stability and a young population. According to Bakheet, with oil prices still holding high, the region is raking in revenue and many infrastructure projects are being announced. His favorite MENA countries to invest in are Saudi Arabia, the United Arab Emirates and Qatar.

As for long-term stock recommendations, Bakheet suggests buying Mobily, the second mobile telecommunications company in Saudi Arabia. He would also buy Maaden, the largest mining company in Saudi Arabia. Zeidan on the other hand would buy leading Turkish banks due to the fact that their stock prices have been severely beaten down, yet they have great balance sheets and no exposure to Europe. He would also buy into the telecommunications sector in Saudi Arabia, such as Mobily and STC.

October 24, 2011 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

For your information

by Executive Editors October 24, 2011
written by Executive Editors

Gold boosts BDL assets

Total assets at Banque du Liban (BDL), Lebanon’s central bank, rose 6.2 percent in August to reach $72.75 billion, mainly due to an increase in the international price of gold. The value of BDL’s gold reserves increased by 12.5 percent to $16.75 billion, accounting for 44 percent of the rise in total assets. Lebanon plans to keep its gold reserves at around $17 billion as it tries to protect its economy from domestic unrest in neighboring countries, according to BDL Governor Riad Salameh. The central bank’s foreign assets (excluding gold) rose by 5.6 percent in August to $32.14 billion due to an increase in confidence in the Lebanese currency. On the liabilities side, private sector deposits increased 3.7 percent to $48.6 billion, while public sector deposits went up around 7 percent to $6.08 billion.

HSBC axes Lebanon branches and jobs 

HSBC is closing three branches in Lebanon, consolidating its network by half, not including its headquarters. The move is part of an ongoing global effort of the HSBC Group to “improve efficiency”. The bank plans to cut 30,000 jobs by 2013, which amounts to approximately 10 percent of HSBC’s total workforce. As well as the job cuts, HSBC is closing its retail banking operations in Russia and Poland and selling three insurance businesses as part of pre-announced plans to save $2.5 billion to $3.5 billion by 2013. HSBC recently sold 195 retail branches in the United States, primarily in New York, to First Niagara Bank for approximately $1 billion.

Lebanon moves up the global competitiveness ranks

Lebanon is ranked 89th in The World Economic Forum’s global competitiveness report for 2011-2012, up three places year-on-year. Qatar is the most competitive country in the Middle East and ranked number 14 overall, up three places from a year ago, followed by Saudi Arabia (17), which enters the top 20 for the first time and gained four places on the year before. The United Arab Emirates (27) fell two slots. The most competitive country in the world is Switzerland, followed by Singapore, which overtook Sweden for second position. Northern and Western European countries dominate the top 10.

Iran’s banking scam reaches Ahmadinejad

Several Iranian banks have been targeted in one of the biggest frauds in the Islamic republic’s history, losing nearly $2.6 billion over more than two years. The financial scandal involved the forging of documents to secure credit from various financial institutions, including Bank Saderat, one of the largest in the Middle East. The proceeds were then used to purchase state-owned enterprises, such as the Khuzestan Steel Company, as the government implemented its controversial privatization scheme, which began in 2004. Iran’s Minister of Economic Affairs and Finance Shamseddin Hosseini said on September 18 that the chief suspect of the banking scam had been detained but gave no further information. Kayhan, a conservative newspaper under the direct supervision of the Office of the Supreme Leader, identified the suspect as billionaire mogul Amir-Mansour Aria and alleged complicity on the part of President Mahmoud Ahmadinejad’s top ally, chief of staff Esfandiar Rahim Mashaei. Ahmadinejad denies Mashaei’s link to the scandal.

Growth forecast in Syria hit by ongoing unrest

The International Monetary Fund (IMF) cut its growth forecast for some countries in the Middle East and North Africa due to the continuing social unrest in the region and the volatility in the oil price. According to the report, “the outlook is subject to large downside risks”. Lebanon is expected to grow 1.5 percent in 2011 and 3.5 percent in 2012. For oil-exporting economies, the IMF expects a 5 percent growth in 2011 and 4 percent growth in 2012. Qatar will continue to lead the way, followed by Iraq (which has the highest growth forecast in 2012) and Saudi Arabia. For oil importers in the MENA, the forecast is grim, as the IMF expects average growth of 1.5 percent in 2011 and 2.5 percent in 2012. Syria has the worst growth forecast in the MENA region, as it is expected to contract by 2 percent this year (down from an April forecast of 3 percent growth) due to the more than six month uprising and European sanctions.

Qatar investing in Greek banks

EFG Eurobank and Alpha Bank, the second and third largest banks in Greece, respectively, are to merge with the help of Qatar. The merger will take place via an all-share swap with a 1.25 billion euro [$1.68 billion] rights issue, followed by a 500 million euro [$672.7 million] convertible bond to be covered by Qatar. Alpha will offer Eurobank investors five new shares for each seven they hold. The expected deal will result in the formation of the biggest bank in southeast Europe. Qatar, which already owns 4.5 percent of Alpha, will become the largest shareholder with a 17 percent stake in the combined bank. Banks are not the only assets in Greece that Qatar seems interested in. According to the Greek Reporter, the ruler of Qatar, Sheikh Hamad bin Khalifa al-Thani, is interested in acquiring two islands, including Scorpios, which was originally bought by Greek billionaire Aristotle Onassis and whose granddaughter is now looking to sell the land. But according to Theodoros Varikos, mayor of the region, the elder Onassis specified in his will that the island could not be sold. 

US targets Israeli banks

In its effort to pursue offshore tax evaders, the United States is now targeting Israel, as three of its largest banks are suspected of helping American clients evade taxes through their Swiss outposts. The banks targeted by the US Justice Department’s criminal tax division are Bank Hapoalim, Bank Leumi le-Israel B.M. and Mizrahi-Tefahot. The inspection of the three Swiss branches of the Israeli banks comes during a wide-ranging campaign by the Justice Department to force nearly a dozen Swiss banks now under scrutiny to pay collectively billions of dollars in fines and to admit to criminal wrongdoing.

October 24, 2011 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 361
  • 362
  • 363
  • 364
  • 365
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE