• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Levant

A tribunal’s legal tender

by Executive Staff April 9, 2009
written by Executive Staff

Justice should carry no price tag, but anyone who has received an invoice from their lawyer knows that justice is not cheap. In early March the Special Tribunal for Lebanon (STL) came into effect, pursuant to the request of the Lebanese government and United Nations Security Council (UNSC) resolutions 1644 and 1757. On the surface, the explosion that ripped through the heart of Beirut on February 14, 2005, may not seem worthy of a tribunal with an “international character” or the invocation of chapter seven of the UN charter. Indeed, such events are not uncommon around the Middle East and they have become almost synonymous with the regional political scene. Yet it was this event the lead to the death of the Western backed, two-time Lebanese Prime Minister and business mogul Rafiq Hariri.

The politics of paying

The tribunal is the legal successor to the United Nations International Independent Investigation Commission (UNIIC). As with almost any international mechanism seeking justice, the commission and the STL have been the subject of a great deal controversy. Allegations of politicization of the investigation and subsequent tribunal abound.

“There are always claims around every tribunal that there is some politicization because you only have to have the USA put money in and you will find that straight away people will say that there is politicization,” says Robin Vincent, registrar of the STL, in effect the chief administrative officer for the tribunal.

The total cost of the STL is still unknown because the first three years have been budgeted, but there is no set timeline for the completion of the tribunal. The principle reason for the open-ended nature of the STL is attributed to a clause in the mandate of the tribunal that can extend the court’s jurisdiction to “other attacks that occurred in Lebanon between October 1, 2004, and December 12, 2005, which are connected in accordance with the principles of criminal justice and are of a nature and gravity similar to the attack of February 14, 2005.” If that comes to pass, the current budget for the STL may also be extended.

“If anything should happen during the year in terms of activities being advanced, I have to respond,” says Vincent. “I am in a position where I can go back to the committee [the organ in charge of administrative decisions at the STL] and ask them to amend or revise the budget to provide me with more funds than those that actually exist.”

The funding for the STL is provided by voluntary donations from UN member states. The Government of Lebanon (GoL), currently led by the “pro-Western” Prime Minister Fouad Siniora, is obliged to pay 49 percent of the total budget allocated to the tribunal, a compulsion they have been keen to meet. The budget for the first year of the tribunal was initially set at approximately $35 million, to which the GoL made a down payment of 49 percent.

In November of 2008, the management committee raised the 2009 budget to where it stands today at $51.4 million, for which the GoL has already paid its share. The total amount of money received thus far towards the first year comes to around $62.6 million.

“We do have money over and above the budget of the first year,” says Vincent. If, however, the makeup of the Lebanese government changes as a result of the June elections and the country’s leadership becomes less willing to support the tribunal for political reasons, there is always the nuclear option. “If during the lifetime of the tribunal the funding situation becomes difficult then [the UN Secretary General] reserves the right to revert to the UNSC,” asserts Vincent.

The expenses of the first year will cover the logistical elements necessary for the initiation of proceedings, as well as the other activities of the tribunal. “The prosecutor [Daniel Bellemare] has made it very clear that he would see 2009 as still being a year where predominately there would be ongoing investigations,” says Vincent.

Today, there is still a small team in Beirut that is currently liquidating its operations, which are not funded by the STL but by the UN itself. Although the list of contributors ranges from Austria to Uruguay, the latter contributing a symbolic $1,500, perhaps the most notable facet of the list is that the countries that have contributed to the STL all come from the same political angle, thus prompting further accusations of politicization. The principal contributors to date are the United States ($14 million), Kuwait ($5 million), France ($4.5 million) and a collection of other “regional states,” who have chosen to “exercise their right to remain anonymous,” according to Vincent.

Prepping for trial

As of late March, the premises where the proceedings will be held are still under construction and are not expected to be ready until late 2009. Furthermore, the STL is still in the process of preparing the facilities to handle the logistics of holding the accused, housing the organs of the court and preparing the building on the outskirts of The Hague for a total cost of $8.8 million. As for year two of the STL and beyond, many of the existing donors have already been asked to commit money.

“Of course we have gone back […] to all the existing donors asking them if they could make a pledge for year two particularly and year three if they could do,” notes Vincent. “The difficulty is that, for most member states, their fiscal arrangements don’t always allow them to commit money, especially when there may be an election in the next year or when there is a financial crisis,” says Vincent. But there are those who look set to be in it for the long haul. “Hillary Clinton came out about a month ago and pledged $6 million on behalf of the US for year two. We don’t think that will be all, but its an indication from the US that they are committed.”

The commitment that will have to be solidified in the coming year is expected to go up even after the construction and logistical phases have been completed.

“I was asked to forecast figures for the second and third years and the figures that I came up with were $65 million for each of the next two years,” says Vincent. “We can see that is significant and around a 25 percent rise in our costs… is attributed to a predicted change in the prosecutor’s activities, moving from investigation to trial and there would be an emphasis on trial teams, which isn’t there at the moment.”

Currently the STL seems in a good financial position and liquid enough to fulfill its tasks. Moreover, it seems to have learned from the shortcomings of previous tribunals by shooting high in order to avoid future financial problems. Where the money comes from — and the politics of the matter — will undoubtedly be the subject of much discussion in the years to come. What is important, however, is that the STL retain its objectivity, regardless of what criticisms are leveled. That will be a difficult task to fulfill. But in the end, as Vincent affirms, “the tribunal can only be judged by its acts and not [its] words.”

Special Tribunal for Lebanon

Status of pledges/contributions (in $)

* Contribution outside the estimated budget: The Netherlands – rent of AIVD building: $5,362,776.00 per year
** Contribution to be 49% of annual budget
Source: Special Tribunal for Lebanon
April 9, 2009 0 comments
0 FacebookTwitterPinterestEmail
Levant

Fields of fallow

by Executive Staff April 9, 2009
written by Executive Staff

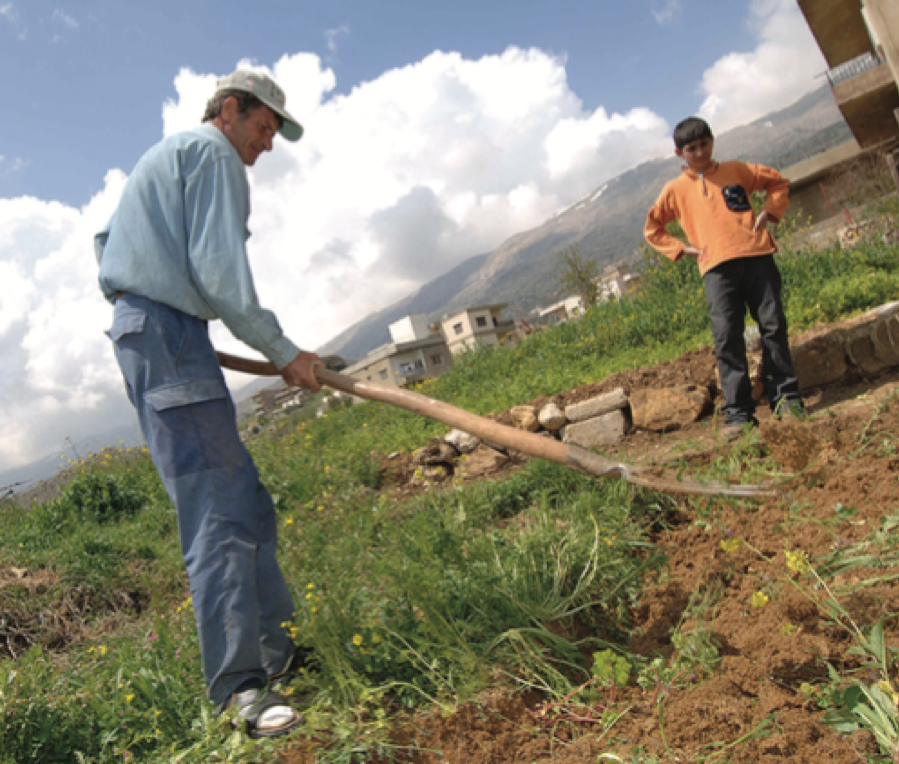
The Lebanese agricultural sector has been crippled by the lack of funds available to farmers and the scant attention given to training and education as urbanization increases. Neglect of this sector has proven to be an obstacle to the improvement of the social and economic betterment of many people living below the poverty line. Moreover, liberalization policies that are not backed by training schemes have actually worsened the status of farmers.

Farming in context

In 1995, the agricultural sector contributed to 12.4 percent of Lebanon’s Gross Domestic Product (GDP), which dropped significantly to 5.2 percent by 2008. Being able to claim self-sufficiency only in poultry production, Lebanon depends greatly on foreign aid and exports. It is no coincidence that the highest levels of poverty in Lebanon are in the same areas as those with the highest levels of agricultural production. These areas include North Lebanon, the Bekaa Valley and South Lebanon. Moreover, Lebanon has a high income inequality. Increased agricultural efficiency would enhance equity and minimize income disparities.

This concern needs to be taken into consideration given the efforts the Lebanese government is putting into entering the global economy and liberalizing its trade. Attempts to enter the World Trade Organization (WTO) and several other signed agreements will lead to the removal of trade barriers to imports. Behind this liberalization lays a threat to unsubsidized Lebanese farmers, who will have to carry the burden of low prices in order to compete with the products flowing out of countries where farmers are subsidized. Currency exchange rates represent a further burden. All of this indicates that a significant increase in agricultural productivity is needed; especially since Lebanon imports more agricultural goods than it exports.

Lack of capacity within the Ministry of Agriculture and increased urbanization are also blocking the growth of agricultural production. However, low export rates are mainly attributed to the low quality of products, which does not meet the standards of foreign importing countries. Although Europe is the prime destination for Lebanese exports, the producers are unable to meet the high quality standards European countries set due to high costs of production, inefficient institutional quality control or lack of knowledge and training. Moreover, Lebanon has lagged behind in the realm of technological development due to the various political disturbances and the marginalization of the agricultural sector within the successive governmental economic policies.

It is odd that these setbacks exist as Lebanon has the highest proportion of cultivable land in the Arab world, at almost 25 percent. Mismanagement comprises a great obstacle to growth. Farms tend to be small in size and there is very little attention given to the field. About 66 percent of farmers have second, nonagricultural jobs. Moreover, lack of cooperation and collaboration between farmers reduces efficiency.

Lebanon has high potential in the field of organic farming, however, the same obstacles stand in the way. Essentially, there is lack of knowledge and confusion over the definition of organic food, allowing people to confuse locally produced products with organic ones. Training local farmers to become organic growers will be a great challenge. Hence, it is essential that three aspects of the agricultural field be enhanced in order to improve the sector. These are human capital, information systems and financial support.

Policies to grow the agriculture sector

The Ministry of Agriculture can play a large role in enhancing the productivity, marketability, and efficiency of the agricultural sector in Lebanon. Primarily, it must conduct market-based research to identify the most convenient export countries for  Lebanese products. In addition, it must learn the standards and requirements relevant to each country. Accordingly, the farmers must be advised to specialize in the products that have a comparative advantage in the global market place. A shift to value-added products — in addition to sufficient training in the fields of manufacturing, product differentiation, quality control, health and safety — will surely improve the agricultural sector’s overall wellbeing.

Contributed by the Youth Economic Forum

April 9, 2009 0 comments
0 FacebookTwitterPinterestEmail
GCC

Tanking up with tax

by Executive Staff April 9, 2009
written by Executive Staff

At a time when oil prices are half of what they were a year ago, the retail price of gasoline in Lebanon has been stagnant or climbing. For example, in July 2007 when the price of Brent crude was around $78 per barrel, the government raised taxes on gasoline which pushed the price from $14.90 per 20 liters — the standard measurement for gasoline in Lebanon — to $15.64 per 20 liters. This is roughly the same price of gasoline in today’s retail market, at a time when crude sells at around $50 per barrel. Needless to say, this illogical development is confusing for the consumer.

In 1985, then Minister of Finance Camille Chamoun issued a governmental decree abolishing state subsidies on gasoline; so legally the subsidy was removed. However, the government has levied a tax on gasoline, which it increases or decreases at will. When the government decreases the tax, gasoline prices drop giving the feel of a subsidy.

Further exacerbating the situation is that most people in Lebanon rely on private transport. Lebanon’s approximately 1.4 million registered vehicles consume around five million liters of gasoline per day, according to Bahij Abou Hamzeh, president of the Association of Petroleum Importing Companies (APIC) in Lebanon.

Another factor experts in Lebanon point to is unfair competition. “There is an oligopoly controlling gasoline imports to Lebanon and this is the heart of the problem,” says Jad Chaaban, professor of economics at the American University of Beirut and acting president of the Lebanese Economic Association. “The prices are set by the Ministry of Energy in consultation with the APIC. When you have an oligopoly controlling an import sector you cannot pass on decreasing or rising prices with the same efficiency as when you have a competitive market.”

Collusion in a free market

For his part, Abou Hamzeh admits that the association does collude with the Lebanese Ministry of Energy, but insists that the market is open to anyone who has the means to set up the infrastructure.

“We regulate the market in cooperation with the ministry but we have to do it because it’s the only product in Lebanon that has a ceiling for the price,” claims Abou Hamzeh. “The government is setting the ceiling of the price on a weekly basis. This doesn’t mean we cooperate in order to monopolize the market; it’s not what we are after.”

Abou Hamzeh blames the government who earlier this year raised the level of taxes on gasoline to $6.35 per 20 liters of imported gasoline when the price of oil was at around $35 per barrel. Abou Hamzeh adds that the gasoline price ceiling, set weekly, is too low. “The government imposes a ceiling according to the international prices and a small margin to cover additional costs,” says Abou Hamzeh. “This margin does not cover our costs. We cannot continue like this; we are making a loss not a profit.”

Whether or not competition is fair, one thing does remains clear: that the government is making a lot of money. Most estimates are that government revenues from gas tax will increase this year to around $466 million as opposed to $199 million in 2008. On March 19, the Lebanese General Confederation of Labor Unions gathered in front of the Lebanese parliament to protest the high prices and taxes on gasoline and around 150 cars blocked one of Beirut’s main commercial districts.

Tax of necessity

The government, however, seems to have little choice when it comes to removing the tax, since it is already drowning in a sea of debt and in need of more revenue. Furthermore, according to a high ranking member at the Ministry of Finance who spoke on condition of anonymity, the government must keep the higher gasoline tax in place because it has already reneged on two of its other promises made to donors at Paris III: the five to seven percent taxation on bank deposits and the increase of Value Added Tax (VAT). The cherry on top may be that many in the government are reluctant to enact policy due to the upcoming elections in early June.

“When we protest the government tells you, ‘you are right but now we have to have the election’,” says Abou Hamzeh.

Whatever the reasons may be, for the immediate future it seems that the high gasoline prices and price fixing will continue. Once again it seems it will be Lebanon’s people and industries that pay the final price.

April 9, 2009 0 comments
0 FacebookTwitterPinterestEmail
GCC

Cityscape 2009

by Executive Staff April 9, 2009
written by Executive Staff

As April begins, so does the countdown for Abu Dhabi Cityscape 2009. Just a few weeks separate Abu Dhabi’s real estate developers, investors and market players from the capital’s most prestigious property show. Usually, Cityscape is where developers launch their multi-billion dollar projects such as high-rise towers, mixed-use developments and even entire new cities. This year, however, the definition has changed. Instead of bragging about their new projects, developers have to prove their resilience in the face of current market conditions. Experts will also have to demonstrate their understanding of the current situation and prove Abu Dhabi’s strong position. On the other hand, investors and end-users will be watching to see whether Abu Dhabi still represents a good opportunity for investment.

Cityscape Abu Dhabi will take place in the Abu Dhabi National Exhibition Center April 19 to 23 and will include a series of conferences and summits, during which 101 key speakers will be discussing the most important challenges and issues facing the property market. Moreover, three post-conference workshops will take place on the last day of Cityscape. In the first workshop, Louise Sunshine, chairwoman and CEO of Domineum will be tackling the global property solution in the current challenging economy. In the second, Oscar Marquez, a real estate master trainer at the Leader’s Edge Training will be discussing new marketing strategies. The third conference will be lead by Matthia Gelber, who will confer about how companies can become green and make money out of it. Additionally, Middle East Real Estate Awards will be held on April 19 at the Emirates Palace in the presence of 500 industry leaders, where distinctive projects that combine architectural excellence with eco-friendly solutions will be awarded.

The optimistic view

Marquez, who remains very optimistic about the real estate market in the Middle East, says that Cityscape will give people a lot of hope.

“People think that this is the end of the world, while it is not. Many investors will become aware [during Cityscape] of the big opportunities that are right now in real estate,” he explains. Moreover, Marquez also thinks that at Cityscape, developers will make up their mind on how much prices have to be reduced in order to keep the economy moving forward. “It is just a matter of time before [developers] realize that they can’t make 100 percent profit,” he adds. 

Other experts agree with Marquez, while saying that this year, the number of transactions that are going to take place will be minimal. Indeed, now more than ever investors are cautious about their investment decisions. They will likely consider Cityscape as a means to see how developers are progressing on their previously launched projects as well as the prices and payment plans that they are going to present.

Hussain Ali Al Shamkhani, chief investment officer at Escan Real Estate PJSC, says that Cityscape 2009 represents an opportunity for developers to show that they are still in the market and still going ahead. He explains that “developers should show the benefit of the demand-supply gap [in Abu Dhabi] and show people that instead of speculating, they can buy units and rent them out and make seven to eight percent return. [Developers] should sell that as the main benefit of buying a unit.”

Shamkhani also adds, “they need to emphasize and explain the potential of Abu Dhabi, how it is very different from Dubai and why it is much safer and more profitable. I think this should be the theme for the show and this is the best message to get across.”

IIR Middle East, the organizers of the event, introduced the first Cityscape Connect breakfast recently, where 150 real estate and property stakeholders met to increase confidence in Cityscape and the market in general. At the breakfast, Sami Eid, Aldar’s senior marketing manager, said “it’s one of the biggest events and we’ll be showcasing ourselves and showcasing Abu Dhabi… We won’t be unveiling anything new but it’s important to be out there and we’ll be showing all our projects.”

This statement is likely to apply to all developers who are considering Cityscape a chance to prove themselves as well positioned to face the current turmoil. Since early February, 95 percent of the exhibition stands were booked, Cityscape organizers asserted. They added that 40 percent more floor space has been sold than last year. Moreover, attendance is expected to increase up to 27 percent from 35,000 during Cityscape 2008.

Real estate stakeholders are looking forward to this year’s show, waiting to see what Abu Dhabi has to offer. Consequently, Cityscape 2009 has a hard task to meet, since it will have to prove that Abu Dhabi is still, despite the current market turbulence, one of the most attractive destinations for investment in the Middle East.

April 9, 2009 0 comments
0 FacebookTwitterPinterestEmail
GCC

Private equity – Stacks of dry powder

by Executive Staff April 9, 2009
written by Executive Staff

Big or small, PE firms in the Middle East are faring much better than most other financial institutions in the region, despite the amount of “dry powder” — i.e. capital called or committed that is yet to be deployed — in the area. Nevertheless, sitting on a mountain of cash and not spending it because you don’t like what you see is more enviable then struggling to pay off your creditors.

The phenomenon of dry powder is not just an effect of the financial crisis and the ensuing downturn, which started to take effect in the last quarter of 2008. Investments by PE firms began to make an about-face around the beginning of 2008. PE investments over the whole of 2008 saw a significant decrease in both number and size year-on-year by 22 and 31 percent respectively, the principle reason for this being that private valuations still seem to be out of touch with public market perceptions.

“At the moment, valuations are generally too high so PE firms are saying ‘give us another six to nine months for them to fall,’” says Robert Hall, head of transaction services Middle East & South Asia at KPMG.

Hisham El Khazindar, managing director and co-founder of Citadel Capital, adds that “in the grand scheme of things valuations across the board are 70 percent of what they were two years ago.”

When the region’s PE firms will start to sprinkle their powder around will, for the most part, depend on how long it will take owners’ willingness to break away from their egos and admit that they are in trouble.

“A contraction is taking place, but certainly we are not seeing the valuations that are in the public sector. We are not in a situation where we see distressed shareholders who are willing to sell at any price,” Christophe de Mahieu, co-head at Gulf Growth Capital at Investcorp, said to The National.

Yahya Jalil, senior executive officer and head of private equity at The National Investor in Dubai, remarks that, “it’s a little bit of an ego thing to admit that things have gone bad; this region is not known for being forthcoming as people like to contain their problems.”

Overcoming egos aside, many shareholders and owners don’t see the point of going into the market.

“People who have been in the market for 20 to 25 years see the blip in the market as very temporary, so they are thinking: why should they off a portion of their equity at these valuations,” says Jalil.

Ammar Al-Khudairy, managing director and CEO of Amwal Al Khaleej Investment Co., says “one private consumer goods company said to me, ‘I brought in one of the big four, they did a valuation for me and said my company was worth $100 million back in August [2008] and nothing has changed since. I sell no less if not more and, in fact, my cost of raw material has come down. So why should I sell for less than 100?’”

The stalemate that is brewing between firms and investors doesn’t seem to be going away anytime soon and it remains to be seen if the same understanding with regards to delaying capital calls will be extended to the firms for much longer.

Stressed out

The possibility of distressed or mezzanine funds is something that many in the industry are starting to look at as a result of the trauma being suffered by many regional organizations. Significantly, the Dubai Financial Services Authority (DFSA) wants the Dubai International Financial Center (DIFC) to consider establishing the Gulf’s first private equity secondary market. This could provide a respite for many PE firms looking to rid themselves of their dry powder.

“The whole issue of distressed assets in this region hasn’t been fully experienced in previous recessions. If you look at what the ‘ultimate’ distress is, which is a company becoming insolvent and unable to pay debts as they become due, then you really haven’t seen much of that yet,” says Hall. “In the recession this time around, the economy is much bigger and there are undoubtedly going to be some companies that will have significant problems. For PE firms this will provide some great opportunities.”

However, for the time being things don’t look that bad and the omnipresent attitude in the region today is not one of going after high risk and high return opportunities.

“Mezzanine capital is definitely more expensive than traditional forms of capital and it works well when valuations are improving and in upward cycle,” says Tamer Bazzari, deputy CEO of Rasmala.

Jalil says, “in the long term mezzanine is a huge unmet need in the region, but for the next year or two I think that, relatively speaking, it is not going to be interesting for investors — the risk profile between mezzanine and secured is night and day.”

April 9, 2009 0 comments
0 FacebookTwitterPinterestEmail
GCC

Quick & lean

by Executive Staff April 9, 2009
written by Executive Staff

With the financial crisis at hand the question is: what are businesses going to do about it? The response many businesses in the region have is to look inwards and improve internal business processes in order to hold down the fort until the onslaught subsides. The next and perhaps more important question is: how will regional businesses restructure their organizations?

Despite the dismal undertone of the business news coming out of the region, there are a few encouraging signs. One sector that is doing surprisingly well as a result of the need for businesses to restructure and improve efficiency is the Enterprise Resource Planning (ERP) industry. According to the International Data Corporation (IDC), ERP growth within the GCC will range between nine and 12 percent, an enormous figure considering many regional states will not grow at all this year.

“We will probably have the best month we have ever had this month,” says Bill Tomlinson, general manager of Dynamic Vertical Solutions, a multinational Microsoft partner that specializes in vertical add-on solutions to Microsoft Dynamics ERP platforms.

Much of this anomalous growth results from owners and managers  realizing that ERPs can increase efficiency for them.

“Before the crisis there was more time and more money,” says Sergio Maccotta, managing director of SAP Middle East and North Africa. “Now companies are taking the opportunity to change, through IT adoption, in order to improve their internal processes.”

The industry itself is also experiencing a paradigm shift in relation to its operating environment. Before the crisis, many regional businesses were hesitant to adopt standard ERP processes, opting instead to fit the system to their businesses or not to adopt one at all. Today, however, the tables have turned.

“What we are seeing that we didn’t see before is that many of the upper to mid-market organizations are coming to us, while we used to go to them and try to prove our solutions,” says Tamer Elhamy, regional business solutions manager at Microsoft Gulf.

What’s on offer?

The ERP companies in the region are increasingly being queried about how their systems can help companies save on the more costly elements of doing business and keep in touch with their customer base.

“People want to manage their [human] resources a lot better now so they are looking for payroll and HR solutions more than ever,” explains Tomlinson. Maccotta adds that, “the money in the market is lower, so in order to secure your portion you have to execute better and stay closer to your customer.”

It should be noted that internally, ERP solution providers are also benefiting from some of the more sinister effects of the global downturn, such as rising unemployment, decreasing real estate valuations and weakening currencies. Although there has been “no drastic change,” according to Maccotta, in the resource pool for providers, there has been a decrease in the acquisition and retention costs of consultants for providers. “The [Indian] rupee rate is at 51 to the dollar, whereas it used to be 39 to the dollar and that cuts 25 percent of cost because I am on dollar fixed,” says Tomlinson. “Another benefit of the crash is that all the rents are down by about half, so if you want to bring in some big people for a project then you can do it cheaper and it’s making our job easier.”

The argument within the industry, however, is centered around the size of the solutions on offer.

“Many of the customers are deciding to adopt an ERP to increase their efficiency but they are trying to start with the minimum number of users and functionalities and taking a step-by-step approach,” says Elhamy. That approach is prompting many people in the industry to predict that smaller and less expensive ERP solutions will be the trendsetters in the future.

“In the global scheme of things, SAP and Oracle’s figures are down because they are too expensive. People are more cash conscience now and are actually exposing the product for what it is,” claims Tomlinson. Perhaps unsurprisingly, that assertion is being bitterly contested by the larger and more complex solution providers.

“I don’t agree when you say we are more expensive because our solution is extremely flexible, as well as scalable, and can fit any kind of business,” counters Maccotta. “We still see a lot of demand and having the vertical competence is putting SAP at a competitive advantage.”

“In order to secure your portion you have to execute better and stay closer to your customer”

April 9, 2009 0 comments
0 FacebookTwitterPinterestEmail
GCC

Much tilling without harvest

by Executive Staff April 9, 2009
written by Executive Staff

Last year food was big news as prices soared globally by 54.9 percent and associated riots erupted in 60 countries. In the Arab world alone the shortage in food sufficiency was estimated at $18 billion by the Arab Authority for Agricultural Investment and Development (AAAID). In the Gulf countries, dependent to the tune of $12 billion a year on imports and with agricultural water consumption at unsustainable levels, the issue took on grave importance. State and private investors promptly started eyeing up arable land in Africa and Asia to secure food for a region that is expected to increase import dependency to 60 percent by 2010, according to the UN’s Food and Agriculture Organization (FAO).

But while food prices and commodities have reduced in the wake of lower oil prices and the global financial crisis, the issue of food security has not gone away. However, it has yet to be seen whether all the touted agribusiness projects will take off as Sovereign Wealth Funds (SWFs) and private investors tighten their belts in the face of the global economic slowdown.

The big issues

The Arab world’s population ballooned 121.9 percent between 1975-2005, while over a similar period, 1980-2004, the region’s food grain and meat production increased by 93 percent.

The shortfall was not overly concerning given access to the free market and that staples such as wheat and rice were fair cheap, at least affordable enough for governments to subsidize. Additionally, countries such as Saudi Arabia, Syria and Iraq were involved in large-scale agricultural projects to boost domestic production.

Saudi Arabia, for instance, spent a staggering $85 billion on agricultural development between 1984-2000, according to estimates by Elie Elhadj in The Middle East Review of International Affairs.

But the cost of such investment has gone beyond budgetary concerns. It is worth noting that while Saudi Arabia was paying up to $500 per ton for domestically produced wheat — when international market rates were around $120 —  to maintain local agriculture some 300 billion cubic meters of water was used between 1980-1999, two-thirds of it non-renewable, says the Ministry of Agriculture and Water. Such a gigantic amount of water was needed to grow produce in the kingdom’s arid climate, which is two to three times more water than required in a temperate climate.

After investing an estimated $16 billion to $18.7 billion over the last 30 years on its wheat program, according to BMI, last year Riyadh decided to phase out production due to water shortages. The costs versus the benefits were no longer sustainable, having been self-sufficient in wheat since the 1980s when production hit 4 million tons per year, Saudi Arabia is now a net importer and as of 2016 it will be totally dependent on imports. Furthermore, with Saudi Arabia joining the WTO, the kingdom has to abide by the organization’s requirement to reduce state support for agriculture to 13.3 percent over the next decade. This will have other knock on effects, such as on the 12 percent of the workforce involved in a sector that accounts for just 3.3 percent of GDP.

The region is losing an estimated one million hectares of arable land each year to salinity

Saudi Arabia is not the only country re-thinking its agriculture policies, with the region losing an estimated one million hectares of arable land each year to salinity, according to Dr. Shoaib Ismail, a halophyte agronomist at the International Center for Biosaline Research (ICBR) in Dubai.

“Twenty years ago there was good quality water everywhere. Now there is one-third seawater concentration in the groundwater and salinity is even higher in other places. Mismanagement has led to more salinity,” said Ismail. “Some 85 percent of water usage in the GCC is for agriculture, the highest in the world. In that sense, the question arises, how feasible is agriculture over here?”

The short answer is that it isn’t. Even producing processed foodstuffs for domestic consumption and export requires water, what has been called the “export of virtual water” and it may have to be re-thought given looming water constraints.

One solution is to use halophytes, plants that grow under high saline conditions, as opposed to glycophytes, non-salt loving plants, an alternative with which the ICBR is involved. But while halophytes could be used to replace more water intensive plants and trees, those plants would not produce adequate amounts of food. It is in landscaping, which accounts for 18 percent of water use in the UAE, that plants and non-conventional grasses can be advantageous, according to Ismail.

Oman is developing a salinity plan and it has invested in a project to clean water from the oil industry, because for every barrel of oil pumped out of the ground seven barrels of water are used. The UAE has also developed a ‘Master Development Plan’ to assess water usage and improve efficiency, such as changing irrigation systems, phasing out subsidies and expanding water pricing to include agriculture and industry.

Desalinization is another touted panacea for the region’s water concerns, but costing between $0.81-$1 per cubic meter, desalinized water is too expensive for agricultural use.

“Building new desalination plants is not the solution, as this warms up the sea and affects marine life,” said Ismail. It also increases the sea’s salinity.

Rich countries trying to secure land overseas risk creating a ‘Neo-Colonial’ System

Eyeing pastures new

With wheat prices rising 83 percent last year and other staples doubling in price, governments started eating into their reserves to placate populations which were spending ever-larger proportions of their income on food.

In Pakistan, the NGO Oxfam reported that, due to food inflation, the number of poor has risen from 60 million to 77 million since 2007, while in the Arab world the AAAID predicted some 35 million people were falling into poverty due to high food costs. As the region has an overwhelmingly young population and high population growth, food security is paramount.

For the GCC, the surge in food prices didn’t push people under the poverty line, but it was a contributor to inflationary pressures. And with the population expected to double by 2038 to 60 million people, demand for food will continue to grow at a rapid pace. Saudi Arabia, the Gulf’s most populated country, already imports some $5 billion per year of food and beverage items, according to BMI, and that will figure will spike in years to come.

“Food security is officially defined not just as a shortage, but also looking at availability and affordability,” said George Attala, a principal at Booz Allen Hamilton. “There are a number of ways to ensure supply is always available. One is try and diversify sources, not all wheat from say, Ukraine. Another is look at internal networks, such as imports through more than one port. A third way is storage capacity, of four to six months, while the fourth is to get into contract farming, but that is not always the best solution.”

Essentially, the Middle East is left with two choices. “The region has to import. The question is, invest abroad or rely on the free market?” said Dr Eckart Woertz, program manager in economics at the Gulf Research Center in Dubai.

Last year, Arab states appeared to be opting for the first choice in the face of high food prices, with government missions from Saudi Arabia, the UAE, Qatar, Kuwait, Egypt and Libya visiting Pakistan, Ethiopia, Cambodia, Uganda, Angola, Kazakhstan, Ukraine, Thailand and the Philippines to discuss the possibilities of buying up arable land to cultivate. The private sector also got in on the act, with the likes of the Emirates Investment Group, Abraaj Capital, Al Qudra Holding and the Bin Laden Group reportedly acquiring land in Sudan and Pakistan.

But such policies are not always popular and they are also not necessarily dependable in the long run.

“For the GCC it is a ‘pros and cons’ situation. In the short term it is profitable to buy or lease land, but it also depends on the geopolitical situation. A country may be a friend today, but might not be tomorrow, so it is a dependency issue,” said Ismail.

Last year, the FAO warned that rich countries trying to secure land overseas risked creating a “neo-colonial” system. The concerns were related to Gulf investments in Sudan where only indigenous water and land were used, whereas fertilizer, seeds, equipment and labor came from abroad. It was a similar story in Pakistan.

As Woertz remarked, “the negative case is bribe an African official, then expel locals and pastoralists, so no benefit for the local population at all. There is political baggage.” Furthermore, he added, “the GCC doesn’t have a good track record of labor rights or the environment and these need to be taken into consideration.”

And while the countries being courted may be interested in foreign investment, they also have to feed their own populations. Sudan, for instance, has an estimated 200 million acres of fertile land, yet only 20 percent is being utilized. However, despite 160 million acres of available arable land, the country is importing two millions tons of wheat per year and five million people are dependent on food aid. Similarly, Pakistan is facing problems in feeding its population, as well as losing groundwater to salinity.

But although there are many reports on plans to buy land, there has been minimal information coming forth about these projects, with “transparency limited to media accounts,” said Woertz. “They announce it — billion dollar deals — but it is unclear whether it has taken off and how the private sector has been brought in.”

An additional factor is that discussions to acquire land overseas were began when oil and food prices were higher. “The urgency is not there now and there is less money to throw around,” said Woertz. “The SWFs lost money in the markets and have less revenues, so [acquiring land abroad] may not be such a widespread phenomenon as made out.”

April 9, 2009 0 comments
0 FacebookTwitterPinterestEmail
GCC

Park sales to pump service

by Executive Staff April 3, 2009
written by Executive Staff

The UAE automobile sector saw sales plunge by up to 45 percent in the first two months of the year compared to 2008, a remarkable downturn from the years of double-digit growth when the $3.6 billion sector was one of the fastest growing in the world.

“The end of the third quarter 2008 was vastly different from the fourth for manufacturers,” said Mike Devereux, president of GM Middle East. “This year we are looking at a decrease overall, with the same daily sales rates since December to now.”

But while the economic slowdown has started to bite, the sector is not sitting on the sidelines until a recovery starts. It has resorted to a change in financing strategy and a greater focus on services to shift units as access to credit tightens and consumer preferences change.

“The financial crisis has certainly affected automotive sales in the UAE, with banks applying more restrictions on financing. And since nearly 80 percent of the UAE’s automotive sales are dependent on financing, this is more evident locally,” said Waldo Galan, managing director of Ford Middle East. Ford, Lincoln and Mercury sales grew 35 percent last year.

As a result of tighter lending, manufacturers and dealers are teaming up with banks to offer zero percent interest on car purchases and making credit more readily available to customers. The most notable change in sales strategy has been the widespread introduction of leasing, a technique dealers had formerly eschewed as car prices were low and customers preferred to buy.

“Financing is a problem so schemes have to be more tactically focused. Screaming the price from the rooftops is not what it’s about, but customer issues. The change is more tactical and less general as there is too much on people’s minds,” Devereux pointed out, adding that: “Lots of people want vehicles but need financing, so we’re focusing on a partnership with the National Commercial Bank (NCB) in Saudi Arabia and in the UAE a car leasing scheme.”

In with the new but not out with old

While enticing customers into showrooms is one concern for the manufacturers, so is keeping dealerships afloat, having ordered vehicles months in advance that can now not be sold or re-exported elsewhere. This has been further compounded by 2009’s models now being on sale, yet there is excess stock of last year’s lines.

“Credit, wholesale finance and bank loans are difficult for dealers. Stock levels for dealers mean reduced working capital so less money in the inventory,” said Devereux. “We will winnow down our inventory and import much less cars.”

And while there is an excess of unsold cars, manufacturers are hesitant to offload vehicles in fleet deals and government tenders.

“We’re trying not to chase unprofitable fleet tenders that we would have done before, as there is little to no margin,” said Devereux. “We are now focusing on the retail business, with 65 percent retail and 35 percent fleet.”

Consumer preferences are also expected to shift towards more competitive fuel efficiency, fewer SUVs and more crossovers.

“While demand for luxury vehicles would possibly see a reduction, quality and value would still remain on top of the consumer’s list,” said Galan. “We believe that consumers will act more out of a rational mindset and look for quality and value for money rather than the emotional drive.”

After sales is a another area manufacturers and dealers are focusing on as sales stagnate — a sector valued in the Middle East at some $11 billion, while the UAE tire trade is valued at $1.1 billion and slated to grow this year.

“There is a big focus now on services, which will be a stable haven in a downturn. Most dealers here are under invested in service capacity and the number of vehicles has increased so quickly,” said Devereux. “There is a need to invest in new services as vehicles are coming into prime servicing years after 2-3 years since purchase.”

While manufacturers continue to monitor the local environment, they are optimistic that revenues will go up next year as supply and demand align, even though it might not be the double-digit figures of the boom years.

“There is a big focus now on services, which will be a stable haven in a downturn”

April 3, 2009 0 comments
0 FacebookTwitterPinterestEmail
Finance

Islamic banking – Sharia by the books

by Executive Staff April 3, 2009
written by Executive Staff

Islamic banking is regarded as the fastest growing segment in the banking sector with a growth rate of 20 to 30 percent per year recorded over the past decade. With more than 390 Islamic banks in over 75 counties, this segment offers products and services compliant with the sharia that is the backbone of Islamic religious law. As a large percentage of the world’s Muslim population are located in the Middle East and North Africa region (MENA), it is logical that this region accounts for nearly 56 percent of total Islamic banking assets. The top three Islamic banks, Al Rajhi bank (KSA), Kuwait Finance House (Kuwait) and Dubai Islamic Bank (UAE) are all located in the MENA region. Since this sector is still in its early stages of development, with market opportunities yet to be exploited, estimates about the size of the industry still differ.
The International Monetary Fund (IMF) estimates total assets of Islamic banks in the world to be $250 billion and they are expected to reach $1 trillion by 2016. Conversely, McKinsey, a consulting firm, and Euromoney magazine are more optimistic as they expect total assets of Islamic banks to reach $1 trillion and $2 trillion, respectively, as early as 2010. In addition to geographic expansion, Islamic banking is also witnessing expansion in the financial services it offers, including retail banking, insurance and capital market investments.
Contrary to popular belief, Islamic banking does not target Islamic populations only. Non-Muslim customers are also demanding Islamic products and services that offer competitive products. As a result, non-Muslim countries are adopting this new trend and offering Islamic banking services. According to HSBC, more than half the customers for Islamic services in the UK were non-Muslims. It is worth noting that Islamic products and services can be offered either through Islamic windows at conventional banks or through newly established Islamic entities.

Sharia and the global financial crisis
The Islamic banking industry does face some challenges as no Islamic interbank market is present. Moreover, similar to conventional banks, Islamic entities were affected by the drop in equity valuation and Gulf property to which they are exposed. Even though the financial crisis did not affect the Islamic banking industry in particular, the drop in Gulf real estate and oil prices had repercussions on the industry since its sources of funds and liquidity were distressed.
Nonetheless, the impact of the crisis was lower on Islamic banks due to the asset-backed nature of their operations. As a result, the Islamic banking sector will continue to grow. However, it will grow at a pace expected to reach 10-15 percent in 2009, which is slower than its previous rate.

Islamic Banking in the MENA Region
The MENA region holds the largest share of the Islamic banking industry. In the four years leading up to 2007, the industry recorded a compounded annual growth rate (CAGR) of more than 31 percent. Islamic bank assets in the MENA outperformed their conventional counterparts that witnessed a lower CAGR of 24 percent.
Within the region, countries can be divided into two groups: Gulf Cooperation Council (GCC) countries and non-GCC countries that account for 51.4 percent and 48.6 percent of total Islamic assets in the MENA region, respectively. On one hand, the Kingdom of Saudi Arabia (KSA), with strong religious traditions, accounts for 35 percent of total GCC Islamic banking assets, representing 18 percent of the total MENA region. On the other hand, Iran represents 95 percent of total non-GCC Islamic banking assets, equivalent to 46 percent of the total MENA region.
Although the development of Islamic banking is dependent on the establishment of Islamic banking laws in Western countries, consumer demand is the main driver in the Arab world. Nonetheless, government support is still an important aspect as it controls barriers to entry in the industry. Oman for example, does not allow Islamic banking — the sultanate encourages conventional banking products and services. Contrarily, Islamic banking in Saudi Arabia and Bahrain is highly supported by the government, making the latter a regional hub.

Products and services
Despite its recent entry to the market, Islamic banking offers a variety of products and services that correspond to conventional banking sector services and are compliant with the Sharia. Murabaha, mudaraba, takaful, sukuk, ijara and qard hassan are only a few of the Islamic products offered.
The murabaha facility occurs when a lender buys an asset and sells it back to the customer at a higher price. The latter allows the lender (i.e. the bank) to make profit through an agreed mark up in price, without violating Islam’s interdiction on lending with interest. This fixed income loan is only used for the purchase of tangible assets such as real estate or a vehicle.
Mudarabah is another service offered by Islamic entities that allows the bank to finance a business without receiving interest payments. Instead, both parties (the lender and the borrower) share profits made by the business, according to a predetermined ratio. In case of loss, the bank loses its capital, while the borrower forgoes the labor and management provisions.
Takaful is the Islamic substitute for insurance, in the form of a murabaha, mudaraba or as a combination of both. In principle, takaful allows policyholders to pay an amount of money and place it in a single pool. The latter will then be used to aid those in need of assistance.
Sukuk is the Islamic equivalent of a bond. It is a financial certificate that is sold to a lender who rents it back to the original issuer at a higher price. It is worth noting that the issuer is obliged to buy back the certificate at a future date at par value. At that point, the issuer would have borrowed money and the lender would have made a profit margin without the use of interest payments.
Unlike the previously mentioned products, qard hassan does not have a counterpart in Western banking. It is a loan granted on a good will basis. The borrower is only required to repay the original amount of the loan. No profit margin is passed on to the receiver of the loan. However, an extra amount may be paid by the debtor as a token of appreciation.

Growth drivers
The key aspects behind the success of Islamic banking vary widely. The most important of these is the world’s rapidly growing Muslim population, which recorded a higher growth rate (1.9 percent) than that recorded by the total world population (1.2 percent) during the period 2002 to 2006. This represents around 24 percent of the total world population and it is expected to reach 30 percent by the end of 2025. Additionally, the world’s Muslim population is very young. Another major reason behind the rise of Islamic banking is the increasing wealth of Muslim nations. This is due to the discovery of vast oil deposits in the Gulf region accompanied by higher oil prices in previous years. The planet’s oil dependence has helped the region to benefit from abundant liquidity, which in turn has created enormous development opportunities. Projects worth more than $2.91 trillion are either underway or in the pipeline in oil-rich countries.
The acceptance of Islamic banking activities and its demand by non-Muslims has helped the industry overcome geographic and religious barriers. Western countries and non-Muslim populations are attracted to Islamic banking due to its perceived stability. The attractiveness of the profit-loss sharing schemes has also contributed to the wide acceptance of Islamic banking products. Furthermore, the spiritual appeal of the industry, its focus on the Islamic identity, the support granted by governments and its regulatory systems have also contributed to Islamic banking’s growth.

Opportunities and challenges
Like other industries, Islamic banking is faced with many opportunities and challenges. One of the most important challenges for the sector today is the interpretation of the sharia, which differs among countries and the various religious schools due to the lack of a unified Islamic regulatory body. As a result, an Islamic product may be accepted in some parts of the world while it is rejected in others.
However, the most important challenge faced by the Islamic banking sector is the unavailability of experts schooled in both banking and Islamic issues. An Islamic banker must possess a profound knowledge of Islam, in addition to finance. The shortage in experienced and qualified scholars is forcing them to field positions on multiple sharia boards, which in turn increases the risk of a conflict of interest. What is also important is that for an Islamic product to enter the market it ought to be approved by two sharia boards, one at the bank level and the other at the state level.
The financing of the many development projects in the Gulf region represents a growing opportunity for Islamic banking. As most Arab governments encourage Islamic banking practices, an increasing number of sharia-compliant financial institutions have benefited from the financing contracts of these projects. The latter has been made possible through the issuance of sukuk. Some economists believe that the sharia-compliant finance deals will account for more than 25 percent of the total project finance market in the coming years.
In brief, the Islamic banking industry is a fast growing sector that offers an array of opportunities yet to be exploited. Although the MENA region still represents the biggest share of the total Islamic banking sector, Western countries are gearing towards this new trend that presents a unique opportunity to diversify. With a growing market share and a considerable growth rate recorded over the past decade, it is essential for a unified Islamic banking authority to be established. The latter will be charged with standardizing Islamic banking operations and facilitating communication between the different entities, leading to the full exploitation of the sector’s potential.

April 3, 2009 0 comments
0 FacebookTwitterPinterestEmail
Executive Insights

Securing your ship in an economic storm

by Wassim Karkabi April 3, 2009
written by Wassim Karkabi

What was ‘expected to happen’ is really happening. There is no doubt anymore as to whether the world is in recession, crisis, downturn or whatever else you want to call it. There is also no doubt that the Middle East is affected in its own way by this global downturn. Of all the constituents of the Middle East, Dubai is perhaps the most affected. This is a fact of life, despite how well the news covers it up and the most important issue is that it has not yet hit rock bottom.

Some employers will not be affected. If you are one of the lucky ones, then you are an employer who is cash rich, in a high margin business, with leverage so low that it is minimal or a combination of any or all of the above. If not, then you have some tough decisions to make and you need to build a strategy to manage this financial tsunami, and strategy doesn’t mean mission, vision or a three to five-year plan for growth, but a real problem-solving strategy that will get you through this downturn.

We would like to suggest the 3Ms that are key to managing through turbulence: margin, margin and margin. The bottom line is it’s all about your bottom line; the numbers, how well you can crunch them, how well you can sustain them, tighten them, grow them or just maintain them. Research and history show us that companies who purely pursue a defensive strategy will perform a lot worse than those who adopt a more proactive one.

Leadership

Leaders require a new set of competencies in this turbulent time. The key set of skills that existing CEOs possess to drive through this storm is not the same as the one they used in the booming economy. Unfortunately, some CEOs don’t possess the skills, hard or soft, for this adventure sport.

According to Lowell Bryan and Diana Farrell in their article on ‘Leading through uncertainty’, executives need greater flexibility to create strategic and tactical options they can use offensively and defensively as market conditions change; they need a sharper awareness of their own and their competitor’s positions and they need to make their organizations more resilient.

Strategy

This crisis is an opportunity in disguise for companies equipped with leadership that has the know-how to implement an action-program that works during a downturn. In a panic situation, companies, run by human beings, will react in the same way humans do. It’s the ‘fight or flight’ dilemma. The ‘flight’ companies, which have closed down their operations completely or downsized to an ineffective size are well documented.

Then you have the ‘fighter leaders’, and those come in two types. There are those that will flap around grabbing at straws to make ends meet without any particular strategy and others that will build a real and interconnected response to a challenge, an overall approach based on an analysis of a demanding situation, with an articulate viewpoint of the forces at work.

The usual ways of doing business no longer apply and a new action plan is needed to ride this wave. What follows are some areas that need to be immediately addressed to compose an overall strategy for survival and even triumph.

Maintaining the customer experience

The most important pillar of the strategy should be, no matter what, to maintain the customer experience. Companies that manage to do so will become leaders in the market that will emerge after the downturn. Just because you are in a crisis does not mean that your customers will tolerate a lower quality of service or product.

The light still has to turn on when you flip the switch in your home. The food you order still has to taste as good as it did during a booming economy. Similarly the oil that your customer puts in his car has to maintain the car’s engine just as well as it used to, if not better.

Actually, if anything should be done regarding customer experience, it should be to upgrade it. Service towards the customer has to become more flexible, provide more options and alternatives, and most importantly it should take into consideration the fact that your customer is going through the crisis too, hence innovation and added value become key for loyalty in the downturn. Take advantage of this downturn to strengthen your competitive edge. Take business away from competitors at a profit and rethink costs of doing business to deliver a healthier margin that will support you through the crisis.
This crisis will present some opportunities and companies have to examine them closely. If you are cash rich, take advantage of distressed competitors’ assets and buy them at basement prices. Many suppliers are willing to negotiate better terms. Real estate developers around the Middle East who have made enormous sales records during the boom and did not start building, or even those who already started building, can re-issue tenders to suppliers to negotiate lower prices.

Examine carefully what your customer breakpoints are and re-adjust the service level to one that maintains customer experience with negligible attrition, while at the same time offers tremendous savings that can be re-invested in improvements as part of the ongoing problem solving process.

Upgrade the talent pool

While reducing staff and consolidating responsibilities is already a widespread practice, companies should make sure to address the implications this has on the employer brand, it’s internal culture and external reputation towards the larger community. Still, a crisis can offer a tremendous opportunity and — sadly — an excuse for companies to reduce the levels of redundancies, or rather, the duplications that were the initial result of over-hiring which took place across the GCC in anticipation of market demand, opportunities, expected growth and upcoming projects. This will allow companies to rethink their organizational structures and their effectiveness and to rebuild a tougher, more robust organization that is capable of surviving, and even triumphing, in this tough economy while containing a springboard and a model for more balanced growth once the economy begins its turnaround.

Marketing and sales

Marketing and sales executives are now asked to do more with less. What will work in today’s economy is by and large different from the sales and marketing strategies that used to work. For example, cut down on traditional media spending and explore what used to be considered complementary media, such as Internet and social networking, which have in the past few years gained major momentum. Additionally, consumer activation programs and being close to your customers by interacting with them on the ground may offer better results and lower costs than traditional mass media vehicles. Replace your “more-feet-on-the-street” strategy with a more customer-centric frontline, product specialists and industry specific sales managers that can provide more customized and better service, and identify and target new revenue opportunities in specific market sectors. It is also important to focus efforts on serving specific sectors with industry specialists that are capable of identifying and targeting new revenue streams from a specific category of clients across a number of its products. It is crucial to create a map of the market that will identify a new ‘who’ and ‘where’ regarding the remaining profitable customers, the sectors and the geographic locations, mobilizing the most effective sales and marketing vehicles to reach them.

Rethink your learning and development approach

Learning and development is always one of the first budgets to be affected by downturns. Yet it seems that these situations may be the best opportunity to upgrade your already existing talent pool by continuing to invest in training solutions. Companies cutting jobs should carefully maintain and rigorously protect training and development programs, as they are necessary to provide your talent pool with the skills needed to perform redesigned jobs that have bigger responsibilities and a greater span of authority and control. One solution is to replace external trainers with internal ones by offering the opportunity to internal specialists and the company’s senior leaders to participate in your learning programs, while also enhancing their facilitating and coaching skills. This approach can both reduce the cost of training and development tremendously, while at the same time redirecting the content of leadership programs by tying them to decisions and skills affecting the company’s current performance issues.

In short, there is definitely a need for a different set of skills and without those skills some companies may not survive. Here is the upside: this is a classic case of survival of the fittest. Companies that stay afloat during this period will find themselves in a more robust market with less competition and more demand to meet their supply; the ship will be stronger, manned by a tough crew and led by a clear minded strategist at the helm, with a strong vision for growth in the years to come.

Wassim Karkabi is partner and regional practice leader EMEA, Stanton Chase International

April 3, 2009 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 475
  • 476
  • 477
  • 478
  • 479
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE