• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Levant

Syria: the gloves come off

by Executive Staff January 2, 2007
written by Executive Staff

Syria is looking to build on its already extensive textile sector in an effort to become an increasingly global player in raw materials and processed products.

However, Syria faces numerous difficulties both at home and abroad to lift its cotton production and processed materials output and quality, with massive investments needed to bring them up to international standards and make them competitive in the cut-throat world market.

Syria’s textile and apparel sector accounts for 30% of the country’s industrial employment. While figures for employment levels in the primary production of the main raw material, cotton, are seasonal, they do represent a sizeable proportion of the 25% of those engaged in agriculture.

The government has been pouring money into the cotton and processed materials sectors, improving irrigation for primary producers and spending on new plants to enhance milling, weaving and apparel production.

These efforts have met with some success, with the production of unprocessed cotton seed breaking the one million ton mark, giving 350,000 tons of cotton lint for processing, with the number of ready-made garments turned out topping 55 million, up from 35 million in 2000.

However, downstream industries still suffer from a lack of investment, with local spinning and weaving facilities only able to process 150,000 tons, the balance available for export. This lack of processing capacity has prompted the government to cut back on planting for the coming season, reducing seed cotton production to 900,000 tons for the 2007 harvest.

Gloves come off

The cotton sector has long been given a high level of government protection, with the importation of raw cotton, yarn and fabrics banned except in special cases. At the end of 2005, under international pressure, Damascus agreed to allow imports of cotton-based clothing, though with a near prohibitive 47.5% tariff. Over the past few years, there have been accusations that Syria has been dumping both processed textile products and cotton onto the global market at below cost in order to increase sales and support the industry at home.

Given that the government looks upon the cotton and textile industries as being of strategic importance to the country, the sectors have seen fewer developments in the economic reform program, with most elements, barring the ready to wear segment, still dominated by the state.

However, this too may be set to change. There have been a number of reports in the state-owned media highlighting losses and the drain on the budget. Similar reports have in the past flagged reforms in other sectors of the economy, meaning there could be a shake-up on the way for the textile industry.

The drive by Damascus to modernize and expand the sector, however, may be too late, given that most of the brakes have been taken off China’s massive apparel juggernaut. Clothing and textile producers around the world have been feeling the pressure of competition from cheap Chinese exports after the lowering of trade restrictions.

Stiff competition

Closer to home, Syria has to compete with the well-developed Turkish and Egyptian clothing and fabric production sectors, both of which have built up extensive links in existing markets in Europe and the US, and have modernized their facilities to meet the most up to date trends. Both the growing strength of China in the world’s markets and competition in the country’s neighborhood may explain the reluctance of overseas investors to put money into Syria’s textile industry.

Even with the concerted efforts of the state, Syria managed to boost its export revenue from yarn and cloth by only $2 million in 2005, bringing in a total of $96 million for the year.

However, according to Jamal al-Omar, the director-general of the Syrian Textile Industries’ Establishment, domestic sales showed a significant increase, coming in at $385 million, a 14.5% improvement on the previous year’s figures.

More significantly, al-Omar said that the industry as a whole had managed to turn a profit this year, for the first time in its history, though he added that further support would be required to allow it to compete in overseas markets.

January 2, 2007 0 comments
0 FacebookTwitterPinterestEmail
Lebanon

Death of a shopping district – BCD retailers cry SOS

by Executive Staff January 1, 2007
written by Executive Staff

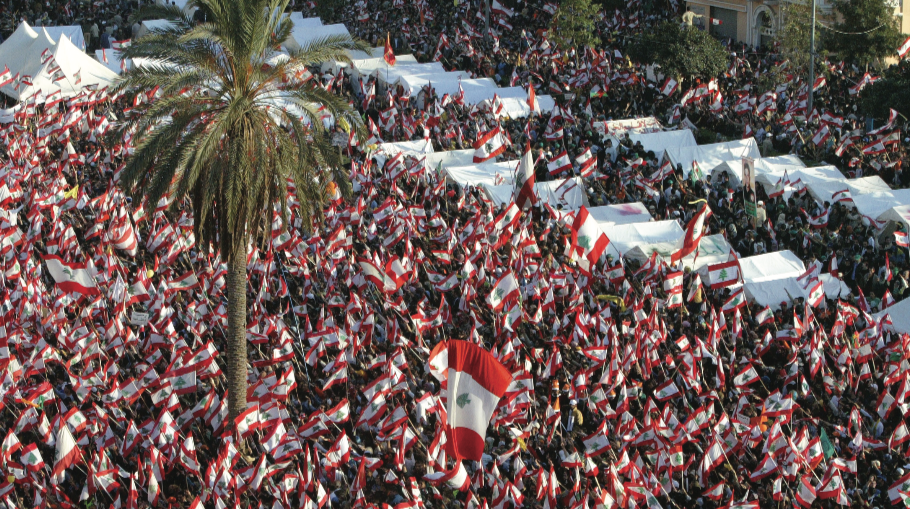
One week into the opposition demonstrations that effectively paralyzed commerce in the capital throughout much of December, a few hardy businesses in the Beirut Central District (BCD) cautiously opened their doors – despite the presence of the Lebanese Army and its armor, dogged protesters, and coils of razor wire – to holiday shoppers. They hung their Christmas decorations and slashed prices in a last ditch effort to woo shoppers. It capped off what has been, by all accounts, a disastrous six months for Lebanon’s luxury retail and hospitality sectors.

Indeed, the commercial fortunes of tenants in the BCD, where rents average $1,000 dollars per square meter per year, have been in the epicenter of the bruising political events of the past two years that began with the assassination of Rafik Hariri. After bumper years in 2003 and 2004, the demos and funerals of 2005 saw business in the BCD drop by 50%, while in 2006 that dip has increased to 70% due to the summer war and more demos, funerals and sit-ins.

Dying a ‘slow death’

This trend will surely continue into 2007. Retailers were reportedly in the midst of scouting alternative, less economically vulnerable locations in December, and said they would be forced to move if the deadlock continued into the New Year. The Lebanese finance minister said that each day of demonstrations has cost the economy $70 million in losses, and according to some estimates up to 70% of businesses in BCD are in danger of collapsing. At the time of writing, Jihad Murr, the owner of the Virgin Megastore – not just a shop, but a landmark that at one point epitomized the retail magic of the BCD – declared that they were dying a “slow death” and may be forced to shut down.

Paul Ariss, the president of the Hotel, Café, and Restaurant Syndicate, confirmed that many members of his association have been considering a change of venue since the war and some have begun to expand elsewhere in the region, namely Saudi Arabia, Egypt, and Qatar, but said it was too early to estimate the number of departures from the BCD.

“In 2005 BCD was closed for at least 40 days following the death of Hariri, and I don’t know how many days for the assassinations afterward,” he explained.

“Then there were 70 days for the national dialogue and the Council of Ministers meetings. Then 43 days during the war, and now the sit-in. Add all this up and no commercial venture would survive. Businesses are either paying operating costs out of their own pocket, selling shares, or whatever is necessary to stay afloat.” He explained that investors were in too deep to just pull out. “Right now, everyone is just hoping that things will get better.”

Staying afloat

Solidere preferred not to comment on the situation, with General Manager Mounir Douaidy saying it was “premature to determine the impact of political events on Solidere.”

Though rents will probably remain unchanged, Solidere did exempt tenants from two-months of rent for July and August. According to Sami Hochon, owner of a Lina’s franchise, a popular BCD café, Solidere has indicated its willingness to do so again if the current stalemate continues into February 2007.

Hochon was one of many high-end business owners to attend the launch of an advertising campaign to kick-start the holiday shopping and tourist season held at the Phoenicia InterContinental in Beirut in mid-December. He said that many foreign companies have closed their Beirut branches since the war, and feared he would have to follow-suit if the situation continued for three or four months.

“People are not spending money so none of my locations are doing well, but business (at Lina’s BCD location) has dropped 80% from last year,” Hochon admitted.

Mall power

The outlook is better for Beirut’s malls, which could benefit from the potential exodus of retailers and restaurants from Solidere, assuming they have the vacant space. Ariss said some in his syndicate are interested in relocating to the Ashrafieh branch of ABC, which is already 90% occupied, and the mall’s operations manager confirmed that inquiries have surged since the sit-ins began downtown.

At City Mall in Dora, also 90% occupied, the number of inquiries into temporary leases for the holidays is below the expected level, according to the mall manager Rony Aoun. They have, however, received 12 applications from retailers looking for permanent space during the last quarter of 2006, although Aoun insisted the increase in demand was not necessarily linked to the political situation in the BCD.

Meanwhile Solidere – the biggest company listed on the Beirut Stock Exchange – saw net profits in the third quarter of 2006 drop by 81.5% from the same period of 2005, from $23 million to $4.25 million. Douaidy tried to put a brave face on the figures, saying they did not show the true picture. But, at the end of the day, chaos is not good for business. Just ask Jihad Murr.


January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Lebanon

Extra Virgin

by Executive Staff January 1, 2007
written by Executive Staff

Olive oil has been a staple of the Middle Eastern diet for millenniums and demand for the product remains high. Global consumption of olive oil has been increasing at 1.5% per annum over the past decade. Market demand for this product is expected to continue as the apparent health benefits of olive oil, and an ongoing interest in Mediterranean cuisine, stimulate the market.

Under-developed sector

Lebanon is considered a minor player in a global market dominated by Spain, Italy, Greece, and Tunisia. The Stanford Research Institute (SRI) Expanding Economic Opportunities in Lebanon project, estimates the economic value of olive farming in Lebanon to be well over $200 million annually – barely 0.2% of the global $125 billion olive oil industry. The IOOC (International Olive Oil Council) released new figures in November 2006 showing that, while overall worldwide production has increased in the last 10 years from 1,735,000 tons to 2,599,000 tons, Lebanon’s production has barely changed – it went from 5,000 tons to 5,500 tons and the same is predicted for 2006/07. However, Lebanon’s neighbors are cleaning up their act to keep up with increasing global demand. Syria’s olive oil output went up from 76,000 tons to 100,000 tons in the last decade, and the IOOC predicts an output of 155,000 for 2006 and 2007. Jordan almost doubled its production in last 10 years and output is expected to increase from 22,000 tons to 36,000 tons this year.

In terms of foreign sales, Lebanon exports 1,000 tons, while Syria is predicted to shift 40,000 tons overseas – a 100% increase since 2005 – while Jordan is expected to experience similar growth with 17,000 tons.

Lebanon is clearly lagging behind, but experts agree that there is global demand for its produce as international olive oil tasters highly rate Lebanese extra virgin olive oil. “Our oil is excellent when produced using good cultural practices and when extracted in modern mills, respecting hygiene conditions,” explained Hussein Hoteit, an agricultural engineer.

Lebanon produces many different flavors and tastes of extra virgin olive oil because of the variations in soil, topography and altitude, but producers now realize that to be part of the global market they have to consider more than just the taste. (Access to international markets was eased in 2002, when the EU agreed to full liberalization – i.e. no duties and no quotas for less than 1,000 tons – for Lebanese olive oil, but production still remains too low for a major entry.) Today’s producers must recognize that economies of scale, labor costs, agronomic practices, and quality pressing are essential in today’s global market.

“One third of the oil produced, is for personal consumption; the remainder is sold to be bottled by the major companies, or from producer to consumer directly in the [$85, 16kg] tanakeh,” said Youseff Fares, an agricultural engineer and manager of Olive Trade. He added that the summer war reduced supply and pushed up prices of what was otherwise an excellent harvest.

One too many obstacles

According to Hoteit, many olive groves were damaged or covered by cluster bombs that prevented harvesting. The mohafaza of Nabatiyeh is only able harvest 23% while the mohafaza of South Lebanon can only pick 17% of the crop. On top of this, five olive mills in the south were destroyed. “The Lebanese olive oil industry is in a tough position. Production costs are increasing, quality is decreasing and the moral of the producers is at an all time low,” said Sleiman El Dagher, president of the Syndicate of Interprofessional Lebanese Olive Oil Producers (SILO).

The war was just another stumbling block for this fraught industry. According to SRI there are several problems facing the sector. Progress within the industry is vital if it is to grow, compete, and sustain itself in the world market. With respect to economics of production, the most important considerations for olive growing to ensure high fruit and oil yields are improved crop management and production techniques. Good storage facilities are also vital to retain quality of product. In Lebanon, these are inadequate compared to other Mediterranean countries.

There is a lack of extension services at the public sector level, such as low cost laboratory and testing facilities, while the sustainability of the sector is also at risk, especially in the south, as fewer people are choosing to live in the rural, olive growing areas.

Local consumers have also been hit by the recession and are reluctant to pay premium prices for olive oil. This has led to increased imports of foreign produce, especially from bulk-producer Spain. To make matters worse, Lebanese olive oil is losing out to shady operators who import olives and oil. These are either pressed or rebottled locally and passed-off as Lebanese.

Reaching out to other markets

Not surprisingly, producers and farmers are calling on the Ministry of Agriculture to implement a nationwide initiative for the improvement of the sector, with a focus on higher quality and a larger agriculture extension and outreach program.

Cheaper laboratory and testing facilities are also needed. “A nationwide incentive to test and certify local oil is essential for this industry to thrive,” insists El Dagher.

There are several ongoing projects with EU financing to train tasters to form a national Lebanese panel and establish four agricultural service centers in Jezzine, Hasbaya, Marjayoun and Bint Jbeil. Each will feature a modern mill and plant for bottling. Elsewhere, a number of producers are looking to export to specialty markets, such as France, Spain, USA, Australia and the Arab countries.

All this can be a significant source of jobs and revenue in the struggling agro sector. According to the SRI, however, to accomplish this, Lebanon must plant more trees and double its output of extra virgin olive oil, the type most in demand internationally. At the moment, it is estimated that extra virgin olive oil represents 25% to 35% of total Lebanese olive oil exports. “We should not attempt to take the highway of globalization that larger countries like Spain, Italy, Turkey and Greece, are on,” said El Dagher. “We should focus on creating a genuine Lebanese product, which can be exported to niche markets abroad.”


January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Stock market games – The big bull stirs

by Executive Staff January 1, 2007
written by Executive Staff

While the consensus of stock market analysts at the end of a harsh 2006 was an uncertainty if those erratic equity markets – mainly those in the Gulf Cooperation Council (GCC) – have reached the bottom, recent research papers by some major financial companies were taking a view of better tidings ahead.

Dubai’s Shuaa capital in December said it is bullish on the UAE, Kuwait, and Oman and sees Saudi Arabia entering an accumulation phase. Kuwait-based Global Investment House predicts Kuwait, Saudi Arabia, and the UAE to show more than 25% growth in equity markets in 2007 and forecasts “moderate growth rates” of 17% to 23% for stock markets in the other three GCC countries – Oman, Qatar, and Bahrain.

In addition to these local firms, the Middle East research department of Japanese financial services house, Nomura, said “intuitive observations suggest that the markets are in the final stages of digesting last year’s excesses and are set to trough soon.”

Suffering big losses

By ways of a historic rather than financial analysis and comparison with bull-bear swings in other emerging markets, Nomura analyst Tarek Fadlallah provided statistics by which the past bull runs of 28 and 39 months on the Dubai Financial Market (DFM) and the Saudi Stock Exchange (SSE), respectively, were within the experience ranges of upturn phases previously seen in Asia and Eastern Europe as well as on the Nasdaq, given an average upturn-phase duration of 31 months within a range spread of 19 to 48 months.

However, when computing the severity of the correction, the DFM and SSE were not quite yet at the maximum loss level of 80% that emerging markets experience as average of their post-bubble corrections. Also in terms of duration, the regional downturn periods were still shorter in November than those seen in other markets before they entered recovery periods with attractive market gains.

In terms of financial analyses, the professional equity gazers have positive things to say about the way in which valuations have returned to levels comparable to other emerging markets. The process was certainly painful for exposed investors, especially retail buyers, who had jumped on the train late, while it was well into its ride to the peaks.

The most recent research notes by regional markets analysts of Shuaa Capital and Global Investment House put the price to earnings ratio estimates for GCC markets in 2006 at between 11 and 15 times earnings (Global) and nine times to 16 times (Shuaa). In the calculations of both firms, the SSE is the most expensive market and has the highest P/E. But being in a range of 15 times earnings is a big step forward for the Saudi bourse from the excessive valuations represented by last year’s prices, when stocks were pushed to trade at almost 40 times earnings.

Price to earnings ratios in the Saudi market have returned to rational levels and are now attractive to long-term investors, Global augured. Retail investors will contribute the thrilling aspects to the equation, it added.

One example for the starkness of the Saudi market correction is the petrochemicals behemoth Sabic, which parachuted from a price to earnings ratio of 40.1 to 13.4. As Nomura notes, this SSE blue-chip stock, contracted by some $130 billion in market capitalization from its peak valuation in February 2006 until December. That loss was more than the annual GDP of Singapore, Nomura said – or, to speak closer to home, it would in mere mathematics be equal to about twelve times of what Lebanon by some accounts suffered in short and long-term economic damage from the war between Israel and Hizbullah.

Although the huge monetary losses from the crash of the Arab bubble made this one of the “largest emerging market meltdowns in history,” the analysts see reasons to justify that the downturn of GCC stock markets will differ in important aspects from other big crashes that went down in history as triggers of macroeconomic crises in the affected economies.

The main element that appears to protect the region from even more painful crash consequences such as macroeconomic crises and need for far-reaching restructuring to remedy systemic flaws is the good economic outlook with high liquidity levels. Thanks to its oil billions, Saudi Arabia, which saw half a trillion dollars in market cap evaporate in 2006, could nonetheless reduce its public debt from more than 100% of GDP just a few years ago to around 28% for 2006.

In line with their strong oil outlook and ample liquidity, the region’s markets should rebound this year, and stock prices are widely expected to move in line with the corporate earnings stories of listed firms that will start to come out in raw versions from the middle of January. This is the ruling expectation, even though the overall respectable third-quarter 2006 results of major GCC corporations did not have enough punch to drive the markets out of their negative sentiments, a failing that Nomura’s Fadlallah described as missed opportunity to “muster a noteworthy rally during the autumn.”

Sector by sector

Smart investor decisions may be quite a challenge for 2007, however, testing investors on picking the right stocks to buy and sell and on basing their decisions on the proper information. “Bottom-fishing” for low price stocks, which some analysts promote, is described by others as a risky proposition, because the temptation is great to buy too early and gamble away both money and confidence. And sector by sector, no part of the regional equity scene can be considered free of risks and downsides.

Finance and banking is by far the largest sector on GCC bourses. Banking shares are stacked high on the outlook list of several regional investment advisory firms – some of which are well interlinked with those very banking stocks that they view favorably. However, while many have been very profitable and have continued good earning outlooks, banks in most GCC markets are sailing into more competitive waters and will have to prove themselves there.

In telecommunications, another high-attention sector in the region, the leading GCC-based players have positioned themselves convincingly on the international field. The caveat here too is that the share prices of several major regional companies are at levels that do not compellingly entice when compared to some of their global peers.

The sector to watch with greatest care in 2007 is, with strong probability, real estate. Consensus of market analysts is that the real estate price runs in various countries and sub-sectors of the GCC property markets will lead to a correction phase in the valuation cycle as supply-demand dynamics for real estate turn. The question, which analysts tend to approach with optimism, is if the real estate bubble will deflate gently or see valuation balloons pop right and left.

The property prices from the second half of 2007 and in 2008 in Dubai and the other GCC markets will provide important information on the challenges that the economies will have to master in this sector. But, serious analysts already warn convincingly that real estate investments in the coming years cannot be considered foolproof and guaranteed to realize double-digit rates of return. The end of the property bubble will be just as inevitable as it was for the equities bubble.

Raising the perspective to a regional look outside the GCC, the market valuations in North Africa are reaching bubble levels, warned Shuaa, and cautioned against exposure to the Moroccan and Tunisian exchanges. One national equity market that was largely absent from recent strategy notes was Lebanon’s BSE. This proved another testimony to the fact that while wars are bad for modern-day bourses, persistent uncertainty from perennial internal instability is even worse. Analysts call the Beirut Stock Exchange a wait or withhold.

The big question for the regional equity markets is if corporate earnings of 2006 will present enough substance to let retail stock market players shake off the post-GCC bubble blues early next year and turn their attention away from instinctive herd behavior to more fact-driven trading decisions and also towards opening additional new opportunities.

Global, which sees a stabilizing factor in outward diversification, singles out Pakistan as example for a growth market where GCC liquidity has positioned investors near the top of the pecking order. According to the researchers, UAE investors are the second largest source of foreign direct investment inflows in Pakistan after the US, accounting for 14% of all FDI. Saudi banks and industrial firms are also expansive in Pakistan and an impending free trade agreement between Pakistan and the GCC is expected to further boost FDI flows into this country from its Arab neighbors.

With the correction phase of the leading Arab bourses tapering out, GCC and Arab market risks persist nonetheless in structural and behavioral factors. While liquidity is the strong element at this moment, the yang that will keep the macroeconomic sting out of the bust of the GCC bubble, the darker side of the equation is the absence of market makers and independent minds, of transparency and convincing regulation.

Then there are still the incorporeal challenges to be handled, the investor psyche and confidence factors. For now, Global Investment House sees the GCC market drivers as dominated by emotions and fears “where all the good news is discounted and the bad news create more flutter.”

This speaks of the need to educate, build awareness, and improve governance and transparency. In a mirror image of their larger economic constitutions, the message that needs to be pounded into the securities markets is that of governance benefits and the increasing rationalism that will make markets more rational. The excitement of the stock market game will still guarantee that forecasts and expectations will be proven wrong and excitement can be gained. But, the swings will move more reliably to be within those ranges that macro planners need and analysts love to chart.


January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Wanted: Alternative investments

by Toby Stevens January 1, 2007
written by Toby Stevens

The Middle East continues to experience unprecedented interest in alternative investments as regional institutional investment in hedge funds is expected to surge to $140 billion, or 14% of the total $1 trillion forecasted institutional investor capital in hedge funds by 2010, according to a report by the Bank of New York.

The report said global institutional investor capital in hedge funds will increase from around $360 billion today to more than $1 trillion in 2010, and institutional investors will account for more than 50% of the total flows.

On this premise, the Middle Eastern institutional investors will increase their exposure to worldwide hedge funds almost five times from around $29 billion today, mainly because the willingness of regional institutions to invest in hedge funds will outpace the expected near tripling of the industry portfolios.

While noting that the vast majority of institutional investors worldwide – Bank of New York estimates 85% – do not currently invest in hedge funds, the report sees alternative investment tools of the industry move into the mainstream of financial management practices. Institutions using hedge funds are in the large majority satisfied with their performance, and only 3% of surveyed institutions said hedge funds they were invested in had underperformed.

To better understand investment tools used by hedge funds, institutional investors will be pushed towards those comparatively aggressive funds by a growing need to achieve higher returns than those offered by more traditional strategies, such as equity and fixed income investing. The increased demand for hedge funds in the Middle East is the result of investors searching to diversify portfolios into investments that are not linked with volatile equity markets.

The report, based on interviews with 101 senior professionals in the fund management industry and updated from a 2004 study, shows Middle East institutional investors make up around 8% of the global institutional market, while the United States and Europe – including Japan – represent around 40% each.

“Investors are looking at hedge funds as an investment that has a lower correlation with other assets in the portfolio. Diversification is the single most mentioned reason for investing in hedge funds,” the report said.

Leader of the pack

According to David Aldrich, Bank of New York managing director, the GCC, with its serious liquidity and high oil revenues, is expected to take the lead for the bulk of the region’s 14% worldwide institutional hedge fund investments.

“Middle East institutions are adopting a more aggressive approach to investment, and you’ve got big government-backed investors who are not constrained by investment fund trustees,” said Aldrich. He noted that regional investors have been on the lookout for better return on investment for some time, especially after the exceptional performance by the GCC stock markets in 2004 and 2005.

Historically, regional investors have preferred mutual funds and until recently, hedge funds have appealed to those willing to take big risks. But, since governments continue to reap the benefits of high oil prices, the hedge fund market has taken on a new dimension for institutional investors in the Middle East. Coupled with the current downturn or volatility of the region’s stock markets, investors are keen to explore the potentially rewarding investment alternative.

“Bull markets don’t really encourage people to move into alternatives,” Aldrich said. “A lot of institutions have just moved into hedge funds globally and these investment decisions were triggered by the bear market in global equities.”

Many institutions view traditional fixed income as a low return asset class. Low yields across the developed world have created a huge gap between fixed income returns and investors’ needs. The report pointed out that the vast majority of those surveyed, 72%, said their hedge fund program has performed within 1% of their target expectations; 25% said that their hedge fund exceeded their return target by 1% or more.” Only 3% of investors said that their hedge fund program has underperformed versus their expectations.

The UAE, and specifically Dubai, has been aggressively at work to position itself as a one-stop-shop for the hedge fund industry. The UAE recently issued and passed the Collective Investment Law 2006, in the DIFC as part of a strategy to provide solid infrastructure and incentives for fund managers to operate. “Dubai can offer the proper administration and the location for investment advisors. This is a more complete package than the Cayman Islands, which is currently the domicile of choice,” Aldrich explained. “But this will be a slower process than people would like. Returns are more important than infrastructure.”


January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Saudi arabia – Just say ’no’

by Executive Staff January 1, 2007
written by Executive Staff

A decision by Saudi authorities to put a temporary halt to licensing of new foreign banks until the country completed an evaluation process for those issued in the past few years was something of a surprise. This could be a blessing in disguise for the sector, however, because it offers bankers and the international financial industry a chance to re-evaluate the sector and gain insight into the Kingdom’s future demand for new foreign banks.

The governor of the Saudi Arabian Monetary Agency (SAMA), Hamad Saud Al Sayari, said in early December 2006 that Saudi Arabia would not issue new licenses until it had reviewed the sector. Insiders told Executive that the outcome of this review is not at all a foregone conclusion.

“SAMA, which has issued full-fledged licenses to 11 foreign banks, has a committee reviewing these licenses to determine future demand. Even those in the committee do not know when they will finish the evaluation process. The only thing that is sure is that it will take time,” said an official close to the agency, who wished to remain anonymous.

It is clear that the Saudi market has a lot of use for advanced banking skills. With budget expenditures of $100 million scheduled for 2007, on the back of another $80 billion budget expenditure in 2006 (plus a 2006 budget surplus of an incredibly cozy $71 billion), the proverbial oil wealth of the desert kingdom is searching more than ever before for productive investment channels.

The Saudi banking sector is heading into a regional boom and expansion plan, especially in line with the joint government and private sector projects for building – until now four – giant economic cities. Over the next few years, these four new megalopolis projects in Rabigh, Hael, Medina and Jazan alone will require investments of more than SR155 billion ($41.3 billion).

Along the way, these cities will create a huge demand for financial advising, corporate financing and consultancy skills which are the domain of investment banks. But, smart banking is not only needed to help ascertaining that the humongous investments into the Saudi socioeconomic future will not be put into the sand wrongly.

Expansion boom 

The growing affluence of Saudi individuals and families and their retail banking requirements also have attracted new banks to the market after many years in which a small number of domestic banks served the country. On top of this, the opening of the stock market to new investors and the strong interest of local retail investors to buy and sell stock on the Tadawul stock exchange led to a push of new brokerage and financial services providers into the market. The authorities facilitated this by issuing a wave of new financial intermediary licenses in 2006.

In the premier league of investment banking and commercial banking, SAMA opened the sector to foreign banks in 2001, and it gave nine licenses to operate as investment banks (see table I) that can provide services in the Saudi stock market. It awarded ten licenses for foreign banks to operate commercial banks in Saudi Arabia (see table II) with retail branch networks.

“As the Saudi economy grows and we are experiencing a boom, there are opportunities for everybody. As the Investment banking sector attracts more attention and more participants, and then there is greater competition for the corporate world in Saudi Arabia,” John Sfakianakis, chief economist at SABB Bank in Saudi Arabia told Executive.

In his view, it is positive that SAMA wanted to take a comprehensive look at the market to evaluate the investment banking sector. “This in no way means that the investment banking sector will see a clamp down or suffer a setback in any way,” Sfakianakis added.

Sfakianakis said that the UAE market has attracted many investment banks despite its smaller size. “It is not a matter of numbers of investment banks but it is measured by how much the economy grows and it seems that the Saudi economy will be growing for many years to come,” Sfakianakis added.

The Saudi banking sector’s total deposits (which are the total of demand, time and savings and other quasi-monetary deposits) reached around 550 billion Saudi riyals ($146.6 billion) at the end of October 2006.

Other analysts said that the sector is saturated and there is no need for new entrants to the Saudi market. “I think the country is over banked because there is an influx of lots of banks and they are all focusing on corporate finance services, whereas many different corporate finance opportunities have surfaced,” said Peter Wright, managing director at Saudi financial firm, Capital Advisory Group.

Wright said that the provision of services like advisory and IPO management services in the past has not been massive but, claimed that international firms with such capacities have for a long time been present in the country, operating through representative offices. Before 2001, foreign banks were only allowed to provide financial consulting, advising but not brokerage, or IPO management services.

Expanding vertically

The opening of foreign banks started partially by allowing foreign banks to enter into the Saudi banking sector as joint ventures with minority stakes. But due to the astounding growth levels, these foreign banks now want to assume a bigger role and are trying to expand on their own.

Some of the operating 11 Saudi banks – National Commercial, Riyad, Samba, Rajhi, Saudi British (SABB), Saudi Fransi, Arab National (ANB), AlJazira, Saudi Hollandi, Al Bilad and Saudi Investment (SAIB), and Al Enmaa Bank (or Development Bank), which is due to start operations in the first half of 2007 – already are joint venture banks. This is the case for Amman-based Arab Bank’s 40% stake in Arab National Bank, just as French Calyon Corporate and Investment Bank owns 31% in Banque Saudi Fransi and UK-based HSBC Bank Middle East owns 40% in SABB.

Of current interest is Saudi Hollandi Bank, in which Dutch bank ABN Amro has a 40% stake which it is intending to sell. Rumors of the sell-off plans have been circulating for weeks in Saudi banking circles, making analysts question why ABN Amro might want to divest.

“If ABN Amro is not seeing its growth plans fulfilled through Saudi Hollandi Bank, then the best time to exit is now because of the reasonable attractive valuation of ABN Amro’s 40% stake in Saudi Hollandi Bank and the high liquidity in the market,” Loannis Karapatakis, managing director of global investment banking advisory at HSBC Saudi Arabia, told Executive.

Some European analysts opined that ABN Amro might want to concentrate its resources in developed markets closer to home, such as Italy, where it had made a $9.9 billion acquisition, Banca Antonveneta, earlier in 2006.

Several Mideast-based economists, however, reasoned that ABN Amro’s decision could be based on an interest to expand in Saudi Arabia by establishing a separate foreign bank 100% under its ownership. This was the view of Saad Benani, a vice president of global markets at Merrill Lynch, who told Executive that ABN Amro could be interested in establishing a wholly-owned subsidiary in Saudi Arabia.

Whatever ABN Amro’s intentions, regional and international banks were quick and eager in looking to buy the 40% stake in Saudi Hollandi that is allegedly up for grabs. These foreign suitors included the National Bank of Kuwait, Britain’s Standard Chartered, and the Audi Saradar Group, which already has a new subsidiary in the kingdom, Audi Saudi Arabia.

The example of leading banks in Lebanon and Egypt – like Audi and EFG-Hermes – which were awarded full fledged licenses to operate in Saudi Arabia, has triggered other regional banks to do the same. Kuwait-based Global Investment House, for example, is also interested in setting a foothold on the Saudi banking soil and it translated its interest by applying in November to SAMA for a license to operate in Saudi Arabia.

The wave of new licenses to operate either as full financial and investment firm or as partial ones raged in 2006 whereby the Saudi Capital Market Authority, the government body that regulates the stock market, issued 36 licenses for Arab, international and local firms to offer brokerage, asset management, financial advisory and corporate finance services in Saudi Arabia.

After SAMA’s decision, this trend will likely culminate giving way to other firms to study carefully the market and see whether their venture into the Saudi financial market is still viable or not.


January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Banking & Finance

Planning ahead – IFQ venture

by Executive Staff January 1, 2007
written by Executive Staff

In December, Bahrain became the latest country to offer the Islamic Financial Qualification (IFQ), which was launched two months earlier in London as a joint venture between the British Securities and Investment Institute (SII) and the Ecole Supérieures Des Affaires in Beirut (ESA).

With religious feelings on the rise in the Arab world and the recent oil boom, Islamic banking services are being increasingly seen, as a natural alternative to traditional banking, and the IFQ reflects the growing interest in this particular field.

Initiated by the Banque Du Liban, the IFQ is already available in London through SII, in Beirut through ESA and in Bahrain through ESA Gulf. “The IFQ is an important development,” said London’s Lord Mayor, Sir Alderman David Brewer. “It is the world’s first ever global benchmark qualification to cover Islamic finance from both a technical production knowledge and a Shari’a aspect.”

According to Dr. Ahmad Jachi, vice governor at the Banque Du Liban, the Lebanese central bank, there are more than 250 Islamic financial institutions worldwide with a market capitalization in excess of $13 billion, total assets estimated at $300 billion and financial investments at $400 billion.

Increasing awareness

In 2002, $3.2 billion constituted the paid capital of Islamic Banks and financial institutions operating in the GCC area, according to the Lebanese central bank. Their total deposits, excluding restricted investment accounts, added up to $54.1 billion backed by $2.35 billion in reserves, representing 4.3% of total deposits. Total investments reached $35.5 billion, of which 58% represented investment in real estate.

Over the past decade, the average annual growth rate of the Islamic banking industry ranged between 15% and 20%. In Lebanon, the situation is different, as the industry is still in a nascent stage. “As of June 2006, there were four Islamic banks in Lebanon – namely, the Arab Finance House, Al Baraka, the Lebanese Islamic Bank and Blom Development bank. Boasting a 73% share, Murabaha is the most commonly used mode of financing,” said Jachi.

With those figures and the fast growth of the sector in mind, the IFQ is timely. It is aimed at those already working in Islamic finance or in the banking industry and prepares candidates for key positions in the areas of Islamic finance and Islamic insurance or Takaful. In Jachi’s view, financial specialists with such a qualification in hand will be able to better understand Shari’a principles applied to Islamic banking commercially, as well as to financial instruments, contracts and other transactions. “The candidate will also acquire practical insight into designing and setting up financial instruments such as Murabaha, Mudaraba, Sukuk, Musharakah, Salam, Istisna, Islamic funds and Takaful, as well as understanding and applying AAOIFI [Accounting and Auditing Organization for Islamic Financial Institutions standards],” he pointed out.

The specialization, which is delivered through several training sessions, delivered either in English or in Arabic, requires between 80 to 100 hours of personal study hours, before the candidate can sit for a computer based test called CBT. However, students can choose to work alone on the test, using a syllabus and a workbook (the first publication on practical Islamic Finance is available for order).

Training future experts

According to SII and ESA, public training for the qualification was held in November 2006 in London and Beirut simultaneously, with the IFQ becoming available worldwide via CBT starting March 2007. The technology also allows candidates to receive their results instantaneously. IFQ will meet level three qualifications on the UK classified National Qualification Framework (NFQ) and other levels within the qualification will be eventually developed.

Finally, the IFQ project originates from Al Multaqa, an international foundation for research in the field of Islamic Finance, existing under the ESA umbrella. The foundation is currently planning a database for Islamic finance as well as training sessions and lectures in the same field. This endeavor is carried out in collaboration with financial companies, banks, regulators and professional experts in the field of finance.


January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Capitalist Culture

Battling Over Beirut

by Michael Young January 1, 2007
written by Michael Young

The nature of the crisis between the government and opposition that began in early December was recognizable thanks to the nature of the battlefield: Beirut’s downtown area, the jewel in the crown of the late Rafik Hariri’s reconstruction program, and premier symbol of the capital’s conceit to be a cosmopolitan business center for the region.

In descending on the city center, managed by the Solidere company, the opposition, led by Hizbullah, sent several messages. For the mainly poor Shiites forming the bulk of the effort to bring down the government of Prime Minister Fouad Seniora, it was partly a class thing: Solidere is as much ours as anybody else’s, the demonstrators seemed to be saying, whether we are poor or not. But the tactic also included a hefty dose of blackmail, with demonstrators warning Seniora that the downtown area, so central to his and Hariri’s efforts to attract capital to Lebanon, was a ready hostage to the country’s political divisions. But the massive sit-in was also, lest we forget, an opportunity for demonstrators to do what everyone else does in the downtown area: enjoy themselves, (for the young men) ogle girls, and be part, if only for a moment, of what Beirut is all about – regardless of the maximalist rhetoric employed by political leaders.

Area of conflict

Recent events were hardly the first fight over the downtown area. When the destroyed old city center was being rebuilt in the early 1990s, publicists and academics were already flicking drying concrete at each other over what the resurrected downtown area should represent. The Hariri vision was not especially subtle, but it was effective: the area was to become a centerpiece for Beirut’s once again becoming the Middle East’s financial crossroads, a luxurious hook to draw in foreign capital and capitalists. The area’s physical attractiveness would project an image of modernity appealing to money-makers all over. At the core of the new city’s efforts would be high-end commerce, banking, but also real estate.

The critics quickly cried foul. What kind of city center was this that disqualified part of the society? Here was an opportunity to use the area as a vector of integration, and instead it was being turned into an exemplar of exclusion. Writing in The Beirut Review in 1992, a notable critic of Hariri’s reconstruction plan, sociologist Nabil Beyhum, lamented: “If the objective of reconstruction is to transcend the Lebanese war, then it must reverse the profound sociological changes caused by the war at the level of service, public transportation, road networks, and cultural and economic activities…. Reconstruction must act to regenerate urban society, serving as an example for society as a whole.” Beyhum had no doubt that Hariri’s ambitions, by blocking out many Lebanese, was failing as a “regenerative” experiment, and as one of conciliation.

In retrospect, Beyhum’s judgment was too severe. The downtown area undoubtedly helped the Lebanese “transcend” their war (even if its recent use has threatened to reverse this). It is indeed a playground mainly for the middle class and the wealthy, a pristine area that has offered much less class diversity than the prewar old city. But oddly enough, this stern benchmark for social integration – that all Lebanese should somehow aspire to feel equally at ease in all areas of the capital – while laudable, is also mildly absurd for anyone who knows how cities function.

Downtown showdown

Social stratification is something all cities face, even those that are quite successfully integrated. Far from being an unfortunate phenomenon, the rise of wealthy areas is a necessary component of any city’s economic and social regeneration. It’s happening in Harlem today, and is what transformed London’s Docklands. As Hariri instinctively realized, a prosperous neighborhood appeals to those who are prosperous, and that’s where investment comes from. It’s also true that Solidere’s plans, while they were haltingly developed, leading to the destruction of attractive buildings eminently salvageable, brought residents back to the downtown area. Before 1975, the old city had become a charming but deteriorating 8:00 am to 6:00 pm hub, where few people lived. Its integration only took place in the daytime, as it does today. After dark, its appeal dissipated.

The real challenge for any city is not bringing wealthier areas down to the level of its poorer inhabitants in the name of doubtful integration; it’s making sure that poorer areas can be brought closer to the standards in higher-income areas. That’s why many demonstrators’ antipathy for the downtown area in December was so paradoxical. Protestors showed their displeasure with what the area represented, but delighted in being able to get their message across amid its posh confines.

Michael Young

January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Comment

Smooth as silk

by Riad Al-Khouri January 1, 2007
written by Riad Al-Khouri

The world economy was until recently a cozy club of the countries of the Organization of Economic Co-operation and Development (OECD – a grouping of 30 of the world’s biggest and more prosperous states) and of the multilateral organizations that they largely finance and control, including the World Bank. However, that coziness could now be disappearing, as the role of non-OECD countries in aid, foreign investment, and trade has been expanding over the past few years, with Chinese activity especially notable.

Aid to Africa is a case in point. Total official development assistance (ODA) from the rich European, North American, and Pacific countries that make up the OECD Development Assistance Committee (DAC) to sub-Saharan Africa was about $23 billion in 2005. (Estimates are that 2006 figures will be the same or slightly lower.) Such largesse is of course welcome, but problems sometimes arise when these OECD donors go to Africa and say “do such and such, or else….” Though such ‘advice’ is sometimes reasonable, when political or economic conditions are imposed, the countries receiving assistance comply with difficulty, or at least go through elaborate games pretending to tow the line; otherwise, precious aid could be lost.

Donors from Western and other developed economies abide by certain, more or less, stringent rules and guidelines set by the OECD DAC. Not so non-OECD members, including the Chinese, let Africans take money without accepting any excess baggage in thorny areas such as governance.

Africa’s Silk Road, a book just published by the World Bank on Asia’s new African economic frontier, sums up this new situation by stating that: “China’s economic support to Africa has recently exploded.” In 2002, China officially gave just under $2 billion in development aid to African countries. Since then, official reporting of such figures has ceased, but preliminary estimates from the World Bank suggest that much of China’s official economic aid to Africa to support development of infrastructure is in the form of China Export-Import Bank loan financing and amounted to close to $13 billion in 2003 to 2006 – mainly, in the power, telecom, transport, water and sewerage sectors. At the same time, China is using debt relief to assist Africa, effectively turning loans into grants. The new World Bank book stated: “Since 2000, Beijing has taken significant steps to cancel the debt of 31 African countries. That year, China wrote off $1.2 billion in African debt; in 2003, it forgave another $750 million.” More recently, China’s Africa policy white paper, released in early 2006, foresees additional multi-billion dollar debt relief as part of the country’s economic assistance strategy to Africa, a point it underlined when hosting 48 African countries in Beijing last November at a conference promoting closer co-operation and trade.

The policies of China at home, social stability, industrial investment, and national unity, are more vital to Beijing than political liberalization or the rule of law, so it is unsurprising that the latter aims are downplayed in dealings with Africa. China has cultivated close ties with countries that provide it with commodities and raw materials, regardless of their political records. Recent examples include Sudan and Zimbabwe, which both trounced the threat of international sanctions in part because of Chinese action.

Partly as a result of closer ties with China, African economies generally look better, buoyed by strong demand in China for everything from Zambian copper to gold from South Africa and Angolan oil. This helps to explain African exports to China growing by 48% annually in the past half-decade, compared to 14% during the 1990s, with 10% of Sub-Saharan exports now going to China.

African-Chinese FDI is also rising rapidly, but the volume of such flows is more modest than that of trade. As of mid-2006, the stock of China’s FDI to Africa is estimated at $1.2 billion, with Angola, Nigeria, Mozambique, Sudan, and Zimbabwe accounting for over 80% of the total, and flows to the power sector making up about 40% of all commitments.

China has more or less surpassed Japan, Russia, EU states, and India in terms of economic, military, and political power. This leaves Beijing second only to Washington on the world stage, so China will now enjoy the status of a semi-superpower between America and others, with all the privileges and obligations that implies. Among the latter will be aid, which is still badly needed in Africa and other developing regions. However, the question increasingly posed for the rest of the decade will be: aid on what terms? As the Chinese evolve, with greater wealth and power, their assistance to Africa will also develop, possibly in the direction of more conditionality. Meanwhile, Beijing’s seemingly unencumbered largesse has helped it slip smoothly into Africa – a place in which the West is still struggling.
 

Riad Khoury is an economist, director of MEBA Ltd Amman and a Senior Associate at BNI inc New York  

January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
Comment

War is not the answer

by Claude Salhani January 1, 2007
written by Claude Salhani

When the current political impasse is resolved and the ongoing restoration of Beirut resumes, the Lebanese government – whichever one ends up being in charge – should turn a cluster of the most distressed remaining buildings from the 1975-1990 civil war into a living museum. To hell with the cost.

Somewhere along the Sodeco-Monot axis would be perfect. It would not require much to get such a project underway. Expropriation and some yellow tape, the kind used by police forces around the world to cordon off crime scenes. Come to think of it, yellow tape with the words “crime scene – do not cross” would be ideal to mark part of what was one of the biggest crimes committed in Lebanon’s brief history.

The Ministry of Education should then make it mandatory for all school children from the earliest grades through to baccalaureate to visit the “Civil War Museum” once every year. These visits should be accompanied by a detailed narrative explaining how the country suffered during a war that left much of Lebanon in a state not very dissimilar to the museum.

The object of such an exercise would be to impound into the minds of the Lebanese from an early age just how senseless the war was – and is – and in so doing hopefully plant the seeds among future generations that, as the song goes, war is not the answer.

But, it’s a message that is finding few takers. First there was last summer’s Israeli-Hizbullah war. In its vapor trail we have seen the rising tensions between the Shiites of Hizbullah and Amal and their Christian allies led by retired General Michel Aoun’s Free Patriotic Movement and the Franjieh-led Northern Alliance on the one hand, and the supporters of former Prime Minister Rafik Hariri – the multi-ethnic March 14 movement – on the other. Lebanon finds itself once again in the midst of a dangerous political crisis, the worst since the end of the 1975 civil war. The assassination of 34 year-old Minister of Industry Pierre Gemayel and the simmering street violence also revives the specter of 1975.

(Memo to the Aounists: I am aware that Aoun is not an “ally” of Hizbullah, and that he only has an MOU – a memorandum of understanding – with the organization. But given the fact that the two groups are united in their opposition to Fouad Seniora’s government, it makes him, well … an ally.)

But war won’t happen. It can’t happen. I, like many Lebanese, was there in 1975. I saw Lebanon destroyed one block at a time, one village at a time. It was the work of a people gone mad, a time when logic was replaced by hatred and fear. It was a time when snipers gunned down innocent men, women and even children simply because they lived on the wrong side of town.

The delicate mosaic that comprises the Lebanese political landscape has much changed since 1975 when the divide was clearly between the mostly Muslim west and the Christians in the east. The global landscape is also different. The cold war is over.

In April 1975 the Christian side was exclusively Christian. The other side, typically referred to as Muslim – but which also included Christians – included leftists, communists, Marxists and Palestinian groups. Today, the schism dividing Lebanese society is more political than sectarian, although traditions are hard to abandon and Lebanese political parties remain mostly ethno-religious. There are Christians and Muslims on both sides, the most notable anomaly is the Christian general (retired.) Aoun, who is MOU-ed to the Shiites of Hizbullah.

The hefty Palestinian resistance as a serious military and political force has also disappeared. Many argue that they have been replaced by Hizbullah as the nation’s catalyst for war, but hopes that Hizbullah’s much vaunted discipline will prevail.

Finally, the Christian militias, who called on both Syria and Israel for assistance when outnumbered and out-gunned by the Muslim-leftist alliance, can no longer call on either country.

One would hope that the Lebanese who were there have no stomach for a second round. We now that know there were no winners then, just as we understand there can be no winners now.
Claude Salhani is an international editor and political analyst at United Press International (UPI)

January 1, 2007 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 603
  • 604
  • 605
  • 606
  • 607
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE