• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Comment

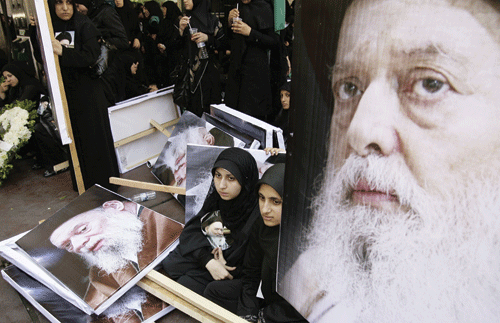
Grand Ayatollah Mohammed Hussein Fadlallah, 1935-2010

by Nicholas Blanford August 3, 2010
written by Nicholas Blanford

Sayyed Mohammed Hussein Fadlallah was a difficult man to pigeonhole, although many tried. From the early 1980s, he became, in the minds of many, synonymous with Hezbollah and was forever described as the group’s “spiritual leader” who had personally blessed the suicide bomber who blew up the United States Marines’ barracks at the Beirut airport in 1983. It was a tag that endured, even though Fadlallah eschewed a formal role within Hezbollah.

The claim that he blessed the Marines’ barracks bomber has also been put down as a rumor deliberately circulated by Lebanese military intelligence during the presidency of Amin Gemayel to discredit the cleric.

Fadlallah, despite being a leading advocate of an activist and modernist Islamism, tended toward dispensing guidance and advice and disdained the parochial obligations of running a political institution. Yet his teachings and writings served as an inspiration for Hezbollah’s founders and he continued to wield influence from afar during the party’s formative years. Among his early followers was a skinny bespectacled youth named Hassan Nasrallah, who even before reaching the age of 10 was a regular attendee at Fadlallah’s sermons in Nabaa.

Even though the official marja (religious reference for followers) for Hezbollah is Iran’s Ayatollah Ali Khameini, it is no secret that many members of the party actually followed Fadlallah. I know of one Hezbollah fighter who was utterly inconsolable on hearing of Fadlallah’s death and in his grief made unflattering comments about Khameini.

Fadlallah was a magnificent public speaker with a showman’s knack for whipping up an audience. But in the 1970s, he faced stiff competition from Imam Musa Sadr for the hearts and minds of the Shia community. Sadr was an Iranian of Lebanese ancestry who had arrived in south Lebanon in the late 1950s and soon made a name for himself as a progressive and dynamic cleric determined to better the lot of the marginalized Shia. He established the Amal Movement in 1975.

Both Sadr and Fadlallah were brilliant orators, but there the similarities ended. Sadr was slim, tall, charismatic, enlivened with boundless energy that saw him holding meetings, lectures and sermons up and down the country. Fadlallah was short and portly, a scholastic figure who centered his activities on his Nabaa neighborhood, glossing over doctrinal differences between Shia and Sunnis and emphasizing the unity of all Muslims.

Sadr’s purview essentially was limited to the communal betterment of Shias in Lebanon within the Lebanese system, while Fadlallah advocated the creation of a modern Islamic state and espoused a universal Islam that ignored man-made frontiers.

Sadr regarded Palestinian militant activities in south Lebanon with misgivings because of the suffering it brought upon his Shia constituents, but Fadlallah embraced the Palestinian cause, considering the eradication of the Zionist state as a moral and Islamic imperative.

Sadr vanished, mysteriously and famously, on a 1978 trip to Libya. For many Shia, dismayed at the more secular direction of the Amal Movement under the subsequent leadership of Nabih Berri, it was natural to gravitate toward the bolder views of Fadlallah.

Fadlallah originally objected to suicide bombings, but changed his stance in the mid 1980s when Lebanon was in the grip of Israeli occupation. In justifying suicide bombings, he said “there is no difference between dying with a pistol in your hand or exploding yourself.” But he pointedly added that suicide operations could not be condoned lightly and that if alternative means of attacking the enemy were available then they should be used instead.

Fadlallah supported Hezbollah’s goal of establishing an Islamic state in Lebanon, but recognized that given Lebanon’s pluralistic society, the attainment of an Islamic state was an impossibility in the short term. His perspective helped shape Hezbollah’s decision in the late 1980s to reverse its outright rejection of Lebanon’s power-sharing system of governance and to submit candidates for Lebanon’s parliamentary elections in 1992.

NICHOLAS BLANDFORD is a Beirut-based correspondent for The Christian Science Monitor and The Times of London


August 3, 2010 0 comments
0 FacebookTwitterPinterestEmail
Comment

Shifty as a desert fox

by Paul Cochrane August 3, 2010
written by Paul Cochrane

As readers of a business magazine, I am no doubt preaching to the converted, but it really does pay to scan the financial pages to know what’s going on with the movers and shakers of this world. If you had confined yourself to reading ‘straight’ news and the op-ed pages, or watching TV news for that matter, you would have missed out on the biggest media deal in the Middle East this year. A deal that has been a long time coming and is set to have major implications for the region’s TV landscape.

In February, global media ‘emperor’ Rupert Murdoch, owner of News Corp, acquired a 9.09 percent stake for $70 million in Saudi Prince Alwaleed Bin Talal’s Rotana Group, which has six TV channels and is the world’s largest producer of Arabic music.

Murdoch has been itching to get into the booming Middle Eastern market to extend his control over the planet’s media consumption, with an empire already spanning the Americas, Australia, Europe and Asia with the Fox network, the Star TV network, Sky News and a plethora of newspapers including The Wall Street Journal   (WSJ) and The Times of London. Signs of News Corp’s entry into the region started with Rotana launching two Fox channels last year. Then came the stake in Rotana, which sparked speculation that a Fox Arabic news channel was in the pipeline.

Bin Talal denied this in February, but in July the prince announced that he is to launch, independently of Rotana, a 24-hour Arabic news channel in partnership with the Fox network. Murdoch’s move into the region then took a further twist in mid-July, with news that British pay-TV broadcaster BSkyB, 39 percent owned by News Corp, is in talks with a private Abu Dhabi investor to launch an Arabic news channel.

Such developments would have previously lit up the news wires and the blogosphere, as happened when News Corp bought Dow Jones, owner of the WSJ, in 2007. Instead, the News Corp-Rotana deal seemed as if it had never happened. Few regional newspapers ran any form of commentary, and the news was nowhere to be seen outside the business pages.

Perhaps editors assumed that Bin Talal’s news channel, whenever it may launch, will have little impact, given that there are 487 Arabic satellite channels already broadcasting in the region. But one might have thought that in the Arab world, of all places, there would have been more than a muted response to the entry of a media empire that banged the drums of war louder than any other organization for the invasions of Afghanistan and Iraq, and, moreover, is rabidly pro-Zionist.

The more likely reason for the media’s silence is more alarming.  Elsewhere, when News Corp expanded, people decried the fact that media consolidation would lead to less diversity in opinions and affect freedom of expression.

Yet in the Middle East, the major media outlets and newspapers have long been in the hands of the few. Bin Talal is the biggest shareholder in News Corp outside of the Murdoch family, at 7 percent, while he owns the majority stake in the Lebanese Broadcasting Corporation’s (LBC) satellite channel and is a stakeholder in Lebanese newspapers An Nahar and Al Diyar. Other Middle Eastern media heavyweights are owned by or linked to Gulf royalty. Clearly, no one wanted to ruffle any feathers or affect future job prospects by critiquing the deal. As Bin Talal is one of the richest men in the world, Murdoch’s buy-in is not solely about further monetary gain.

The prince said as much in February: “The [News Corp] transaction is way, way beyond finance… Rotana does not need to be financed. It has near zero debt.” Perhaps when Murdoch acquires a further stake in Rotana — which he is entitled to do in late 2011, to 18.8 percent — courageous voices in the media will speak up about what a strange tie-up this is, between a Saudi prince and a media mogul whose outlets continuously bash Arabs and Muslims while offering unflinching support for Western and Israeli military aggression in the very region where he is investing.

Or, perhaps, there will just be a short story in the business pages to let us know it is, well, business as usual.

PAUL COCHRANE is the Middle East

correspondent for International News Services


August 3, 2010 0 comments
0 FacebookTwitterPinterestEmail
Comment

The rial’s slow starve of Yemen

by Alice Fordham August 3, 2010
written by Alice Fordham

Yemen’s currency woes do not top global concerns. And yet the wobbling Yemeni rial, having depreciated 13 percent against the dollar since January, could have devastating consequences for the stricken nation, the ripples of which could well wash ashore through the Arabian Gulf and beyond.

When oil prices plummeted more than two years ago, Yemen’s single-resource economy took a pounding, as the government had overestimated its income and overspent. The result was a 2009 deficit around 10 percent of GDP: crippling for a country unable to borrow from international financial markets and whose primary means of raising funds is to borrow from its central bank and sell foreign currency reserves.

International Monetary Fund policy advice and some aid have reduced the deficit, but the finance ministry predicts it will still be 7.7 percent of GDP in 2010.  Further problems have come in the form of a national shortage of dollars. Yemen imports nearly everything it consumes, and a policy designed to make importing easier and more profitable saw low taxes on imported goods last year. Reliable statistics are hard to come by in Yemen, but Deputy International Planning Minister Hisham Sharaf said that luxury goods, including cars and electronics, came pouring into the country as never before. Exporting dollars for imported goods, traders have depleted dollar reserves, which stood at $6.2 billion in March, their lowest level in five years. This dollar demand consequently boosted its value over the rial.

Respected economists also allege that as much as $3 billion dollars has left the country in money-laundering activities. Political analyst Abdulghani al-Iryani, however, reckoned that sum to be on the high side, and said that the more common practice was for people to dump their rials for dollars and stash them in Dubai banks, exacerbating the dollar shortage and leaving the rial ever-more vulnerable.

Recently the rial has held stable on exchange markets, but only because the government has propped it up through drawing on some $1.1 billion in foreign currency reserves; this is unsustainable and would devour these reserves within two years. As long as the pressure on Yemen’s economy is maintained, oil supplies dwindle, gas exports remain negligible, investors are scared and no cash injection comes, the rial’s fall is inevitable.

How much it will fall is debatable: optimists hope for a gradual, controlled descent, while pessimists foresee a rush to change assets to dollars and a possible run on the banks. Even the current stability measures are harmful. Interest rates, for instance, are being held around 20 per cent, which businessmen say is preventing them taking out loans to expand or start businesses.  Given that almost all Yemen’s food is imported, food prices have risen and will rise more. Yemeni consumers are fairly thin already and will have to tighten their belts further, despite there being more malnourished children here than anywhere in Africa, with the World Food Program classifying a third of the population as “acutely hungry.”

High food prices in 2007 sparked riots. Yemen is critically unstable, and large parts of the non-urban areas of the country are ungoverned, with Houthi rebel groups in the north, an increasing Al Qaeda presence and secessionists in the south. The IMF and World Bank, along with the government, are attempting to improve the situation. The bloated civil service has had its pay frozen and last year’s Ramadan bonus was cancelled. Massive government fuel subsidies, which benefit the rich far more than the poor, have been cut slightly, and a general sales tax has been introduced targeting importers.

There is talk of helping Yemen move from an oil to a non-oil economy, encouraging fishing, mining and tourism. But these are slow, long-term changes difficult for a country hanging on the edge of civil war and bankruptcy, with dwindling income, growing population, chronic unemployment and rapidly-diminishing savings. It is also an open secret that those close to the top of Yemen’s opaque power structure benefit from oil subsidies and unreformed business laws.

Western powers worried about Al Qaeda, and Gulf countries worried about a failed state on their borders need to look to the nitty gritty of the Yemeni economy. They should use their leverage with the government to cut corruption, slash fuel subsidies and get Yemenis trained and internationally employed in Saudi to help rebuild Yemen, one rial at a time.

ALICE FORDHAM is a correspondent

 for The Times of London


August 3, 2010 0 comments
0 FacebookTwitterPinterestEmail
Comment

American imports of influence

by Riad Al-Khouri August 3, 2010
written by Riad Al-Khouri

In praise of free trade, 19th century British politician Richard Cobden described it as “God’s Diplomacy,” bringing people together to prosper. Taking a page from his book, the United States has successfully applied this idea in the region, using trade to further political ends even as America’s traditional Middle East diplomacy stumbles.   

This regional success for America began with the launch of the Qualifying Industrial Zone (QIZ) model in the mid-90s, allowing joint Israeli-Jordanian output to enter the US duty-free, mandating 7 to 8 percent Israeli value-added input into a product as one condition for the trade privileges. QIZ resulted in massive Jordanian garment exports to America, reaching a peak of over a billion dollars annually. So successful was the model in promoting trade that Egypt got the same privilege — the Israeli component in the Egyptian case being 11.7 percent — and started in 2005 to sell textiles and apparel to the US, with those exports jumping to $764 million in 2009.

On the political side, QIZ has been another way for the US to both support Israel economically and effectively buy off Jordanian and Egyptian complicity with the Jewish state, thus furthering America’s political agenda in the region.

Investment in a QIZ is particularly attractive to industries such as textiles and clothing, which are subject to high US tariffs. Consequently, 80 percent of QIZ companies in Egypt and almost all of those in Jordan produce such articles, with big-name US buyers including, among others, Wal-Mart, Van Heusen and JC Penny. Around the States these past few months, I saw more of these products, labeled “QIZ made in Jordan” (or Egypt). This is a far cry from 15 years ago, when it was almost impossible to find Jordanian products on sale in the US, and very rare to see items from Egypt.

There were times when almost the only things our region exported to the rich markets of the West were crude oil and a few other minerals in raw form. By the 1980s, with the expansion of immigrant communities, some foods joined the list of regional exports, as Lebanese hummus and such became available on Western supermarket shelves.

The counterargument runs that selling these ethnic products is easy and ultimately a small niche, while exporting garments to be sold by Wal-Mart is a poor man’s game, so all this exporting hubbub is not really making people rich through higher value-added products.

Could this pattern now be changing? The answer from Egypt, Jordan, and a few other countries in the region seems to be yes. Egyptian QIZs are now kicking in with furniture, leather products, footwear, and glassware. Jordan, which has had a free trade pact with the US since 2000, goes beyond QIZ garment production and has started exporting a growing breadth of goods to America, including air conditioning equipment, branded pharmaceuticals and cosmetics, among many others.

Of course, the hummus and falafel mixes are still there, but in increasingly sophisticated form, and joined by higher-end goods such as spices, herbal tea, and burghul wheat — products that have also penetrated Europe Union with help from EU free trade deals with many Arab states. Not that this is a simple process: such hurdles as EU technical requirements and US Food and Drug Administration product guidelines have to be negotiated, but regional exporters are increasingly managing to comply with requirements of Western markets.

The image of a Middle East exporting only crude oil and crude hummus is fading as regional exporters manage to penetrate Western markets with a widening variety of higher value-added goods, thanks to free trade deals. The next big surprise on this score could even be the Syrians, whose commercial pact with the EU may be coming on stream soon, after which Syria’s industrial exporters will no doubt begin invading European markets.

Given the current state of the regional peace process, however, God’s Diplomacy may take a little longer to bridge the divide between Damascus and Washington.

RIAD AL-KHOURI is a senior economist at the William Davidson Institute at the University of Michigan in Ann Arbor, and the dean of the business school at Lebanese French University in Erbil, Iraq

August 3, 2010 0 comments
0 FacebookTwitterPinterestEmail
Comment

Sanctions stalk Iran’s free market

by Gareth Smith August 3, 2010
written by Gareth Smith

As Iran’s 2005 presidential election approached, a broker active in Tehran’s stock exchange was downbeat. “Pessimists look at the elections and see no new ideas and no new faces,” he told me. “They worry that pressure from outside means tighter rule at home. And that, in turn, means more bad politics, more bad economic policy and no markets.” Five years later, his words appear prophetic. Expanded economic sanctions imposed by the United States and — to a lesser extent — the United Nations have curtailed Western investment in Iran’s economy, strengthening the role of the state. The conservative president Mahmoud Ahmadinejad has presided over a crackdown on the reformist opposition and reversed the sluggish economic liberalization that took place under the previous president, Mohammad Khatami. Strange, then, that the Tehran stock exchange (TSE) should be at record levels, with the most-quoted index, Tepix, reaching 15,361 in the third week of July, above even the bull market that peaked at 13,882 in late 2004. But today’s “boom” at the TSE is very different to 2003 and 2004. In those days, expatriate money was flooding back, feeding rising prices in stocks and real estate. At the same time, private banks were expanding, Western energy companies were signing deals for developing Iran’s oil and gas resources, and Tehran was in talks with the European Union over its nuclear program.

The current rise of stocks in Tehran takes place in an exchange more and more dominated by state, or quasi-state bodies, which have proved adept in exploiting the Ahmadinejad government’s privatization policies. Funded to a greater or lesser degree by oil revenue, the state sector is far better placed to survive sluggish economic growth, currently at 2 percent according to the International Monetary Fund. The retirement fund of the Revolutionary Guards was also involved in the consortium that last year bought a 50 percent plus one share stake in the state-owned Telecommunications Company of Iran (TCI).

“The government and quasi-government bodies have made the TSE far more of a co-operative than a competitive game,” an Iranian economist told me. “As a general rule, in developing or risky economies cash dividends are more prevalent [than retained earnings] and pay-out ratios higher. Buying and selling stocks can help increase an extraordinary income to make up for declining profits from normal businesses. And of course, we should not forget that high oil revenue over recent years, despite the falls since 2008, has built up greater liquidity and that there are a limited number of investment opportunities in Iran.” Isolation cuts both ways, and sanctions make Iranians reluctant to invest abroad.  Government and quasi-government bodies are especially cautious. Another factor in the bourse’s boom, said the economist, was a perception that political unrest after last year’s disputed general election had died down: “The surge in the TSE began around five months ago as people perceived an apparent stability after nearly a year of uncertainty.” The buoyancy of the Tehran stock market has also attracted liquidity from falling markets in the region and elsewhere. Turquoise, an investment firm majority-owned by the London Stock Exchange, offers an Iran equity fund and has described the TSE as “one of the most under-valued emerging markets in the world.”

Traders detest the growing politicization of the Iranian economy. Many Western media outlets described last month’s protests in a Tehran bazaar against tax rises as a potential return to the strikes that helped topple the Shah in 1979. On the other hand, Hussein Shariatmadari, editor of the leading conservative newspaper Kayhan, recently wrote that officials were slow to take action against “a handful of prosperous capitalists” in the bazaar. Shariatmadari has been a strong supporter of Ahmadinejad and is clearly in no mood to pander to advocates of lower taxes or market liberalization.

Across the board, sanctions weaken the private sector. If the US is successful in blocking the insurance of goods being transported in and out of Iran, then the government may well take over the responsibility. 

As the broker said back in 2005, “more bad politics, more bad economic policy, and no markets.”

GARETH SMYTH is the former Tehran correspondent for the Financial Times

August 3, 2010 0 comments
0 FacebookTwitterPinterestEmail
Society

“Those who tell the stories rule society”

by Mark Helou August 3, 2010
written by Mark Helou

The above quote from Plato has never rung more true. At a time when perception is stronger than reality, the people who can tell the stories and influence public opinion are now as powerful as the strongest armies in the world. Heads of media conglomerates are feared and even revered by most heads of state and politicians, who are fully aware that they can ‘make or break’ them.

The power of the media today is such that it can even make or break the image of a whole country. With the proliferation of 24-hour news, satellite TV, social media and the Internet, influencing people’s perceptions of a country has never been easier. Inhabitants of the “global village” are continuously subjected to a stream of movie and TV productions that also contribute to forming numerous stereotypes and images, which they end up perceiving as reality.


This is not to say that motion pictures and television are the only, or the most influential media channels, but they are often the channels most able to transcend linguistic, ethnic, social, and cultural barriers. Whether you are watching a Charlie Chaplin or a Steven Spielberg movie in English, Spanish, or Chinese, chances are, you are going to understand the messages behind it and sub-consciously pick up and form what you believe are your own ideas and perceptions.

How a country is perceived by investors and visitors can make the difference between economic prosperity and stagnation – especially for a state such as Lebanon, which is eager to attract investment and rebuild its tourism industry as an economic backbone.

A nationwide thinking process around this issue is all the more relevant today, as Lebanon is at the threshold of an extremely promising touristic season, confirming the country’s potential as a destination of choice for tourists of all nationalities. Its image should thus be optimized to take full advantage of this potential. 

Sadly, the media – especially Hollywood – continues to portray Lebanon as a land of war and violence, perpetuating an image of the country as being unsafe, dominated by extremists, or a haven for terrorists. There are many examples of Hollywood movies such as Syriana, Spy Game, Naked Gun and, more recently, From Paris with Love, in which silver screen stars use Beirut as a metaphor to express a state of mayhem and anarchy. While we might think that this is only done in the context of a movie, and will not have any lasting effect, emphasizing again and again that same message will ultimately affect global opinions of Lebanon, especially in the many without first-hand knowledge.

Shorthand for destruction

The same applies for other media outlets such as TV and newspapers, where Beirut has been constantly used as shorthand for destruction and anarchy. Whether there is intentional malice behind it or not, this further confirms the fact that Beirut remains a byword for chaos. This originated with the stream of horrific images that came out of Beirut during the Lebanese Civil War. Among the first conflicts in the era of 24-hour news and live broadcasting, and also involving foreign deaths and hostages, the 15-year conflict seems to have burned an indelible mark on the city’s reputation.

The fact that Beirut was a sophisticated westernized city in the eyes of the international community made its rapid descent into mayhem all the more striking, rendering it a sensationalist example of a ‘good thing gone bad.’

The interest that the international media had in Lebanon during the war years was such that the terminology “Lebanonization” or “Libanization” even became part of the media and political analysts’ lexicon. Such terms even made it into dictionaries as synonyms for the breakdown of a country into various religious communities.

Believing the hype

But the media can not only break a country’s image; it can also help build it to the extent where the line between fiction and reality often becomes a blur. 

Take the case of the United States: While Hollywood and the US media in general have often portrayed Lebanese and Arabs as violent, backward, and blood-thirsty terrorists, they were able to create an image of the regular American as the quintessential hero in the waiting, always willing to sacrifice himself to save the world. Movies like Armageddon and Independence Day are only a couple of the scores of films that have helped build the image of America, among its citizens at least, as “the land of the free and the home of the brave.”

Westerns also succeeded in the acrobatic task of portraying the settlers of the new world as the “good guys” while their Indian victims were confirmed as all-time villains, and series like “Sex and the City” have established the image of New York as glamorous and romantic, downplaying its darker side.

What the media has effectively done is to entrench the feeling among Americans that they have a responsibility to lead the world, that they are the guardians of humanity. In that sense a cliché becomes a stereotype, and a stereotype becomes a reality for many.

One thing we can learn from Hollywood is that the only way for us to amend Lebanon’s image is by using the same medium that got us here in the first place: the power and reach of the mass media.

Changing scene

So far, there have been a number of sporadic and ad-hoc efforts, some spearheaded by the government and the Ministry of Tourism, and others that came spontaneously or as a result of a particular media’s interest in Lebanon, such as the New York Times article that ranked Lebanon as the number one destination to visit in 2009, the article in Paris Match focusing on Lebanon’s  joie de vivre, or the report on CNN highlighting the fact that Beirut has become a “top city to party in.”

That said, a concerted national effort to develop a clear and holistic communication strategy to rebuild Lebanon’s image is still lacking.

We have to decide how we want Lebanon to be perceived and which key attributes we want communicate. Do we want Lebanon to be seen as a place for those looking to party all night long and enjoy the naughtier side of the country? Do we want Lebanon to be seen as a perfect getaway for family relaxation and for those looking to enjoy its mountains and beaches? Do we want Lebanon to be positioned as a place filled with history, focusing on our archeological heritage, or do we want to position Lebanon as a hub for business and investments instead?

Media campaigns should focus on communicating Lebanon’s positioning and edge, as should politicians and civil servants abroad in all their meetings and conferences.

Seeing how the movies can help build a country’s image, the government must support the local film industry; several home-grown offerings have already started shifting the public perception of Lebanon away from that of a bombed-out haven for terror and fundamentalism.

But more importantly, we as Lebanese citizens should take advantage of the current emergence of new media channels and the drastic decrease in production costs that have come about thanks to the omnipresence of digital technologies.

The global media and communication scene has reached a new stage where anyone can make themselves heard across the globe, and where creating and disseminating impactful content has become accessible to each one of us.

As such, changing existing perceptions or creating new ones becomes only a matter of creativity, a creativity that each Lebanese citizen can exercise in order for us to help successfully build the image that truly reflects the history, values and uniqueness of our country.


August 3, 2010 0 comments
0 FacebookTwitterPinterestEmail
Real Estate

Cityscape speaks – Damac Properties

by Nada Nohra August 1, 2010
written by Nada Nohra

Our message over the previous years has been growth, new projects, new demand, but this year it is very much construction and delivery,” says Niall McLoughlin, senior vice president of corporate communications at Damac Properties. With that message, Damac has been marketing every stage of its progress, assuring buyers and investors that the units they bought will be delivered on schedule. Last year, Damac announced that it had 11,313 units under construction. The company has delivered 3,029 in the last 12 months, and will deliver the rest by the end of 2010.

McLoughlin explains that Damac has been working with customers and transferring their investments from longer-term projects to the ones under construction or that are almost completed. “We have approached our customers on a case-by-case basis. It is a winning situation for them because they get the product earlier. It may also be a question of consolidating their portfolio to ease payment terms for them,” says McLoughlin. This strategy has been very successful, as it helped decrease potential payment defaults, which is the last thing either developers or customers want.

The company has also dedicated a new management team to focusing on customer queries, handling them case by case. “Losing a customer is not good for us, and also not good for the customer,” says McLoughlin.

Currently, Damac is not planning any news launches. The company is issuing enabling works contracts for its projects in the United Arab Emirates and Qatar. “By the end of the year, we anticipate awarding two to three main contractor works with a value of over AED 1billion [$272 million],” explains Mc Loughlin.

As for the long term, McLoughlin says the company will be looking to expand regionally, but not before the time is right. “Now the market is not ready for expansion, so our short-term objective is consolidating and constructing what we have launched,” he adds. 


August 1, 2010 0 comments
0 FacebookTwitterPinterestEmail
Finance

Regional equity markets

by Executive Editors July 23, 2010
written by Executive Editors

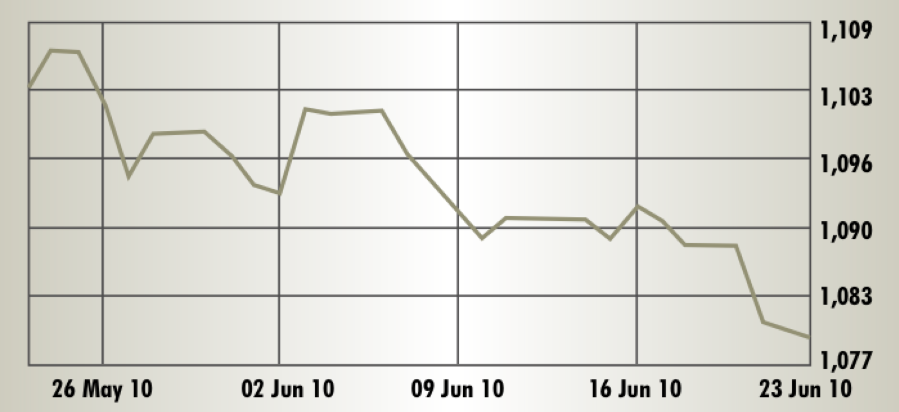
Beirut SE  

Current year high: 1,200.49    Current year low: 991.49

>  Review period: Closed – June 22 at 1079.28 Points          Period Change: -1.5%

The MSCI Lebanon index trended lower in a not overly dramatic fashion in the June 2010 review period, leaving all the excitement for Lebanon’s army of devoted football fans. When compared with its high of 1,180.98 points for the first half of 2010, the index softened by just over 100 points. However, the banking sector could show off another victory with a 31% y-o-y rise in its Q1 2010 aggregate net profit of the top 12 lenders. Market cap leader Solidere scored a goal of $189 million net profit last year in a stable performance.

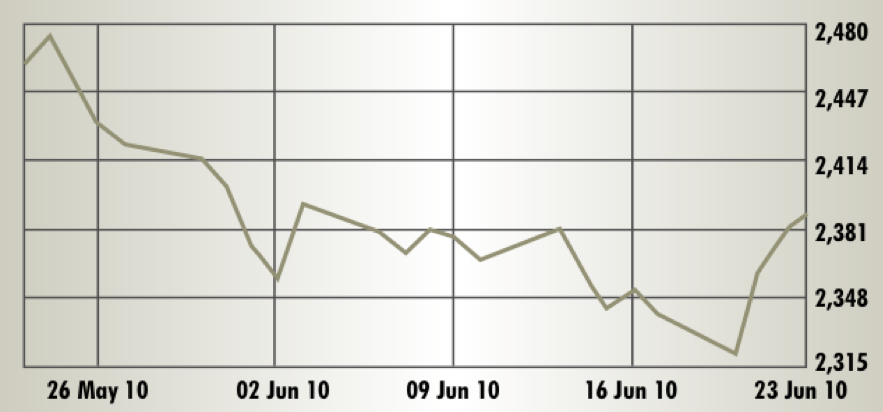
Amman SE  

Current year high: 2,744.07                Current year low: 2,320.14

> Review period: Closed – June 23 at 2,388.94 points          Period Change: -0.5%

Having just passed across a multi-year low of 2,320.14 on June 20, the best wish for the Amman Stock Exchange may be for this to have been rock-bottom for the market and for new stamina to appear after the disappointing first-half. Sadly, endurance training seemed to be of no help to the insurance sector, which dropped 15.2% at the bottom of market trends. Banking, industrial, and services sectors, by contrast, traded range bound with the ASE general index and banking even achieved a tick into positive territory, starting from June 21.

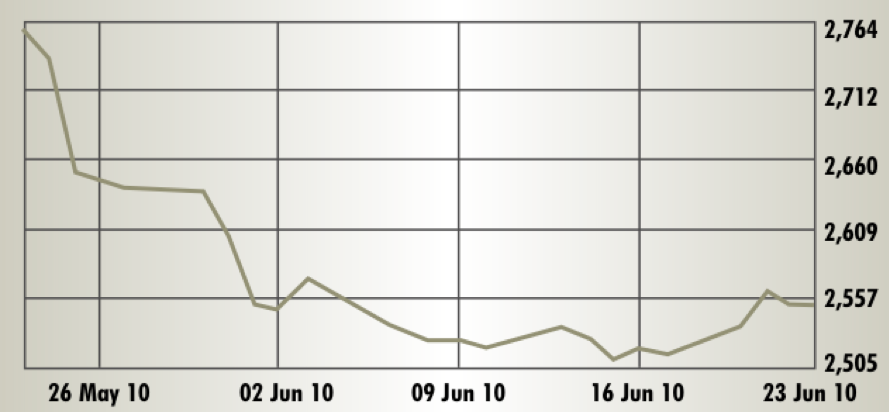
Abu Dhabi SM  

Current year high: 3,239.74                Current year low: 2,467.04

> Review period: Closed – June 23 at 2,551.39 Points                      Period Change: -2.0%

Abu Dhabi’s exchange has dropped a sizeable 7% from the start of 2010, though this decline is only half as steep as the plunge Dubai’s DFM took over the same period. The ADX exhibited some noticeable volatility in June and sector indices fluctuated in uncoordinated trends. The only sector index to end the period in positive territory, however, was the industrial index. Market cap leader Etisalat weakened 2.4% as Methaq Takaful and Gulf Livestock were beaten down 28.4% and 26.8%, respectively. The best gainer was Finance House, up 18.6%. 

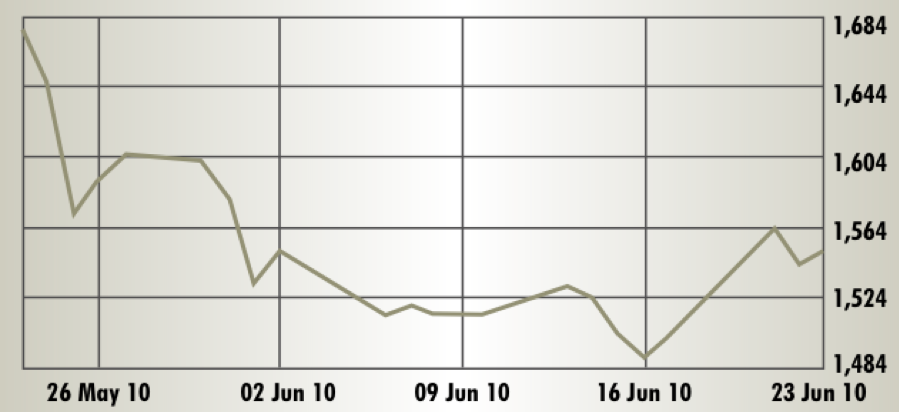
Dubai FM  

Current year high: 2,373.37                Current year low: 1,487.93

> Review period: Closed – June 23 at 1551.19 Points           Period Change: -1.8%

The ‘lord of the dip’ award goes hands-down to the Dubai Financial Market for the first half 2010. With the halfway point for 2010 quickly approaching, the DFM was down 14% for the year to date at its June 23 close and danced around 1,500 – levels last seen in February 2009. No vigor, no football competition, no cultural happening seemed to energize the DFM, where a 10.7% climb of Aramex stock was the only upward outlier. The vast majority of shares tended to the red, as did the sector indices, except for transport. 

Kuwait SE  

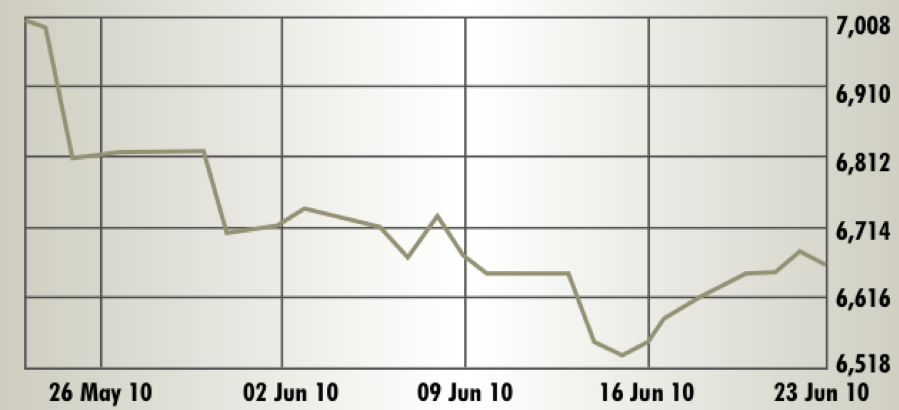
Current year high: 8,140.20                Current year low: 6,528.60

> Review period: Closed – June 23 at 6,653.00 Points          Period Change: -0.7%

The fact that the Kuwait Stock Exchange closed less than one percent down in the review period cannot soften the harsh realities of the bourse’s massive slide in May, which didn’t stop until the index hit a 15-month low of 6,528 on June 15. It remains to be seen if this will be rock bottom for 2010, or if investor nerves have worn so thin that share price performance in Kuwait will fall further. Banking and industry were better than the general index; real estate and investment underperformed.

Saudi Arabia SE  

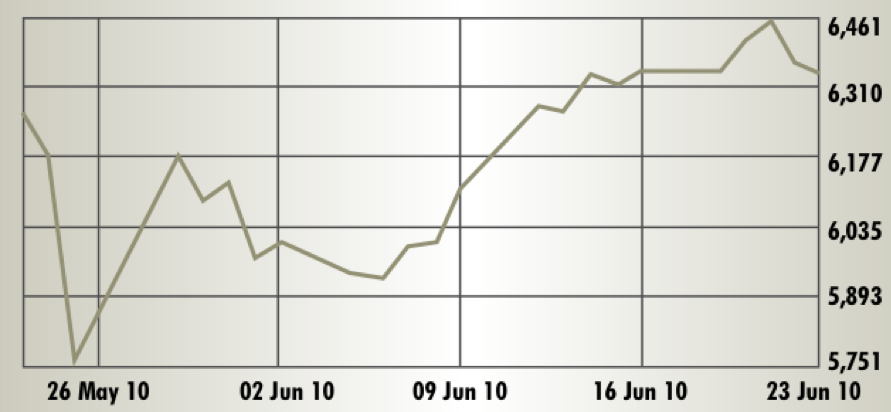
Current year high: 6,929.40                Current year low: 5,407.31

> Review period: Closed – June 23 at 6,343.47 Points          Period Change: 3.6%

After its immune system took a hit from various contagions in the second half of May, the Saudi Stock Exchange resurged in June, in a manner of speaking. Compared to its GCC peers, the SSE index was second best performer in the review period and for the year to date it is still the best student in the GCC securities college, with a 3.6% climb. Most SSE sub-indices moved range-bound with the TASI in the review period; a news-driven 23.1% spike in the Energy and Utilities index was the upward exception.

Muscat SM  

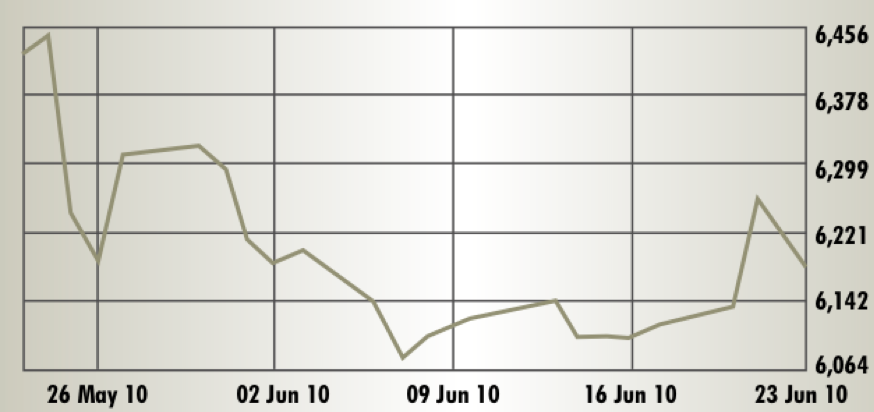
Current year high: 6,933.75                Current year low: 5,263.94

> Review period: Closed – June 23 at 6,173.33 Points          Period Change: -1.3%

The Muscat Securities Market had more losers than winners in the review period and the general index seemed to be finding its feet after two months of down pressures. While the industrial sub-index was the June market’s consistent best performer, banking had the most erratic ride. Brokerage Financial Services Co was the MSM’s best individual performer in June and shot up 19.6%, reversing a comparable drop it had suffered in May. National Mineral Water Co found no such mercy, dropping 21.6% from June 1 to 23.

Bahrain SE  

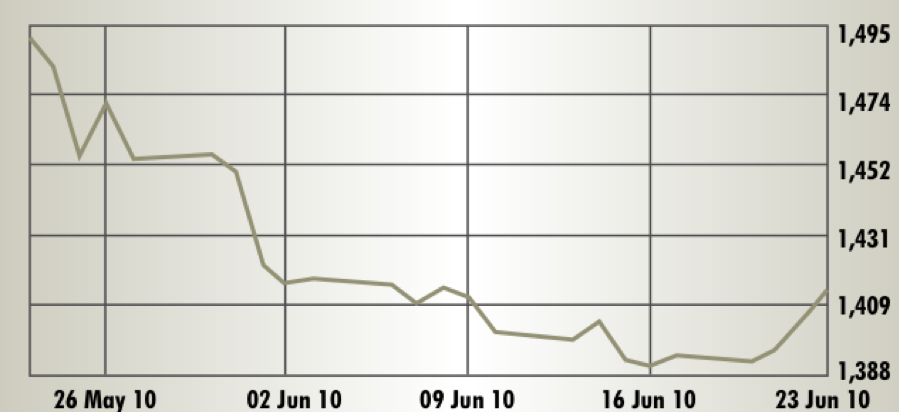
Current year high: 1,613.01                Current year low: 1,390.81

> Review period: Closed – June 23 at 1,413.19 Points          Period Change: -2.6%

Although the BSE’s bow beneath the 1,400 point line between June 15 and June 20 was merely a six-month low, and although the year-to-date performance of minus 3.1% is only the fourth worst in the seven GCC security markets, Bahrain’s investors will still be hoping the second half of 2010 bestows more blessings than the first.  While Esterad Investment fell 28.3% in the review period, a gain of 2.63% was made by Al Salam Bank – Bahrain, the period’s best performer.

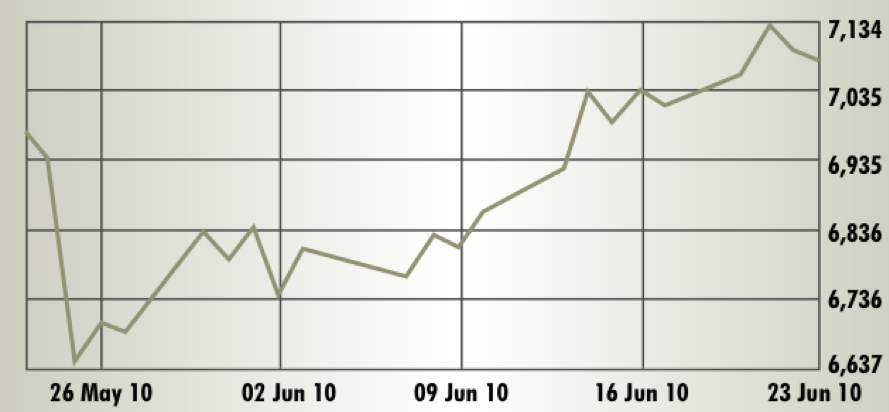
Doha SM  

Current year high: 7,801.33                Current year low: 5,731.30

> Review period: Closed – June 23 at 7,072.08 Points          Period Change: 4.2%

Though the Gulf region has no team in the World Cup to bring home glory,  the Qatar Exchange took this month’s trophy for greatest market vigor. After its epic 1,250-point slide between April 13 and May 25, the ensuing gains of June made for a picture perfect V-shaped performance, albeit a V that is still rather short on the upside. The QE’s four sector indices all were positive, with insurance coming out on top as best performer. Was it because the country iterated another energetic bid to host a World Cup (2022)?  

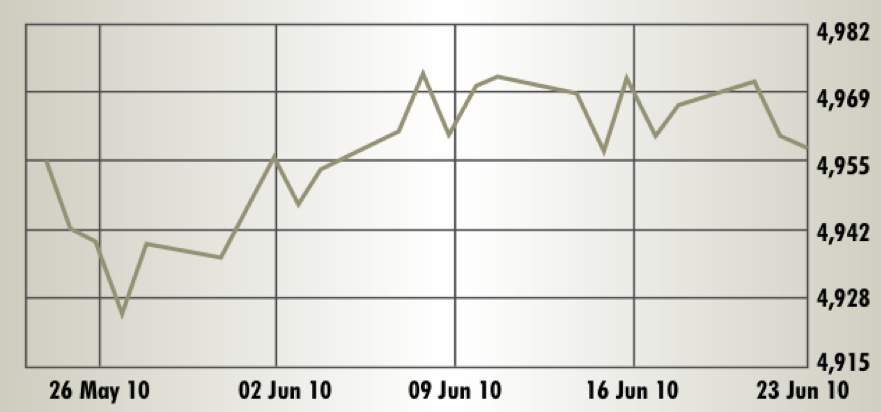
Tunis SE  

Current year high: 4,772.39                Current year low: 3,337.48

> Review period: Closed – June 23 at 4,957.85 Points          Period Change: 0.4%

Minimal volatility and sideways trading at the ceiling of historic performance was the game on the Tunisian Exchange. The period close represented a tiny retreat, by not even 15 points, from a new index peak of 4971.35, which was scaled on June 21. The market reported a smashing success in the initial public offering of cement maker Carthage Cement. The $89 million share offering for 49.8% in the company’s stock was oversubscribed more than 13 times and the stock debuted on June 22 with a first-day change of 26.3% when compared with the issue price.

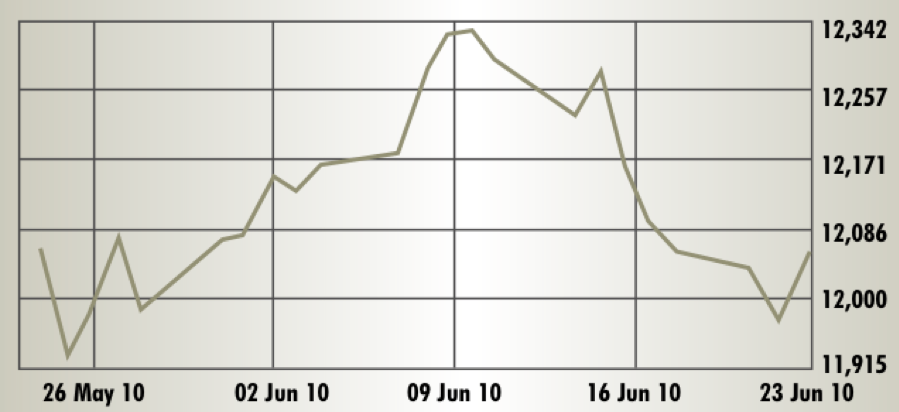
Casablanca SE  

Current year high: 12,457.59              Current year low: 9,997.56

> Review period: Closed – June 23 at 12,055.36 Points        Period Change: -0.1%

The June 2010 match between bulls and bears on the Casablanca Stock Exchange was a draw. As the impact of the downturn in most global markets in late May caused the MASI to correct from record highs of almost 12,500 points, the optimists dominated on the pitch in the first eight sessions of the review period, but the bears came back in the second eight sessions for a flat net balance. Market cap leader Maroc Telecom advanced 4.7%, and leading bank Attijariwafa dropped 1.8%.  

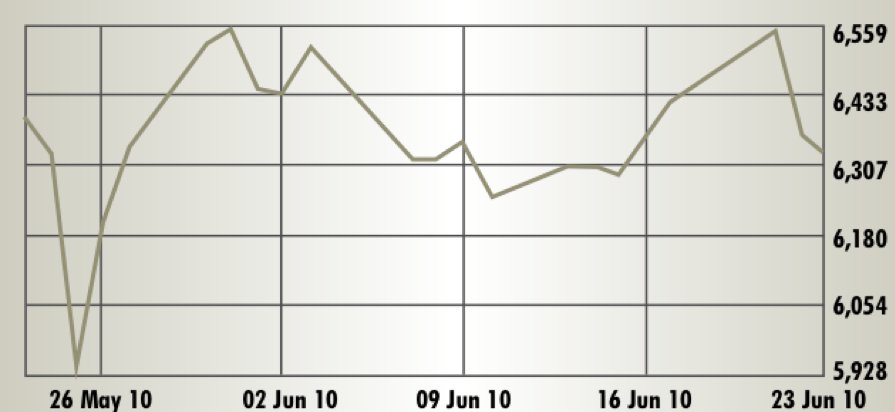
Egypt CASE  

Current year high: 7,603.04                Current year low: 5,229.40

> Review period: Closed – June 23 at 6,319.00 Points                      Period Change: -3.5%

The highest volatility in North African markets marked the flow of trade on the Egyptian Stock Exchange in the June 2010 review period. After a massive drop and sharp rebound between May 18 and 31 into the mid 6,500 range, the EGX 30 fell more than 300 points to June 10, recovered by almost exactly the same point score, and weakened again. Telecom Egypt managed a flat performance but Orascom Telecom lost 14.7% as analysts questioned its planned divestment from Algeria.

July 23, 2010 0 comments
0 FacebookTwitterPinterestEmail
Feature

A species sinks

by Executive Editors July 17, 2010
written by Executive Editors

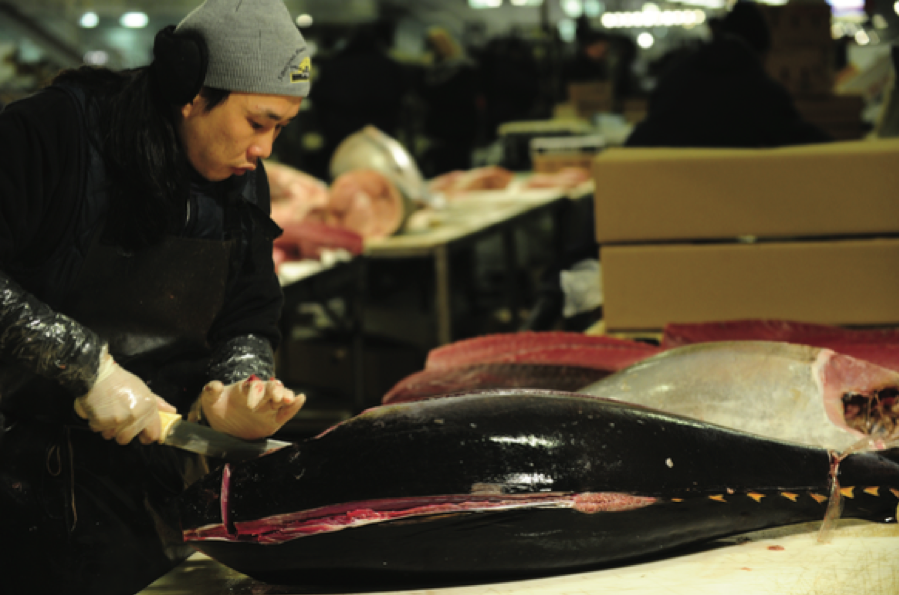
Blame it on the sushi. The rising popularity of the Japanese delicacy has brought the northern bluefin tuna to the brink of extinction, while at the same time profoundly altering the dynamics of fishing in the Mediterranean.

On June 9, the European Commission closed the Mediterranean bluefin tuna season, which had opened just three weeks earlier, because the annual quota had already been caught — predominantly by the ultra-efficient industrial fishing vessels sailed by Spain and France. At 13,500 tonnes, the 2010 quota was already set 40 percent lower than 2009 — a concession to environmental organizations, which had argued for a complete ban on bluefin fishing this year. For them, the European Union’s decision to halt bluefin fishing is too little, too late.

The Mediterranean’s stock of bluefin has shrunk to less than 15 percent of its original size due to overfishing.

“Bluefin tuna must be given a break,” said Sergi Tudela, head of fisheries at the World Wildlife Federation — Mediterranean. He advocates a global trade ban as the only way to ensure a sustainable tuna fishing industry in the Mediterranean. But the latest fishing ban applies only to EU countries — non-European fishermen will continue to fish the waters. Greenpeace believes that European boats will circumvent the ban by flying non-EU flags and gravitating to territorial waters off the North African coast, which are harder to regulate. 

Japan, which receives around 80 percent of the world’s tuna catch, has repeatedly moved to block an international tuna trade ban by the United Nations. Similarly, few Mediterranean countries are volunteering to give up a lucrative source of income, as tuna prices have shot up in recent years with the global popularity of sushi. A ton of the fish now sells for $1,000, up from $300 in 2005.

On the other side of the coin, declining supplies have had a deep impact on local fishing communities, especially in North Africa, where fishermen employ smaller vessels and outdated technology. In Morocco, where fishing is a pillar of the agricultural industry, tuna catches dropped 96 percent between 2006 and 2007, from 8,800 tons to 343 tons, leading to the discontinuation of local tinned tuna brand Tam. 

Some North African countries have increased measures to protect their dwindling fish resources. In April 2010, Tunisia passed a bill aimed at preventing illegal fishing in its territorial waters, where a tuna recovery program was initiated in the summer of 2009. Foreigners found fishing in these waters will be fined up to 300,000 dinars ($196,860), while Tunisian fisherman will be penalized up to 100,000 dinars ($65,620).

However, Africa remains a weak spot for the prevention of bluefin exploitation. The Gulf of Sidra off Libya, previously the largest breeding ground for Mediterranean bluefin, has been identified as the greatest site of illegal fishing in recent years, and yields approximately 40 percent of total bluefin catch.

While Libya has relatively scant fishing production itself, the country sells major European companies access to these waters. As a result, it has been one of the most vocal opponents of a bluefin fishing ban, which it believes disadvantages the developing nations that rely on the trade. 

At the Convention on International Trade in Endangered Species held in March 2010, Libya’s delegate forced a vote on the matter before any debate had taken place. The result was 68 votes against and 20 for, with 30 abstentions, clearly demonstrating that “governments are not ready to adopt trade bans as a way to protect species,” a spokesman for the UN told international press. In the minds of environmentalists, this nearsightedness has sealed the fate of the bluefin tuna. 

July 17, 2010 0 comments
0 FacebookTwitterPinterestEmail
Economics & Policy

For your information

by Executive Editors July 11, 2010
written by Executive Editors

Inking free trade

Lebanon, Syria, Jordan and Turkey came to an agreement June 10 to allow the free flow of goods between the four nations. Under the deal a “Cooperation Council” will be set up to tackle long-term strategic planning and implement a free movement zone. The agreement also included the lifting of visa obligations for individuals traveling between the countries. The deal was agreed by the foreign ministers of each country on the sides of a Turkish-Arab cooperation conference in Istanbul. The statement issued also stated that Turkey and Lebanon were required to complete a bilateral agreement before the multilateral agreement could go ahead. Three days later Lebanon and Syria also inked 15 memorandums and two executive programs covering the environment, consumer protection, agriculture, tourism, culture, justice, education, higher education, economics and vocational training.

Budget steps closer to approval

After several months of delays and almost a full five months past the constitutionally mandated deadline for Parliament to ratify a national budget, the Council of Ministers approved a version of the budget that was then passed on to Parliament for deliberation. If passed, the budget will be the first the country has seen since 2005. The draft budget was first submitted in April by the finance ministry and has been heavily debated by the opposition, specifically Telecom Minister Charbel Nahas and Speaker of Parliament Nabih Berri, who raised concerns about off-budget items and budget increases, respectively.  The proposal itself contained a total deficit of $4.3 billion based on a projection of  $9.2 billion in revenues — an 8.6 percent rise on 2009 — and $13.4 billion in expenditures. A total of $4.3 billion will be spent on servicing Lebanon’s public debt, which reached $51.48 at the end of April according to the latest available figures from the Association of Banks in Lebanon, constituting a year-on-year rise of 7.7 percent. The total debt at the end of the year according to the proposed budget is estimated to reach $55.18 billion, or a debt-to-GDP ratio of 147.47 percent, based on a estimated real growth of 4.5 percent and an inflation rate of 3.7 percent. According to the Central Administration for Statistics, Lebanon’s consumer price index, the primary indicator of inflation, had risen by 4.9 percent year-on-year as of the end of May.

A new plan for power

The Council of Ministers, Lebanon’s cabinet, approved a proposal on June 21 to overhaul and reform the country’s decrepit electricity sector. The plan, originally proposed by Minister of Energy and Water Gebran Bassil in March, lays out a 10-point, four-year agenda to move Lebanon toward producing more electricity through cheaper and more environmentally friendly natural gas, as opposed to the current use of fuel oil. The plan aims to increase the country’s production capacity from the current 1,600 megawatts (MW) to 4,000 MW by 2014, and then to 5,000 MW in 2015.

By 2014 it is envisioned that the country will enjoy 24-hour electricity. As part of the plan, the loss-making sector should be breaking-even by 2014 and generate a profit the following year. This would be achieved through cost cutting measures associated with weaning off fuel oil, and increasing the tariff structure of Électricité du Liban (EDL), Lebanon’s publicly owned electricity provider. The strategy earmarks a total of $4.87 billion to boost production and will be funded by several sources: the Lebanese government ($1.55 billion), the private sector ($2.32 billion) and donor countries ($1 billion). However, for all of the elements of the plan to be implemented, Bassil notes that several decisions will need to be approved by himself, EDL, the cabinet and the Parliament.

According to the energy ministry, the Lebanese pay around $700 million to EDL every year and $1.4 billion towards the private generation of electricity.  “If we don’t decrease the debts after reducing the cost of generation, we would go to $650 million in 2014 as direct losses to the treasury,” said Bassil. Both the finance minister and the International Monetary Fund have also stated that they support an increase in the price of electricity, although Bassil acknowledged the poor and the productive sectors will probably have to be compensated in some way. The energy minister also stated that renewable energy will make up 12 percent of the energy portfolio by 2020, a target first announced by the prime minister at the 2009 United Nations Climate Change Conference in Copenhagen. He added that the high possibility of finding gas offshore was a major factor in deciding to transition to more natural gas production in the plan. A law to regulate the exploration of gas in the country was before the Council of Ministers as Executive went to press.

Broadband: almost there…

Lebanon’s telecom sector is set to receive a boost from the government’s broadband infrastructure project, the first phase of which Minister of Telecoms Charbel Nahas announced on June 15 will cost $66 million. A spokesman for the ministry confirmed, on June 22, that a request for proposals would be issued in a matter of days . In January the Minister estimated that the much-anticipated project would total $166 million, then revised that figure down to $92.9 million in April. In March, Executive cited telecommunications experts at the International Telecommunications Union, the United Nations agency for telecommunications, as stating that the project should cost no more than $40 million. Anders Lindblad, president of Ericsson in the Middle East, confirmed that the project would constitute the “highways” or the national fiber-optic backbone, but did not include the access layer — the final crucial link between telecommunications infrastructure and the user which is still being studied by the ministry. 

“This part [highways], I assume will be public sector and I think that is a sound decision because there is a lot of money going into [it],” added Lindblad.  Nahas estimated that the project would need another 12 months to be completed and stated that in the 2011 budget “there will be a displacement of the tax burden on the telecom price structure,” adding that $800 million of the approximately $1.2 billion transferred to the treasury from the telecom sector last year was in the form of taxes; in a $160 million accounting discrepancy, the finance ministry stated that the total transfer from telecoms was $1.36 billion.

Lebanon praised and chided

The International Monetary Fund has concluded their annual consultation mission with Lebanese policy makers, including the Minister of Finance Raya el- Hassan, Central Bank Governor Riad Salameh, President of the finance commission  Ibrahim Kanaan and others.  “If the trend continues, [real] growth could reach 8 percent or even a bit more,” said Andreas Bauer, mission chief for Lebanon at a press conference alongside Hassan and Salameh.  “We have to caution that despite the progress made the vulnerabilities in Lebanon are still very high,” added Bauer. “There has been little progress on the structural side to address some of the bottlenecks and to strengthen the economic institutions in Lebanon.” The mission identified two main challenges for the country: to manage the strong economy with caution to make sure potential risks such as high inflation do not materialize, and to implement long delayed reforms to ensure the sustainability of the current economic growth. 

The IMF later issued further recommendations that advised Banque du Liban (BDL), Lebanon’s central bank, to privatize its non-financial assets, including Middle Eastern Airlines and its real estate portfolio, to improve its financial balance. Bauer also cautioned that the rise in real estate prices, the sector’s expansion and the amount of credit allocated to it should be watched “carefully.”  Using the finance ministry’s latest gross domestic product estimate (year-end 2009) and the BDL’s latest available figures on loans to the sector (February 2010), total credit extended to real estate in Lebanon is equivalent to some 33 percent of the economy. Speaking with Executive recently, Central Bank Governor Riad Salameh revised upward his previous estimate, from May, that real estate constituted 18 percent of total loans in the country.  “It might be one third, in fact, of the loan portfolio but it does not represent more than 10 percent of the total balance sheet of the banks,” he said. “Therefore, [with] the liquidity being very high in the banking sector, you do not have a situation of leveraging and the risk of bubbles.”

July 11, 2010 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 413
  • 414
  • 415
  • 416
  • 417
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE