• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Money Matters

Global research Highlights

by Bruce Steinberg September 5, 2000
written by Bruce Steinberg

• Productivity is the key to the outstanding performance of the US

economy. As a result of the tremendous revival in productivity in

recent years, inflation has remained dormant and corporate earnings

have advanced at a double-digit pace. Even now, as economic

growth has begun to moderate, productivity gains remain strong.

If they stay that way, inflation will probably continue to be

absent and earnings gains will be reasonable.

• The traditional definition of productivity is output per hour

worked. Federal Reserve chairman Alan Greenspan has said that

he believes that the productivity pickup is permanent, not cyclical.

Productivity rose at a 5.3% rate in the second quarter,

stronger than our estimate and 5 .1 % above its year-earlier level.

• The only other periods during which productivity gains were

strong occurred in the early stages of economic recoveries, not ten

years into an expansion. Unlike the current performance, rapid

gains during earlier periods mainly reflected a cyclical pickup as

the economy revived after recession. Indeed, during the past five

years, productivity has risen at the fastest rate since the mid-1960s.

• An equally important point to note is that productivity gains have

finally become widespread throughout the economy. Manufacturing

productivity rose at a 5.1 % rate in the second quarter and

was up by 6.9% year-to-year. That means that productivity in the

broad service sector also rose at a rate of more than 5% in the second

quarter and at about the same pace during the past year. Until

recent years, service sector productivity had been virtually

unchanged for two decades.

• The technology boom has arguably been the single-mostimportant

cause of the productivity revival. Our work shows that

productivity gains lag tech spending by roughly two-and-a-half

years. Tech spending has risen at a 25% rate during the past two

years, suggesting that productivity gains will remain robust.

Moreover, new orders for tech equipment are currently 42%

above their year-ago level, indicating that tech spending itself

should remain strong.

• The growth in productivity is likely to slow somewhat as the

pace of economic activity moderates, but we think that it will

still be impressive. We expect productivity to rise at a pace of

about 3.5% or more during the second half of 2000, and at a rate

of 3% to 3.5% for 2001. If so, we think that inflation will not

be a problem and that earnings will hold up.

• Robust productivity gains keep unit labor costs in check. Unit

labor costs fell at a 0.1 % rate in the second quarter and were down 0.4% during the past year. Manufacturing unit labor

costs have declined by 1.9% during the past year and are at their

lowest level since 1988. We expect overall unit labor costs to be

unchanged for 2000 and to rise by only l % or so next year. Inflation

simply doesn’t occur under those conditions.

• That’s borne out by the latest inflation report. The headline July

PPI was unchanged, and the core figure was up by only 0.1 %.

The PPI for crude materials other than food and energy fell by

l.8% for July, indicating that commodity price pressures are

unwinding. The core crude PPI for July was up by 7.5% year-toyear

because of commodity-price increases in late 1999 and early

2000, but it is likely to go negative before the end of 2000.

• The direction of the core crude PPI is a leading indicator of

the direction of earnings momentum. That means that the

deceleration on industrial commodity prices points to a deceleration

in earnings momentum. We expect S&P 500 operating

EPS to be up by 16% for 2000 as a whol.e, but the rate of

increase will probably be in the low double-digit area by the

fourth quarter. Next year, earnings growth of about l0%

seems likely as long as productivity growth holds up.

• Despite the surge in productivity in recent years, there is reason

to believe that productivity gains remain understated. Recent

releases of government data have made it possible to look at productivity

on and industrywide basis from 1987 through 1998. Many

industries posted huge productivity gains during that period, but

some important ones showed little or no productivity growth.

• That doesn’t mean, however, that the “laggard” industries have

missed the productivity revolution; the fault may lie with the data.

It shows that from 1992 to 1998 productivity in the construction

industry fell at a 0.9% annual rate, but that construction spending

rose by 7 .3% a year. During the same period, productivity in the

trucking industry rose by only I% annually, despite the sector’s

heavy investments in satellite and freight-management technology.

While medical costs decelerated and life spans grew longer,

productivity in the health care industry declined at a 0.6% rate.

• As we see, more reasonable assessments would raise productivity

growth for a numberofindustries, which, in tum, would boost the

productivity gain for the economy as a whole. Our best guess is

that overall productivity growth is still being underestimated by

a full percentage point. That’s another way of saying that economic

growth has been underestimated by a percentage point.

Bruce Steinberg, chief economist
September 5, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

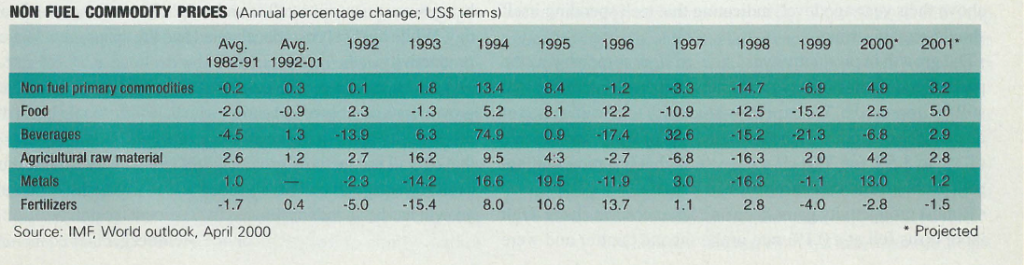
Non-oil commodity prices on the rise

by Executive Editors September 5, 2000
written by Executive Editors

W orld commodity prices

have strengthened signifi-

– candy since mid-1999, as

evidenced by the 25% rise in the IMF

index of primary commodity prices in

the past 12 months. While much of the

credit for this recovery goes to the

upturn in oil prices, non-fuel commodities

have also shown strength this

year with the index of non-fuel commodity

prices rising by 5% over the

nine months to June this year.

However, non-energy prices have yet

to recover fully from their late 1990s

slump when they fell by as much as

25% over the period between the beginning

of 1997 to the middle of 1999. The

IMF non-fuel commodity price index fell

by 14.7% in 1998 alone. Prices are

expected to continue the recovery that

started in 1999, due to stronger economic

growth and reductions in excess

supply of certain commodities.

Cycles are the dominant feature of

movements in world non-oil commodity

prices, challenging policy makers in

many developing countries that depend on

primary commodity exports. This last

cyclical decline has been more severe

than the previous two declines in the

early and late 1980s due to the more pronounced

than usual concurrence of

strong supply and demand shocks. The

slowdown growth in global demand during

19’97 /98 coincided with continued

production increases. Most of the decline

in non-energy prices was due to the Asian

crisis and the recession in Japan, especially

as several of the Asian countries were a

major source of demand for primary

commodities prior to the crisis. At the

same time, production of many commodities

had continued to increase at a

rapid pace, owing to technological

advances that cut production costs. In the

case of metals and fertilizers, oversupply

by producers to make up for the reduction

in revenues maintained the downward

pressure on prices. For certain agricultural

commodities, prolonged periods of

favorable weather in the US and Europe

have resulted in particularly good harvests,

preventing major rises in price.

The recent pickup in non-fuel commodity

prices is due to a reversal of the

supply/demand factors that triggered

the decline. World economic growth is

expected to be around 4% in 2000,

higher than initially expected, and supporting

a recovery of commodity

prices. However, while non-fuel commodity

price indices appear to have bottomed

out last summer and raw material

prices are increasing as the world

economy revives, the recovery is likely

to be slow. Stocks for most commodities

are still relatively high, and new capacity

is coming on stream. This means

that it will probably take longer than

usual for the upturn in demand to translate

into a significant increase in prices.

According to the IMF, non-oil commodity

prices are projected to increase by

5% in 2000 and between 3% to 4% in

2001. One important distinction

between the recovery in oil prices and

non-oil commodities as a group is that the

upturn in oil prices, while supported by

the recovery in world demand for oil, was

mostly driven by significant supply cuts

by OPEC and other oil producing countries.

On the other hand, producer cartels

in other commodity markets have largely

failed and producers in these markets

are unable to follow OPEC’s example in

reducing excess supply. Ample capacity

exists in countries producing non-oil

commodities, be it metal, phosphate,

petrochemicals and potash. Production

volumes should continue to ·rise in the

remaining part of 2000 as a result of the

ambitious expansion programs introduced

prior to the Asian crisis and a general

upturn in demand.

For exporters of non-fuel commodities,

the net effects of this year’s projected

increase in price hinge on the specific

commodities they export. The prospects

for Arab countries that depend on

exports offertilizers, such as Jordan and

the Gulf states, remain subdued.

According to the IMF, fertilizer prices fell

by 4% last year and are expected to

decline further, albeit at a slower rate, this

year (2.8%) and in 2001 (1.5%).

However, the surge in oil prices and

stronger economic growth worldwide

may initiate an earlier recovery.

September 5, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

GDR commentary

by Executive Contributor September 3, 2000
written by Executive Contributor

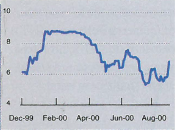
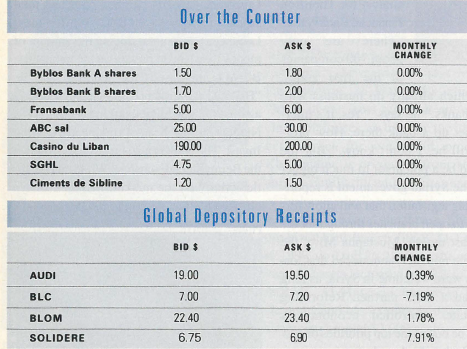
SOLIDERE

The general investor sentiment

toward the Lebanese GDRs

remains unchanged with local and

foreign investors waiting for the

upcoming elections for an efficient

macroeconomic policy. Solidere’s

GDR rose 15.28% to $6.225 (14/7)

as investors perhaps smelled a bargain,

only to fall back 3.61 % to $6

(21/7), then again drop 7 .5% to$ 5.55 as the economic condition worsened

with no signs of relief from the depressed real estate sector (28/7).

By early August, Solidere’s GDR edged up 0.9% to $5.6, as prince Al

Walid reconsidered plans to build a $250-million Four Seasons hotel,

as well as a residential apartment complex in downtown Beirut (4/8).

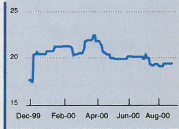
AUDI

Audi’s GDR was no different than

the rest of the GDRs or for that mat-

25

ter the economy in general with the

macroeconomic conditions still on 20

the downside and political instability

due to the elections putting the economy

on hold. Audi’s GDR was 15

priced at $19 .18 ( 14/7) and remained

there for a week (21/7).

By the end of July, news from the ministry of finance on the state of the

public deficit discouraged investors even more, driving Audi’s price

down 1.2% to $18.95 (28/7). Nevertheless, Audi regained some of its

losses as it was chosen as the best bank in Lebanon. It rose 1.58% to

$19.25 (4/8), and stayed at that level till mid-August (11/8)

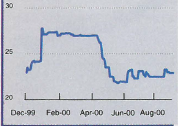
BLOM

BLOM’s GDR held firm this

month despite several negative

economic reports by S&P, EIU

(Economic Intelligence Unit) and

the ministry of finance, which

pushed most of the Lebanese

GDRs listed on the international

down as foreign investors

interest was slowly fading.

BLOM’s GDR remained at $22.5 for the second half of July

(14/7)(2117)(28/7), mirroring the stagnation of the local economy. It

then edged up 2.22% to $23 ( 4/8).

By mid-August, BLOM’s GDR lost $0.1 to $22.9 as investors cashed

in the gains (l 1/8)

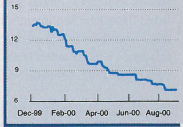
BLC

BLC’s GDR had the poorest perfor- 15

mance among all the GDRs losing

almost 7 .5% of its value in the past 12

four weeks. BLC’s GDR fell 0.32%

to $7.65 (14/7) as the economy 9

showed little growth and debt servicing

exceeding public revenues 6

for the first time, with the deficit

sp~nding ratio reaching 53% in the

first half of the year. Investors’ fear from a possible S&P downgrade was

revived, sending BLC’s GDR down 0.65% to $7.6 (28/7). A report from

the Economic Intelligence Unit (EIU), warning about the deteriorating

economic conditions pushed all the GDRs down; BLC dropped 6.58% to

$7.1 (4/8) and remained there (11/8).

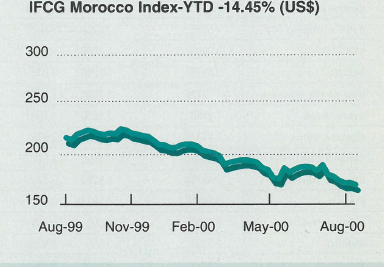
MOROCCO

Moroccan equities conti1’°ed to head south, breaking the

~ey 700-point psychological level as weak macroeconomic

performance and lack of foreign funds continued

to weigh negatively on sentiment. The highlight of the

month was the listing of mining company Managem,

which managed to add some interest to an otherwise quiet

market. Managem stole the limelight, outperforming its

parent holding ONA Group, and accounting for a big

chunk of trading activity.

EGYPT

The Cairo Stock Exchange continued to lose ground, suffering

another month of severe losses with institutional

investors remaining mostly on the sidelines. The lack of positive

economic news and continuous pressure on the pound

has caused the market to decline almost 40% so far this year.

Trading activity was mostly concentrated in the telecom sector

with the successful closing of Orascom Telecom’ s ( OT)

IPO, which was 1.7 times oversubscribed. OT’s attractive

pricing (EP55.568) prompted many investors to sell stakes

in MobiNil (-3%) and invest instead in the new issue.

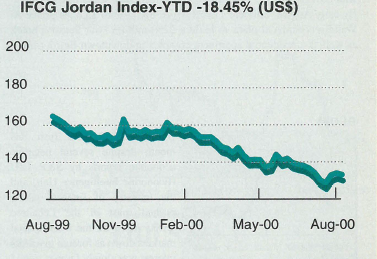
JORDAN

Investors at the Amman Stock Exchange welcomed the

modest rebound in share prices at the end of July following

weeks of consecutive declines. The small upturn was

primarily driven by an impressive rise in the Arab Bank

shares. However, mixed semi-annual results for most

listed firms kept sentiment subdued with the index hovering

around the 140-point psychological level. Mixed performance

was recorded in the insurance, industrial and

banking sectors, while the services sector lost ground

September 3, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Swallowed up

by Executive Editors September 3, 2000
written by Executive Editors

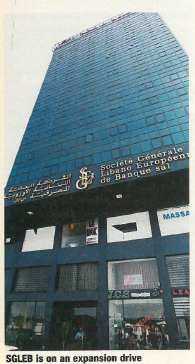
S ociete Generate Libano-Europeenne

de Banque (SGLEB) has reportedly

acquired the financially troubled lnaash

Bank in a deal worth $50 million. The

Central Bank had recently taken control of

lnaash after the J affal family relinquished its

84% stake. The bank had allegedly been in

violation of certain lending regulations.

SGLEB, which is half-owned by France’s

Societe Generale, will add 17 branches to its

30-branch network, vastly expanding the

reach of the financial institution and giving

it a presence in the South and Beirut’s

southern suburbs. “They were restricted in

opening new branches so they bought

lnaash,” says one banking analyst. SGLEB

is in an expansion mode. The bank has

moved into the Jordanian market and, a

couple of months ago, it purchased a

majority share of the local brokerage firm

Fidus. SGLEB registered profits of $18

million last year. lnaash had a capital of $10

million, assets worth $356 million and

$290 million in customer deposits in 1999

Safe bet

A rab Bank is planning a regular issue of

Investment Linked Deposits (ILD),

which will be offered with a choice of

indices. The US dollar-based deposits

guarantee that investors will not lose their

capital. The ILDs also, to some extent,

guarantee a certain return on an investor’s

money. The issue of the ILDs follows the

success of an earlier issue by Arab Bank. It

is linked to one or a basket of major

indices. These include the Nikkei 225,

Standard & Poor’s 500, Hang Seng or the

DJ Eurostoxx 50. “Instead of a fixed interest

rate, you get a return based on the

increase in the indices,” says Rim Zanabili,

senior relationship manager at Arab Bank.

“Once a new ILD is opened, clients have

four to six weeks to invest.” The minimum

deposit is $20,000.

Fast mover

A 1-Mawarid has become the first

Lebanese bank since the Israeli

withdrawal to open a branch in the former

occupied zone. The new branch is located

in Hasbaya. It has six employees and

serves a population of around 50,000 people,

including those living in outlying

.1 areas and villages. Only Fransabank –

which has been operating branches in

Marjayoun, Bint Jbeil and Jezzine since the

early ’90s – has had a presence in the

zone. “The next closest bank is at least a

half-hour’s drive away,” says Marwan

Kheireddine, AI-Mawarid’s chairman.

“Most of the local residents are middleclass

employees, so they are the ideal target

market for our retail products.”

Kheireddine is originally from Hasbaya

and his familiarity with the area and many

of the locals who live there helps assure that

he will have a loyal clienl base. The medium-

sized bank had profits of $1.1 million

in 1999, up a full 26.9% from the previous

year. Its assets increased by 32% to $30.19

million. Al-Mawarid has over 40,000

accounts and has extended 17,000 loans, averaging around $2,000 each.

Current accounts

Allied Business Bank (ABB) and

Societe Nationale d’ Assurance (SNA)

have launched a new set of bancassurance

products called H.imaya. The policies were

developed by SNA and will be marketed

exclusively by ABB to its clients. These

include savings-with-insurance plans for

education and retirement benefits as well

some traditional policies. ”We have to keep up

with the worldwide trend that makes it possible

for clients to handle all of their financial

transactions – namely banking, investment

and insurance – at one location, a sort of

financial supermarket,” says Nada Assaf,

ABB’s manager of research and development.

A number of banks in Lebanon have

either started theirown insurance company or

have bought majority shares in established

firms. Banque du Li ban et d’ Outre Mer is one

of Arope’s major shareholders and Byblos

Bank owns ADIR (see pp. 32).

The casino cashes in

Casino du Liban (CCL) saw profits

jump to $5.2 million in the first half of

2000, a 60% increase over the same period

last year. Profits were just $3.6 million in the

first half of 1999. Revenues for the first half

of 2000 totaled $42 million. The casino

saved some $5.4 million by renegotiating

contracts. It is also trying to change the contract

with Abela Development and Tourism

Company and the London Clubs responsible

for running the gaming facilities. But the

casino is not as lucky as it may seem. The

company owes the London Clubs some $5

million and the ministry of finance is

demanding that the casino pay $23 million

in back taxes from slot machine revenues, a

case that is now before the Shura council.

The new Audi

convertible

B anque Audi has launched a new threeyear

convertible bond linked to the

bank’s global depository receipts (GDRs)

and carrying a fixed rate of return. The bonds

are being marketed towards Audi’s retail

depositors. The minimum investment is

$1,000. The paper will offer investors a return

of6%, 7% or8% and are priced at$23.81, $25

and $27.03. Interest is paid semi-annually.

The GDRs’ issue price in 1997 was $27!. This

·marks the second issuance of convertible

bonds in post-war Lebanon. The first ones

were issued by Ciments de Sibline in 1996.

Retail depositors at Audi’s 61 branches will

have the right to exchange the bonds any time

during the paper’s lifetime. Over $75 million

in bonds will be issued. The first tranche, to be

sold in August, is not expected to exceed $30

million. ‘The timing is right because analysts

consider the bank’s GDRs undervalued,” says

Nabil Chaya, head of capital markets at Audi.

Rolling downhill

1999 suffered a drop of 17%. Until the end of

June this year, sales fell 28% compared to the

same period last year. Rymco’s shares,

which are traded on the Beirut Stock

Exchange, have been stagnant, just like the

rest of the stock market. They have

remained at or below $2.50 since the beginning

of the year.

Babv steps

S yria has taken the first steps toward

opening up its state controlled banking

system by granting three Lebanese

banks permission to open branches in the

country’s free trade zones. Societe

Generale Libano-Europeenne de Bank,

Fransabank and Banque Europeenne pour le

Moyen-Orient are allowed to provide banking

services to Syrian companies operating

within the free zones,

provided that each

bank maintains a

minimum currency

capital of $11 million.

But the move is

not likely to result in

any major financial

windfall for the

banks that open in

the zones, says

Maurice Iskander, an

analyst for Thomson

Financial BankWatch.

“There are only

about 700 companies

in the free zones,

most of which already do business with

Lebanese banks,” he says. “Yes, it’s interesting

to set up a bank there. How profitable

it will be, I don ‘t know.” But the

move could be a precursor to much bigger

reforms. The Syrian government is reportedly

studying legislation that will allow foreign

banks to open branches throughout the

country. Last month, Mustapha Miro, the

Syrian prime minister, announced that foreign

banks were welcome in Syria, as long

as they had a local partner. Reforming

Syria’s state controlled economy is

believed to be one of the top priorities of new

president Bashar Al-Assad.

Trade aid

The Arab Trade Finance Program (ATFP)

has extended to Byblos Bank and Credit

Libanais lines of credit worth $20 million

and $10 million respectively, to facilitate

trade transactions with Arab countries. ATFP

had previously granted the Lebanese government

a $40 mill ion loan for the same purpose.

The ATFP has so far granted several

Lebanese financial institutions a total of 37

lines of credit, worth some $251 million. The

Credit Libanais program includes deals to

import crude oi l, which could prove fruitful

should work resume on the refineries. “Loans

wilJ be given at Libor for six months and at

Libor plus 1/8 for one year. But the bank will

add a risk factor of 1 % to 2%, depending on

the project and the client,” says Georges

Khoury, assistant general manager of Credit

Libanais Investment Bank.

Bucking the trend

At a time when most banks are struggling

to maintain profit, Banque

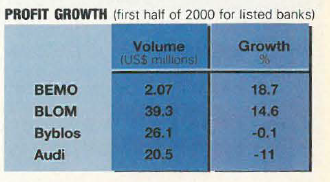
Europeenne pour le Moyen-Orient (BEMO)

has been seeing some healthy earnings.

Profits for the sector dropped 13% in 1999,

but BEMO’s earnings shot up to $2.07 for the

first half of 2000, a full 18.7% increase

compared to the same period last year.

Customer deposits climbed 35% and total

assets increased 28.8%. While most

Lebanese banks are reducing the amount of

money they lend to private sector companies,

BEMO increased its lending 31 .4%.

“BEMO’s performance is obviously working

against the tide in the banking sector,” says

Nicolas Sawan, head of trading at Lebanon

Invest. The bank is also bucking the trend at

the Beirut Stock Exchange. While there is little

activity on the market, BEMO’s shares

climbed 8% last month, to $3.25.

September 3, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

come together

by Avo Tavoukdjian September 3, 2000
written by Avo Tavoukdjian

Y ou don’t have to pick up a copy of

the National Enquirer to know

that insurance firms are going to

bed with banks these days. The megamerger

of Citicorp and Travelers Insurance

Group created the $700 billion giant

Citigroup almost two years ago, and

helped precipitate the blurring of lines in the

US financial sector – a trend that was

already well established in Europe.

France-based insurer Axa, for example,

has an asset management portfolio of $700

billion, making it the fourth-largest money manager after Union Bank of Switzerland,

Fidelity and Credit Suisse.

Here in Lebanon, the business of banks and

insurance companies is also coming closer

together, albeit on a smaller scale. “It’s the

future. People are looking for a one-stop

shop, and banks are creating a sort of financial

supermarket,” says William Salem,

head of marketing for SNA, the first insurance

firm to start selling insurance in banks.

SNA has created a worldwide group accident

policy, which it sells to banks, and has

developed a complete line of retail insurance

products that are sold at Banque Audi and

BBAC, both shareholders in SNA.

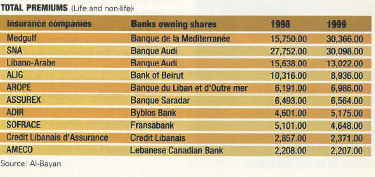
At least ten banks have started their own

insurance companies while others are buying

into existing insurers. Banque du Liban

et d’Outre Mer is a major shareholder in

Arope; Byblos Bank owns all of ADIR;

Banque Audi has a I 0% stake in Societe

Nationale d’ Assurance (SNA) and is finalizing

its recent acquisition ofLibanoArabe.

So what do these profit-driven partners get

out of this love affair? Insurers are the first to

benefit. Banks throw a constant stream of

business their way. Insurance companies

that are owned by banks are guaranteed captive

business. Before granting a loan, a bank

usually requires a client to purchase one or

more policies. These policies virtually

ensure that a bank will get back its money. A

personal loan is accompanied by life or disability

insurance. Car loans must come with

automobile insurance. A housing loan generally

comes with life insurance as well as fire

or natural disaster policies. “This is our

bread and butter,” says Fateh Bekdache,

general manager of Arope insurance.

“Everyday the bank’s branches are open, I’m getting cash business,” he adds. In 1999,

at least a third of Arope’s $5.5 million portfolio

was captive business, policies that

BLOM clients were required to buy.

Most of the insurance pobcies that are

sold through banks, such as life, fire and

marine, are the most profitable forms of

coverage. At least half of ADIR’s $5.2 million

portfolio in 1999 was in life, and the

firm’s earnings were $1.6 million.

Insurance companies that rely on banks for

business are also able to lessen their

reliance on the volatile and high-risk market

for medical coverage. “We’re not interested

in hospitalization,” says Jean Hleiss, general

manager of ADIR. “Others are building

their market share on [hospitalization] and

that’s why they are losing.” But medical

policies account for 33% of Arope’s business.

Although a third of that is BLOM’s medical group, the insurer’s heavy reliance

on health coverage has taken its toll on

profits. Out of $5.5 million in revenues in

1999, earnings were less than $475,000.

Insurers receiving captive business from

banks do away with long collection periods

and receivables. Collection problems have

contributed to the collapse of more than one

insurance firm. With banks, all payments are

made in cash. The insurer has no receivables.

At least 80% of ADIR’s portfolio comes

from Byblos Bank, which pays upfront.

“When BLOM issues a loan, they take the

money for the insurance from the customer

and give it to me,” says Bekdache. “We get

paid ahead and the balance is always zero.”

And by relying on a bank for business,

there are no broker’s charges. ”The commission

rates in our business are very high,”

says Bekdache. “I don’t have to pay that for

business coming from the bank.” Many brokers

are not reliable payers. They tend to

demand extended payment terms for clients

and, says Joseph Issa, lawyer for Middle

East Assurance and Reinsurance Company,

“some brokers don’t pass on everything

they collect from the clients. They pay the

money they’ve collected in parts even

though the client has paid up.” At the same

time, brokers often transfer portfolios from

one company to another every time they

find a better deal. “If you depend on a broker

who has a very large portfolio and he

decides to leave, you have a problem,” says

Bekdache. Arope has already reduced its

broker-based business from 33% of its total

sales to less than 20%.

The banks also benefit from the relationship

by getting a share in the profits. Byblos

Bank is entitled to the $1.6 million in earnings

made by ADIR. BLOM gets 90% of Arope’s profits. “We look at it as an investment,

a diversification of the bank’s products,

which leads to additional profits,”

says Faisal Nsouli, head of research and

development at Byblos Bank. “We rely

heavily on life and homeowner policies.

Having a bank-owned insurance company is

more efficient and more reliable.” At the

same time, banks are able to tailor insurance

products for their clients. A fi vi::-year pt::rsonal

loan can be guaranteed by a life insurance

policy for the same period.

But there are downsides to the bank-insurance

company connection. An insurer that

depends solely on a bank to provide it with

business is restricting its own growth. And in

the insurance business, as your portfolio

grows, your risk diminishes. “It’s not healthy

to depend on the bank all the time,” says

Bekdache. “Direct business will generate

more for you.” About a third of Arope’s total

revenues, or $1.8 million, came from direct

sales in 1999. ADIR is also considering stepping

out of Byblos Bank’s shadow and

expanding into direct sales. “We are seeking

to increase our market share as well as

exploring new markets,” says Hleiss.

There are those who believe that this type of

marriage between banks and insurers denies

consumers the basic right to choose to do

business with another insurance company.

”Banks are actually pushing clients to buy

insurance from companies, which are either

theirs, or with which they have made

arrangements,” says Abraham Matossian,

chairman of Al-Mashrek. “It’s a package deal

and the client cannot refuse. Bancassurance is

important abroad, but the client is not obliged

to accept what the bank offers. He can either

accept what’s offered or go with another

insurer. Here there is no choice.”

September 3, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Vulnerable

by Peter willems September 3, 2000
written by Peter willems

T he rating agency just won’t quit. Two

months ago Standard & Poor’s

(S&P) threatened that if the government

didn’t do something about fiscal problems

running wild, Lebanon would be downgraded

later this year. S&P’s latest incoming

targeted the country’s most cherished sectorthe

banks. Rest assured: The recent warning

did not highlight problems within the banks.

Whether or not the government heeds S&P’s

earlier signal will determine to a great extent

the problems that banks may face.

The agency went after financial systems

around the world that are vulnerable or

already tasting deterioration of credit quality.

If, by chance, defaulting on loan payments

reaches critical mass, banks could experience

a credit bust. Out of 15 banking systems

cited by S&P, US banks’ credit exposure

could be hit if the booming economy comes

to an end with a hard landing. Japanese banks

cannot prosper as the country’s recovery

from its financial crisis a decade ago is moving

slowly. Lebanese banks, on the other hand, are operating

in a feeble

economy and if it’s

not resuscitated in the

near future, loan portfolios could be in jeopardy.

“Lebanon is a special case,” says

Navaid Farooq, S&P’s sovereign analyst for

the Middle East and North Africa. “It’s about

macroeconomic conditions. We’re not concerned

about the banks themselves as much as

the environment they operate in, which is

riskier due to the government’s severe fiscal

imbalances.”

Relying on a rescue team to pull the

economy out of its dismal state is in question.

The administration, in office for two

years, put together a fivt:-year plan that

included lowering the debt, correcting fiscal

imbalances and stimulating growth.

Instead, it let debt to GDP climb from

118% at the end of 1998 to 140%. In the first

half of 2000, the budget deficit reached

53%, way above this year’s target of

37.3%. Economist Intelligence Unit reports that GDP growth fell to – l % in

1999 and predicts only 0.5% this year.

Right now there is a glimmer of hope that the

elections will bring in a new government able

to repair the crippled market. But the next government

has little room to maneuver. After debt

servicing and salaries and wages, the government

can only play with about 15% of its

expenditures – something they can’t reduce

since it’s their meager contribution to growth.

Raising taxes again to increase revenue

would bury the economy even further.

Many analysts believe emergency action

must be taken. ”The most important thing is

for the government to get money today,”

says Marwan Barakat, head of research at

Banque Audi. “It must relieve debt and debt

servicing as soon as possible.” He suggests

selling mobile phone licenses – $2. 7 billion

was lost when the government rejected offers from LibanCell and Cellis – and

picking up the pace on privatization. But

once a new government settles in, it might

be too late to make an impact this year. And

some wonder whether any Lebanese

administration can unite and generate political

will to implement solution~ “I don’t pin

any hopes on anybody anymore,” say~ um: analyst.

“We have to be realistic:

All government

policies will be dictated

by political interests, not

political will.”

On the upside, unlike the

wayward government,

most banks have the discipline

to prepare for the

worst. “Most of the banks

are low on lending compared

to other countries,

which gives them a lot of fat,” says Andrew Stephens, head of retail at

Credit Libanais. “And most have significant

assets in Lebanese T-bills. The banks do not

face deep problems.” By the end of June, the

loan-to-deposit ratio for the sector was 42%.

And expecting hard times, banks have

become less generous handing out money.

Loan growth fell from 20.5% in 1998 to

12.7% last year. Lending up to the end of June

increased only 3.7%. The banks are also high

on liquidity: Liquid assets to total assets

stood at 68% in the first half of 2000.

Creating a cushion using conservative tactics

makes it unlikely for numerous banks to

fall if defaulting on loans accelerates. “The

banks will get into problems only if they stop

lending prudently and start lending outside

certain banking criteria, as a couple of them

have done,” says Stephens. One case was

Inaash Bank. Found with bad loans and

fishy lending in violation of regulations, the

central bank stepped in and sold it to Societe

Generale Libano-Europeenne de Banque.

If obituaries are rare, one area will be difficult

to defend: profits. “Not many banks will

fail in the near future,” says Bassam

Yammine, senior manager of corporate

finance at Lebanon Invest. “Banks have

enough ammunition, especially the large

ones, to continue. I’m worrying mostly about

the bottom line.” There have already been

attacks on banks’ earnings. Spreads have been pinched in recent years. With interest

rates on two-year government paper falling to

14%, stiff competition has kept deposit rates

up (around 12% on LBPdeposits). The economic

slowdown has put pressure on growth

in deposits and assets. An increase in deposits

fell from 20% in 1998 to 11 % last year. Nonperforming

loans are now starting to move up.

Doubtful loans to gross

loans inched up to 14%

last year from 13.75% in

1998. In June, they

climbed to 15.1 %.

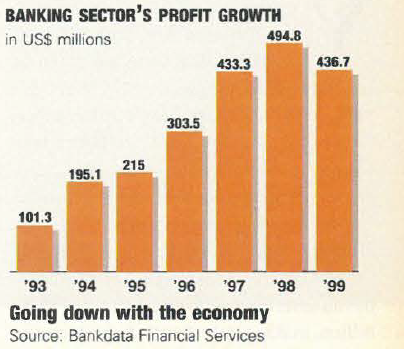
After profits dropped 13%

for the sector in 1999 – a

blow after 40% average

annual profit growth

between 1993 and 1998 -many predict that earnings

will experience a similar fall this year. “Now adding

deterioration of asset quality and an increase

in provisioning to revenue stagnation and

tight spreads, profits will drop between 15%

to 20% this year,” says Yanunine.

Finding solutions for the banks to generate

better earnings will not be easy. Banks are still

heavily investing on a safe bet: Thirty-five percent

of assets are in T-bills. But with the

spreads in a vice and the option of increasing

lending to the private sector with higher

yields a no-no for now, the banks are in a catch

22. “With the loan ratio this low, banks cannot

make up the thin spreads on lending,” says

Stephens. “That’s about it for the bottom

line.” Banks have been moving more into

retail banking to help beef up non-interest

income. “It’s important for the banks to move

into products and services as profitable activities,”

says Haroutiun Samuelian, vice governor

at the central bank. “In the early ’80s,

non-interest income for US banks took up

20% of their revenues. Now it’s a 50/50 split

between interest and non-interest income.” But

retail banking has yet to pay off. It requires

high volume, which is difficult in a small

market, while other non-interest tools, like letters

of credit, have been pulled down with the

recession, damaging gains coming from new

products and services to make a difference.

As in any sector, downtime means lowering

costs. “Banks must focus on restructuring,

cleaning up, cost cutting,” says Yammine.

Banque du Liban et d’Outre-Mer, Lebanon’s

largest bank and one that is still enjoying

healthy profit growth, is not only conservative

in lending but has focused on reducing

expenses. Its cost-to-income ratio dropped to

34.7% after the first six months this year

from 38.4% at the end of 1999. But other

majors more aggressive expanding on retail

find it more difficult to contain costs. Banque

Audi’s and Byblos Bank’s cost-to-income

ratios have moved up this year. ”The human

cost is already low compared to other countries.

Plus, many banks, out of necessity, are

investing in new services which all have

costs,” says Stephens.

If economic agony is prolonged, the pace of

mergers and acquisitions may pick up-especially

small and medium-sized banks swallowed

up by larger ones. Out of the 63 banks

operating in the country, the top 20 carry the

most muscle. Over 90% of total profits are in

the top tier, which leaves less room for the rest

of the banks’ earnings to fall. “With consolidation,

economies of scale can help,” says

Samuelian. ”The sound ones will survive

while the weak ones will not.”

Going abroad would help. But up to now

Lebanese banks have been hesitant to fan

out across the region. This could change.

Syria, with a state-owned, dilapidated banking

system, is opening up. It just established

free-trade zones and three Lebanese banks got

the green light. The problem is having to wait

for the entire Syrian market to open up.

“Syria is the place,” says Stephens, “but not

tomorrow. Maybe the day after tomorrow.”

What’s more certain is that if banks

remain mostly entrenched in the Lebanese

market and the economy continues to falter,

it may take time for them to see glory days

in profit growth again.

September 3, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Stuck in reverse

by Peter willems July 30, 2000
written by Peter willems

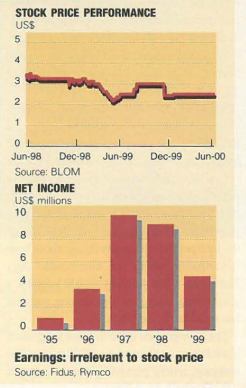
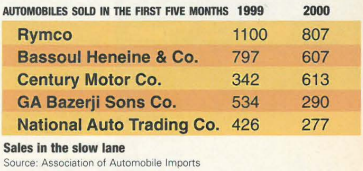
Rasamny-Younis Motor Company
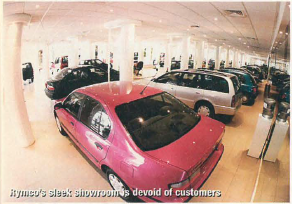
(Rymco) is still holding on to the
number one position in car sales in
the local market with a 14.4% share so far
this year. That’s good news for the only car
dealer that has shares traded on the Beirut
Stock Exchange (BSE). Unfortunately, the
rest of the news is not so bright. Recently
Rymco released its 1999 figures: Sales
dropped 30% and earnings fell 49%, from
$9.3 million in 1998 to $4.7 million. In the
first five months this year, units sold
decreased to 807 from 1,100 in the same
period the year before.

What is hurting Lebanon’s leading car
dealer? First and foremost, the economic
slowdown has caught up with the car market.
While economic growth started to drift
lower in 1996, car sales remained robust
through 1998, climbing 26%. “Car sales in
a normal market would have gone down
earlier,” says Gerard Rizk, senior analyst at
Banque d’Affaires du Liban et d’Outre-Mer.
“The car market was underdeveloped
in methods of financing. Two years ago
credit facilities were offered by banks and
consumers took advantage of that.”

But with the economy now at a standstill,
access to car loans can no longer encourage
customers to buy. “People are holding on to
their money to see what will happen. They
are waiting,” says Rania Fathallah, senior
associate at Middle East Capital Group
(MECG). “Someone buying a car today is
a person who needs a car, the old one is
falling apart and needs to be replaced.
Those with reliable cars will not buy now.”

Lebanon’s recession finally put a stranglehold
on the dealers last year. In 1999 total
car sales dropped about 17%, and so far this
year sales have fallen 21%, according to the
Association of Automobile Imports. Among the top car dealers, the crunch is
becoming obvious. Rymco’s main power
drive in sales comes from its Japanese
import, Nissan (93% of its units sold this
year), with Sunny being its leader in passenger
cars and Pathfinder its 4×4. G.A.
Bazerji & Sons, selling a full range of
Suzukis, has been ripping through the
Lebanese market in the last few years. Its
4×4 Grand Vitara has been its best seller. A
small to medium sized off-road vehicle
compared to the large Pathfinder has a
much cheaper price tag: Grand Vitara is selling
fully loaded for $14,900 to $15,900,
while the Pathfinder stripped down with no
extras goes for $28,250 to $30,500.

Bazerji’s Baleno, its best-selling passenger
car, sells at $7,900, while Rymco’s Sunny
is priced at $13,950 to $19,750. Bazerji’s
sales growth nearly tripled between 1997
and 1999 and moved up in ranking from 15 in 1997 into the top five in sales last year.
But this year, Bazerji’s momentum has hit
a brick wall: sales have dropped 46%.

Bassoul Heneine & Co., selling leading
European brands like BMW and Renault,
was able to move up from the third position
to the number two slot in sales in 1999. But
that wasn’t the result of increasing sales.
Cars rolling off the lot dipped slightly,
propped up by a weak euro that has
brought Heneine’s prices down with it.
Instead, the company that was right behind
Rymco, Century Motor, has had problems
selling its Korean brand, Hyundai. Century
Motor came out with a bang
bringing Hyundais to the market
in 1994: In 1996 the dealer led
the market in sales. But since
then, sales have deteriorated
dramatically. Sales in 1996 hit
3,372 last year units sold totaled
only 1,490. According to
Fathallah, consumer interest in
Hyundais worldwide has fizzled
out in recent years, partly as a
result of their quicker depreciation
and less reliability in the eyes of
the consumer.

Heneine has something new that
might help sales. For the first
time it will carry 4x4s, both
from BMW, for $56,000 and up,
and Renault, fully loaded and
similar in size to the Grand
Vitara at $22,000. “Four-by-fours
are very important,” says
Pierre Heneine, Bassoul
Heneine’s general manager for
financial activities. “Four-by-fours
take up at least 25% of the
market, and we have been out of
that part of the market completely.” He predicts that 4x4s will push up
sales this year by 5% to 10%. “We hope to
be number one in sales by the end of the
year, if not in 2001,” says Heneine. That’s
a decent goal, but the new 4x4s will have to
take up the slack. So far this year, Bassoul
Heneine has seen its sales drop by 24%.

Rymco has taken steps to help handle the
harsh economic conditions. “We reduced our
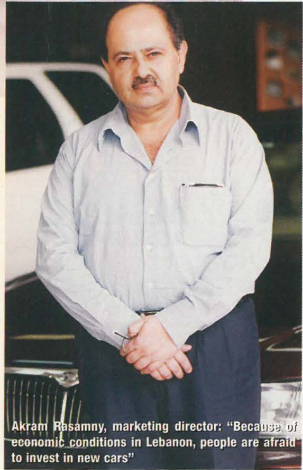
costs in many areas,” says Akram Rasamny,
Rymco’s marketing director. Total operating
expenses dropped 16% in 1999, including a
decline in salaries and wages. Rymco has
also focused energy on diversifying products
and services. Last year it moved into the
boat market. “We plan to be very active in the
marine department,” says Rasamny.

The company has gone outside of retailing
by investing in Capital Finance Corporation
(CFC), which is waiting for approval by the
central bank. The financial institution, with
a total of $30 million including partners
such as Credit Libanais, MECG, Century
Motor and Standard Motors, is geared
towards offering consumer loans in
Lebanon and the region. In 1998 Rymco opened its “megastore” to push sales in used
cars. But in 1999 used cars only took up 7%
of net income. It also had plans to start a car
rental agency and to team up with an insurance
agency to cover automobiles. But
these have been put on hold.

With the economy in a black hole and the
BSE in paralysis, it’s difficult to get investors
interested in any listed company except
Solidere (see box). Rymco’s share prices
rarely move up or down, regardless of its
performance (see graph). It remains consistent
with its dividend payout, even though earnings
have decreased, a 53% dividend payment
ratio in 1999 compared to 54% in 1998, coming
out as $0.1 per share off of last year’s profits. Its P/E ratio is
within a reasonable
level, around 13 for
1999 earnings.

But until the BSE
is reactivated
Rymco’s shares will
get little attention.
And with the car market now caught on
the negative side of the economic
cycle, things don’t look good. “This could
be the worst year for car sales to decline
since the war, unless there’s a major
improvement in the economy,” says
Fathallah. But an upturn doesn’t look
likely in the short term. “If the private
sector, the main drive of the Lebanese
economy, suffers one more year, Lebanon
could go bankrupt,” says Nabil Bazerji,
G.A. Bazerji & Sons managing director. “If
it is not relieved by important changes, don’t
expect better income among businesses in
Lebanon.” This is something Rymco will
have to worry about, this year and probably
the next.

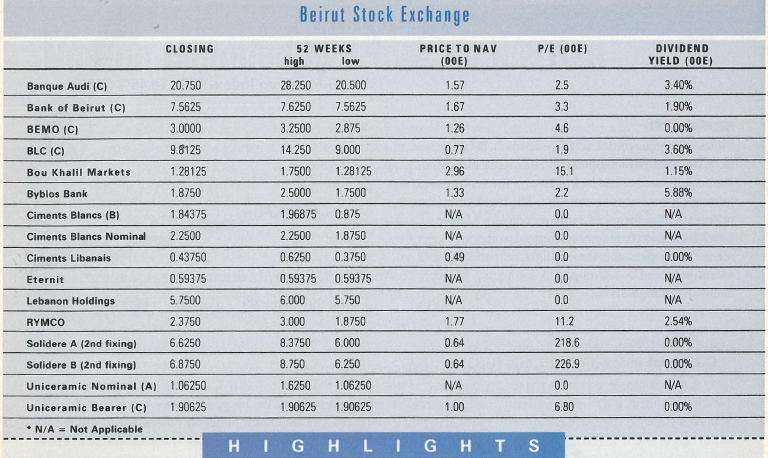
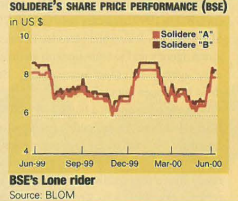
The one and only stock

With the Beirut Stock Exchange
(BSE) still in intensive care, there’s
only one stock that is able to move.
Solidere, which at $1.32 billion accounts
for 73% of the BSE’s market cap, was the
only company that showed a significant
jump after the Israeli pullout. In a few
weeks, Solidere’s shares on the BSE
jumped over 20%, while its GDR shares
increased over 10%. The two banks that
get most attention, Banque du Liban et
d’Outre-Mer (BLOM) and Banque Audi,
were lagging. BLOM’s GDRs went up
around 5%, while Audi’s GDRs barely
moved. Audi’s shares on the BSE, which
started the year at $28.13, continued to
fall, dropping 19% since the pullout, to
end up at $20.75.

In 1999 Solidere had a dismal year.
Sales plummeted and profits crashed
93%, from $54.2 million in 1998 to $3.7
million. The general consensus among
analysts is that if there is a peace
agreement coupled with an economic
recovery, Solidere’s growth will be re-
energized. But it’s hard to predict when
that could happen. HSBC and Middle
East Capital Group’s recent reports
offer a “hold” recommendation for the
long haul. But Société Générale just
released its analysis and suggested a
long-term buy. According to Hani
Shammah, senior regional analyst at
Société Générale, the prospects for a
comprehensive peace agreement are
improving and the Lebanese government
is looking more sympathetic
towards the real estate giant.

“Compared to 1999, it doesn’t take
much for the future of Solidere to look
brighter,” says Shammah.

But still, the government needs to be a
friend to Solidere (see “Can’t get no sat-
isfaction,” May 2000). Permits are still
trickling through: When Executive went to
print, there were 24 construction per-
mits and 29 occupancy permits pending.
The souqs are a prime area that will help
Solidere move forward. A decree that
gives a green light to the souqs has been
sitting with the council of ministers for
three months. If there is a historical
breakthrough for peace in the region,
everyone knows that players in the mar-
kets can make a quick buck as
Solidere’s share prices will soar. But it’s up
to the government to let Lebanon’s
biggest business operate as it should in
order to grow in the future.

July 30, 2000 0 comments
0 FacebookTwitterPinterestEmail
Cover story

Bring in the new economy

by Carl Gebeily July 29, 2000
written by Carl Gebeily

According to latest estimates, there are
about 240 million people worldwide
with access to 1.5 billion Web
pages on the Internet. Most of the users are in
North America and Europe, while the Middle
East, some areas of the Far East and Africa
bring up the rear with the least access to the Web.

Michel Kilsy, managing director and chief
IT consultant of Internet Facilities, notes that
the world is facing two basic truths: “First, the
Internet is truly a global phenomenon and, second,
that phenomenon has hardly touched
our region.” The Middle East in general
needs to look to other models to increase
Internet penetration and connectivity, including
higher bandwidth and embracing wireless
communications brought in by outside
investors. “All around us, in ways and forms
that we have been too sluggish to fully appreciate,
new digitally based economic arrangements
are changing how people work together
and alone; how they communicate and
relate; how they consume and relax.”

Some IT analysts, such as Dialog’s
Jacques Hakimian, are more upbeat about
this country’s e-prospects and estimate that
Internet data traffic between Lebanon and the
rest of the world, already among the highest
in the region, may soon have annual growth
rates in excess of 100% and continue such
growth rates for years to come. “The rise of
the Internet changes many things about how
‘information works’ are distributed,” says
Hakimian. “The Internet should become a
great economic engine for Lebanon, just as it
has become for the USA.”

The case in point is the unheralded growth
in the business-to-consumer (B2C) market. For
instance, where previously there were not enough
artists in
any one place
for the record
stores to carry their
music, now, via the Internet
and the plethora of music sites, artists
can reach audiences anywhere.

The two facets of the digital economy,
ecommerce and the information revolution
that is the driving force behind ecommerce,
are growing and changing at breathtaking
speed. “The ecommerce wave is having
a major impact on the world economy,
thereby fundamentally altering the way we
produce, consume and communicate, and
that is why Lebanon must use its collective
will to embrace and keep abreast of the
new technology,” says Hakimian.

Research shows that the Lebanese
Internet industry, estimated at $20 million
in 1999, could exceed $50 million by
2003 with the expected 140% rise in users.
“We are currently at 85,000 users,” says
Hakimian. “Our potential is of the order of
400,000. And that increase will drive commerce
on the Internet.”

But while the benefits that can arise from full
participation in the information economy are not
limited to the world’s developed nations, for
much of the world, ecommerce and the
movement to a digital economy in general are
constrained by a lack of critical infrastructure.
Hakimian believes that, ultimately, any success
in Lebanese ecommerce will largely
depend on an effective partnership between the
private and public sectors, with the private sector
in the lead.

Furthermore, economies, whether virtual
or traditional brick and mortar, have also
always been a function of geopolitical variables.
And across the region, there is hope that
the new crop of leaders, from Jordan’s King
Abdullah to Morocco’s King Mohammed to
Syria’s Bashar Assad, will bring social,
political and economic change. A new cadre
of young, western-educated Arab leaders
whose focus on economic and democratic
reforms could mark a historic departure from
the ideological leadership of their fathers and
usher in a new era in the Middle East.

As patron of the Syrian Computer
Society, Bashar Assad has worked to
spread computer use in his country. He
wants to move Syria from a Middle East
backwater, where Internet access is available
only to the elite and cell phones operate
in only a few urban centers, to the fast
lane of the information highway.

“The economy is the most important thing
on his agenda,” says Riad Abbas, professor
of light electronics and IT systems at the
University of Damascus. “To him, the
Internet is not so much a value in and of itself,
but rather that computerization is the basis for
economic progress.” Syria, notes Abbas,
will now be looking at ways to make the transition
from an agricultural economy to an
economy based on high-tech.

Certainly compared to Syria, Lebanon with
its cheaper connection fees and “Internet for
all” philosophy represents something of a
cyber heaven. But in relation to the West’s
sophisticated B2B Net-tools and its embrace
of e-consumerism, Lebanon is still the poorhouse
in the global village. In this era of
change, time and regional stability will tell if
Lebanon can rise from virtual purgatory.

July 29, 2000 0 comments
0 FacebookTwitterPinterestEmail
Cover story

Land of plenty?

by Gareth Smith July 21, 2000
written by Gareth Smith

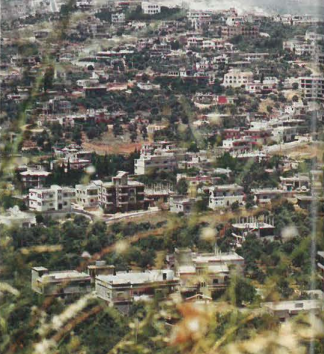
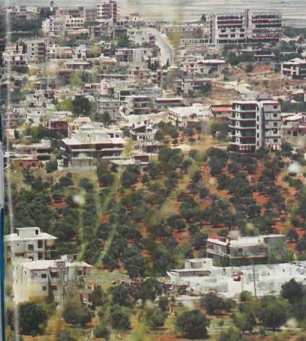
Liberated south Lebanon is slipping
back into rural tranquility. The purple-
topped tobacco plants sway in
the breeze, children play on abandoned
tanks and old men chew the fat under
posters of Hassan Nasrallah. The unspoiled
hills and coast astound visitors.
The quiet is broken only by the sounds of
reconstruction. Bulldozers, sporting the
colorful emblem of the Council of the
South, are out repairing roads and installing
pipes workmen are putting up electricity
poles. New palaces are under construction
others, left half-built during the years of
fighting, are finally being finished.

So will tourism and new housing drive up
land prices? Yes, say many. Expectation of
a real estate boom came almost immediately
after the Israeli withdrawal on May
24. Take Imad Saab, chairman of the
Lebanese Projects Establishment, based
in Kuwait, who told the Kuwait News
Agency: “I know a Kuwaiti businessman
who bought 120,000m² of land for only $2
per m² in the region of Iqlim Al-Toffah five months ago. Now the price per m² in this
region has soared to at least $15 per m².”

But how much of this is hype? Raja
Makarem, of consultants Ramco, is among
the skeptics: “This is daydreaming. Unless
people were selling under the value earlier,
nothing rises from $2 to $15 in five
months.” Ibrahim Murtada, a developer in
Tyre, is also unconvinced: “Some people are
spreading rumors that land is being bought
at $350 per m², but these are all lies.”

Murtada’s judgement is that good land in the
formerly occupied zone is worth between
$10 per m² inland up to perhaps $100 for
prime land near the coast at Naqoura.

The attraction of the coast has figured in
many of the optimistic scenarios for southern
real estate. But Naqoura remains an uncertain
prospect. It is nearly 90km often two hours
from Beirut, and as long as there is no
peace treaty with Israel, political instability
will always lurk in the background. In such
circumstances no one is likely to risk the
substantial investment required for a purpose-
built resort or even a large hotel, which
would usually require a minimum of ten
years to see any return on capital. It is difficult
to envisage anything like the $150 million
project for a 600-room hotel at Khalde
that has been drawn up by an Emirati group
represented by Faisal Awwad.

“There are just as attractive, and fairly
undeveloped, stretches of coastline much
nearer Beirut,” says Raja Makarem. He
cites a plot at Adloun, just south of Sidon,
fully 130,000m² with a 230-m coastal
frontage, that has been on the market for
months at $50 per m². At around $100, land
is available between Jounieh and Byblos, far
closer to Beirut than Naqoura, and with
ready access to the casino, nightclubs and
historical remains as well as beaches.

“Apart from perhaps land actually on the
beach at Naqoura, I doubt anything there
would fetch $100,” says Makarem. “If you
can buy land at Adloun for $50, why would
you go to the end of the world and pay $100
unless of course tourists come from
Israel. In time, with peace, I could see facilities
like a casino aimed at attracting people
to come from over the border, but clearly
that’s dependent on peace and normalizing
relations and that seems some way off.”

And that’s the coast. Inland, prices are
much lower. A 3-million m² plot at Rihane
was sold two years ago for just $3 per m²,
more expensive than Hermel but in line
with much of the Bekaa. Would it be worth
much more today?

Real estate prices are not independent of
general economic activity, which will remain
concentrated in Beirut. Banque Audi recently
estimated a 0.5% contraction in GDP in the
first quarter of 2000. And the outlook for the
southern economy is far from rosy. The government’s
$1.2 billion investment plan,
announced last month, is a target rather than
a commitment, and is dependent on Arab and
international loans: the government plan also
persists with the BOT model that is looked
upon unfavorably internationally.

In many of the Christian villages, Israeli
withdrawal may even depress land prices.
During the occupation, at least and probably
more over 3,000 people worked in
Israel, and another 3,000 received a
monthly paycheck from the South
Lebanon Army (SLA). That income is now
lost. In the SLA heartland around
Marjayoun and Qlaiya, many people have
fled to Israel and this cannot help but
weaken the economy.

Expatriate investment has figured as a
major target of post-war Lebanese governments,
seeking to tap the capital and intellectual
abilities of the 900,000 citizens,
almost one-third of the population, who
emigrated during the war. The expectation
is that returning Lebanese bring in money
saved abroad, and that they buy land and
build luxurious homes. But isolated
palaces will not regenerate the market as a
whole nor create an environment that is
conducive to investment.

“There is pent-up demand, with people
rebuilding the family home,” says economist
Kamal Shehadi. “But in the absence of
planning and zoning, there’ll be chaos. The
traditional villages that have kept their
character will be ruined by wannabe real-estate
developers.”

George Nur, who owns 5 million m² of land
a ten-minute drive inland from Naqoura,
believes that the potential of the land
depends on the government drawing up a
master plan that allows development and at
the same time protects the quality of the
region. “Unlike much of the country, it’s
not too late to save the South,” he says. “So
much of it is green, virgin. But can you find
me a buyer? I can’t believe anyone would pay
even $10 per m² for my land now.”

It is clear that the government will invest
capital although its record as a planner is
hardly convincing. The sites of schools, clinics
and other government buildings already
exist, and constructing them where they do not
is unlikely in itself to drive up prices.

Without planning the more professional
developers, says Ibrahim Murtada, will
keep well away: “I wouldn’t do anything in
the former occupied zone. It’s very difficult.
The government says it will allocate LL30
million for each person to reconstruct their
house. Instead they should build infrastructure,
introduce zonal planning and call
in contractors to build residential units.”

The South, after all, is one of the poorest
regions of Lebanon. Its main income is agriculture.
Tobacco is a major crop because of
state subsidies, but even this offers relatively
poor returns. This is not a recipe for rising real
estate prices, at least not between the immediate
positive effect of the withdrawal and a
peace treaty that opens up trade between
Lebanon and Israel. So while individuals will
build houses, corporate investment is unlikely.
“It’s risky,” says Ibrahim Murtada,
“because few people there have money.”

July 21, 2000 0 comments
0 FacebookTwitterPinterestEmail
Cover story

Who gives a dam?

by Hadi khatib July 21, 2000
written by Hadi khatib

The South’s liberation has brought back into the public eye a 40-year-old
plan to turn Lebanon into an agricultural breadbasket. With the exception
of Turkey, Lebanon is the only country in the region with more water than
it needs. But most of this water is left to flow into the sea or evaporate. The
$400 million Litany project, expected to take 14 years to complete, will channel
and contain the water of the country’s longest river for irrigation and drinking.
The river stretches 170 km and has a 2,700 km² basin, a little more than
one quarter of Lebanon’s surface area. Unfortunately, 50% of this water runs
off into the Mediterranean Sea.

A World Bank loan for the project was initially approved in 1976, but the
war put those plans on hold, until now. The government recently
obtained a $2.5 million grant from Arab donors to update studies
done on the Litany project before 1975. On May 20, Dar Al Handasah Shair
(DAH) started revising project plans.

The Litany project will be completed in several stages along with a number
of sub-projects. The biggest of these is the 800 Project, which involves
building a 57-km channel that will link the waters of Lake Qaraoun to 15,000
hectares of agricultural land in the South. Another project involves building
channels connecting Lake Aanan and Lake Qaraoun with Sidon, Iqlim
Al-Kharroub, Nabatieh and Zahrani, where 23,000 hectares of agricultural
land are cultivated. There is also the Khardali dam, which will be built on
the lower Litany to provide drinking and irrigation water.

But even before the war, the project was controversial. “The Litany water
project will have a huge impact on the current state of agriculture and drinking
water supply in the South, but it’s a crucial source of conflict in the region,”
says Marwan Iskandar, an economist. Since their 1976 invasion, Israelis have been salivating at the chance to tap
into the Litany River, says Iskandar.

And the USA has backed them all
the way on the issue. “If this [World
Bank] loan is to be approved again,
US-Lebanese relations will have to
improve and the project will have to be
part of the peace process,” says
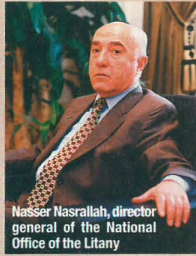
Iskandar. But Nasser Nasrallah,
director general of the National Office
of the Litany (ONL), says that
Lebanon will not bargain over access
rights to the waters of the Litany.
“There is a government decision not to
include the Litany as a bargaining chip during any regional peace talks. Lebanon’s right to full use of the river
is not an issue,” he says. Nasrallah is convinced that the entire project will
have little difficulty obtaining funding from the World Bank, which has already
financed a number of similar projects in the country.
Iskandar feels that there is an alternative. “Why take a loan if the project
can be done as a BOT (build-operate-transfer),” says Iskandar. In many
cities around the world, such as Jakarta, Sydney and London, water projects
have been done this way. Nasrallah feels that making the Litany project
a BOT is a possible alternative, but unlikely. This project is not purely
profit-driven, he says. Rather, it serves to improve the social and economic
situation in one of the poorest areas of the countr
y

July 21, 2000 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 690
  • 691
  • 692
  • 693
  • 694
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE