• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Money Matters

Shock therapy

by Executive Contributor April 7, 2000
written by Executive Contributor

There will be a new trading system soon. Please describe what it will be and when it will be implemented.

KHALAF: We’re going to start continuous trading as soon as
we have an agreement with the government. We already
have a deal with the Paris stock exchange to install the same
software program that’s used there. You’ll have on-screen
trading the same as in Paris. We’re hoping to get it within
12 months.

The first step will be the shouting system. It will be a temporary
period to get us to the computerized continuous
trading system. Because it’s a transitory period, we’ll
continue with our fixing system, but just for the opening. I
think we will open for one-and-a-half to two hours of
shouting, as in New York. The fixing system will also permit
small investors who don’t want to wait for the broker to
find other investors in order to be involved in trading.
Everybody will have a chance to trade on the BSE.

Why not a full day of trading?

KHALAF: In other countries they have much greater volume.
If we have more volume, we’ll be flexible. We’ll start with two
hours. When we find that there’s enough volume, we can go to
three hours, four hours, six hours and maybe even eight hours.


The BSE allows no more than a 5% price change in one day. Will you allow more fluctuations?

KHALAF: We will change it a little, keeping 5% for the fixing
and 5% for the shouting – 10% total. The committee can
decide to change this without going to another authority. We
will be going in steps, seeing how the market is acting and
reacting with our plans.


What are the benefits of the new computer system?

KHALAF: It will be easier for brokers to place their orders –
with just a click of the mouse. We have another proposal to
get on the Internet and link all Arab markets on the same
website. You go in and you get information on all the companies
and get connected to any trading room with continuous
pricing on it. This will start with the Kuwait stock market,
Cairo and Jordan.

Someone in another country might ask: “Is there a stock
market in Beirut?” On the Internet I have my CAC, my Dow
Jones, my Nasdaq. So if you have an Arabic website, you can
go and see what’s happening there.


When should we expect the Internet system to be in place?

KHALAF: I have to present it to the committee and sign it. Then
we can start to implement it. In the Gulf it took one year.


Are you pressing for the BSE to have a regulatory body soon?

KHALAF: As soon as possible. We are working on it. I’m
working with the minister of finance and others. Then we
have to propose it to the cabinet and then to parliament.


Can you give us a time frame?

KHALAF: I can’t say. It depends on how long it will take to
get through the cabinet and then how long it will take to be
agreed in parliament. I hope as soon as possible.

Meanwhile we can’t say there’s no department regulating the
market. The BSE is carefully watching the market, and the
central bank is carefully watching the financial institutions.
If there’s a transaction that’s not completely clear, we
can stop it and have it clarified.


It’s obvious that there is lack of transparency with some companies listed on the BSE. How are you going to improve on this?

KHALAF: What we have done is recruited someone to follow
companies for transparency, to make sure that they give us every
statement we need at the proper time. For banks it has to be every
three months, even if it’s not audited. For other companies it has
to be every six months. We haven’t implemented a fixed date.
But there is a logical time limit. As for other information, when
we think there’s information that needs to be published, we call
the company and if they don’t react we send them a letter that
they have 48 hours to inform the public.


But what about companies that are tardy with their financial statements? Will you make them pick up the pace?

KHALAF: It’s not easy to get audited year-end statements in
as early as February. In March we have to have it. We will
enforce it. We will be flexible if there’s a reason. We are not
rude, but we are becoming rigorous.


How will you control insider trading before the regulatory body is established?

KHALAF: It’s a bit hard to control insider trading with a fixing
system and little liquidity. You can control it if you are
watching your staff enough, and that’s what we’re doing.

What can we do with companies? It’s difficult. If you see someone
making a transaction and you think something is wrong, it’s
difficult to prove. We think that with the fixing system and
small liquidity, it’s easier to manipulate prices than with
continuous trading. What’s important is to prepare the market
to be more transparent and to reflect the reality of the transactions.
When you have continuous trading and more liquidity,
you cannot influence the market with only a few shares. It will
be easier to control the situation.


What’s your plan to promote the market?

KHALAF: We are working on putting together a marketing
campaign. The first step will not be talking about the BSE, only
what a stock exchange is, for the investors and the companies.
In the second phase, we will focus on what the BSE is. The third
one will include the progress made to improve the BSE.

To get to the public directly you have to go through television
and newspapers. To talk to investors in person, we will start
conferences in Beirut in April. We are also promoting the stock
exchange in other countries.


Are there any plans to relocate?

KHALAF: We’re trying to find a place in the Beirut Central
District. It will be the BSE building, in which we will have not
only the stock exchange. We have demands from financial
companies and brokers who want to be in the same building.


There is a problem getting companies to go public because of the tradition to keep business in the family. How can you persuade them to list?

KHALAF: To help encourage family businesses to become listed,
there are tax incentives. We are trying to help them become more
aware of the benefits, such as raising capital by being listed.

Dividend taxes were cut by 50%, from 10% to 5%. Some companies
want to be listed but are hesitant because of the lack of activity.
They are waiting for others to do it first. In 1997, when one bank
listed, others followed. When the first company comes, others
will follow.
April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

The Global Strategist

by Executive Contributor April 7, 2000
written by Executive Contributor

A US soft landing

US fund managers have raised their expectations for GDP
growth for 2000 and 2001. While 83% now expect Fed Funds to
rise over the coming year, they expect a soft landing free from an
upturn in inflation after just two more 25 bps rate hikes. We are
skeptical. In his Humphrey-Hawkins testimony, Alan Greenspan
said that he had been around long enough “to never take an oil
price shock unseriously”. He could have gone further in our view
and said that no central banker, himself included (1987–90),
had ever delivered a soft landing during one. Unless the oil
price falls and stays down, it still feels right to overweight cash.

European optimism is very high

A stronger than expected upturn in non-US growth could
drive the oil price higher. Europe could be one source of upside
growth surprises. Economic optimism is very high. Fund managers
assume that the ECB is hiking rates to offset the inflationary
impact of a weak euro, but they are not targeting below-trend
growth. Importantly, 77% of European fund managers think hiking
rates specifically “to defend the euro” would be a bad idea.
We agree. Such a policy could put the economic upturn at risk
by starting a vicious circle where equity capital leaves Europe,
the euro weakens further and rates are hiked again.

Getting bullish in the UK

Only 67% of UK fund managers expect base rates to be
higher in a year’s time. With inflation expectations modest, bears
of Gilts outnumber bulls by just 5% as against 37% in January.
Earnings expectations have stabilized and fund managers see
value in the market. Bulls of UK equities outnumber bears by
a strong 44%. Support for financials has risen, 41% now
choose it as their favorite broad sector. Financial stocks would
be major beneficiaries of a soft landing.


TMT: Looking for a way out

The TMT phenomenon

Global Tech, Media and Telecom stocks have outperformed the
broad equity market by a massive 180% since 1990. Relative
performance has been especially strong since the interest rate
cuts of 1998. These sectors now make up almost 40% of world
stock market capitalization. A large sector outperforming like
this demands attention. Most fund managers choose Tech,
Media or Telecoms as their favorite global sector.

How to value TMT stocks?

It can be a struggle to value these new companies. Many, especially
fledgling e-commerce businesses with high advertising
and capital spending needs, are not forecast to make a profit for
the foreseeable future. Traditional measures, such as dividend
yield or price-earnings ratio, mean nothing for such companies.
Most fund managers use PEG or EV/EBITDA to value TMT
stocks. These methods are deemed appropriate for fast-growing
profitable companies. For loss-making companies with high
scalability, fund managers prefer EV/Sales.

Overvalued and overweighted

Regardless of which method is being used, fund managers
in every region are unanimous in deciding that TMT stocks are
overvalued. However, the vast majority of these are overweight
TMT stocks. European and Asia-Pacific funds are
particularly overweight.

Looking for a way out

While Asian fund managers are generally happy with their
overweight positions, most fund managers in the US and
Europe expect to reduce their exposure to TMT stocks over the
coming year.

But what would be the trigger to make them sell TMT? In general,
managers are looking at company- or industry-level information.
A total of 57% expect some kind of sell signal from company
fundamentals, technical analysis or sell-side broker
recommendations. Only 15% think macroeconomics is relevant.

Macro factors suggest caution

Fund managers are looking for company-specific developments
to decide when to sell. But TMT stocks did not rise on a company-
by-company basis. They rose en masse. We think macroeconomic
factors will drive the reversal when it comes. Our suspicion
is that the rush into cyclical growth stocks like TMT was driven
by hopes of permanently strong growth with low inflation. The
growth stocks doing well are not the defensive ones, like consumer
products, but the aggressive cyclical ones, like technology.

The interpretation must be that the markets do not see rising
commodity prices as something that can cause inflation. In terms
of the “Investment Clock” diagram we use for our asset allocation,
the markets are assuming that we will always be in Phase II.

A new era or the Japan effect?

We are not convinced that such a new era is upon us. We prefer
to look for more mundane reasons for the strong growth and
low inflation in the US. Alan Greenspan took advantage of the
disinflationary impact of the decade-long slump in Japan by
allowing America to grow more strongly. Inflation fell as it often
does when growth is strong and competition is fierce. However,
non-US recovery could reduce America’s speed limit. As the Fed
slows growth, productivity could worsen, causing companies to
raise prices in response to rising unit costs. Rising inflationary
pressures should drive a move into value stocks. If global growth
peaks, on the other hand, cyclical earnings expectations are likely
to fall and we would find ourselves in Phase I or Phase IV.

Will Greenspan backtrack on the new era?

Alan Greenspan must target the US stock market to cut off the
equity wealth effect that is boosting consumer spending. So far
his rate hikes are having the desired effect on the Dow, but his
frequent affirmation that we are entering a new era seems to be
driving the Nasdaq higher. A strong Nasdaq could partially
counteract the dampening impact of interest rate hikes. This has
an interesting consequence. The more Greenspan verbally backs
the new era, the more he may have to raise interest rates. He risks
having to use a sledgehammer to crack a nut.

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Capital flows to Arab countries and other emerging markets expected to rise this year

by Executive Contributor April 7, 2000
written by Executive Contributor

Arab countries attracted around $9

billion in private capital flows in

1999, or 6% of total capital flows

to the emerging markets that year. Private

flows to the Arab region are expected to rise

by l 7% to around $10.5 billion in 2000,

however, growth in global private capital

flows is forecast at 30%, translating into a

lower share of 5 .4% for the Arab countries.

After declining in 1997 for the first time

this decade, private capital flows to

emerging markets fell dramatically in

1998 by over 44%, with much of the

decline in the wake of the Far East crisis.

Notwithstanding a rally in emerging markets

early in 1999, external financing for

many emerging market borrowers

remained weak with net private capital

flows rising marginally to $148.7 billion

lflst year, or by 0.6% on their 1998 level of

$147.8 billion. While p1ivate capital flows

in 2000 are projected to remain below the

average level achieved over the last five

years, it is evident that market participants

are beginning to place the financial crises

of the last few years behind them, with net

private capital flows expected to rise to

$193 billion this year.

According to the I’nstitute of

International Finance, foreign direct

investment (FDI) into emerging market

economies rose to a record $139 billion in

1999 (94% of total private capital flows),

after $118 billion in 1998, but is expected

to retreat to $120 billion this year, largely

reflecting lower flows to Latin America.

Most emerging stock markets performed

well in 1999, particularly towards the end

of the year, and a rise in portfolio equity

investments into emerging stock markets

is anticipated this year with the volume of

investments rising to $34 billion from

$17 billion in 1999 and $13. 7 billion the year before. Around $1.8 billion or less

than 5% of total portfolio equity investments

into emerging markets are forecast

to go to the Arab stock markets this year,

compared to $1.5 billion in 1999.

FDI flows to the Arab countries are

expected to reach $5.2 billion in 2000,

from $4.5 billion in 1999. Although the

share of Arab countries in global FDI is set

to rise from 3.6% in 1999 to an estimated

4.6% in 2000, it remains very low.

However, the announced intentions of

several Gulf countries to open up their

energy sectors to foreign participation,

alongside economic reform and liberalization

policies across the region and a

stronger privatization drive in some Arab

countries will help boost the Arab world’s

share of global FDI flows. Furthermore, a

clear progress in the peace negotiations

between Israel and Syria will reduce

regional risk and enhance the attraction of

the region to foreign direct investment.

Net private credit flows (including

bank Joans and bond issuance) to emerging

countries is expected to rise to about

$40 billion this year, after a net credit outflow

of $7 billion in 1999. Bank credits to

emerging markets this year are expected

to be slightly negative at a $3.1 billion outflow.

This follows a rush out of emerging

markets by commercial banks (mainly

from East Asia and Russia) in 1998 and

1999 with net credit outflows of $49 billion

and $39 billion respectively. Bond

issuance by major emerging market borrowers

amounted to $55 billion last year

compar.e4 to $74 billion in 1998 and

$109 billion last year. The recovery in

bond issuance witnessed in the last quarter

of 1999 as investor appetite for

emerging market paper returned and

spreads fell significantly, is likely to continue

this year with bonds issued in the

international market by Arab governments

and corporates forecast to reach

$2.5 billion in 2000 compared to $2.3

billion the year before.

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

The numbers issue 12

by Executive Contributor April 7, 2000
written by Executive Contributor

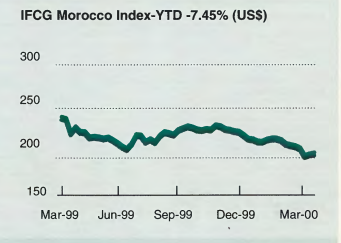
MOROCCO Equities on the Casablanca Stock
Exchange remained under pressure,
with most investors opting for the
sidelines in anticipation of 1999
corporate results. Share prices headed
mostly downward in thin liquidity as
institutional selling outweighed buying.
Total assets under management by local
institutional investors in Morocco
reached $4.3 billion at the end of
February, down 2% since the beginning
of the year. Of the total, around 13% are
invested in local equities. On the
privatization side, the flotation of
state telecom company Itissalat
al-Maghrib looks unlikely to be effected
before 2001. This will be the real driver

for an improvement in the market’s
fortunes.


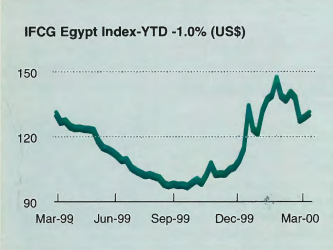
EGYPT

A profit-taking spree swept through
the Cairo Stock Exchange (CSE) ahead
of the holiday season in mid-March.
However, the market weathered the
storm, narrowing year-to-date losses
to just 1%. Trading was mostly
concentrated in a handful of blue chips,
with Commercial International Bank,
MobiNil and Media Production City
capturing most of the market activity.
Investors also reacted favorably to the
news that the Egyptian bourse has
preliminary approval from the New York
Stock Exchange to list some Egyptian
companies in the form of American
Depository Receipts (ADRs).

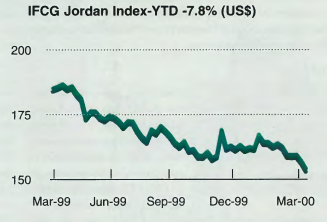
Prices slid across the board in Jordan
under the sway of increased dumping
by foreign investors. During the first
two months of 2000, non-Jordanian
investors purchased an equivalent of
JD12.2 million worth of local securities,
while they divested a total of JD48.5
million. The market is now down almost
8% from its level at the beginning of
the year. Selling pressure was mostly
concentrated in major banking and
industrial blue chips. The poor
performance was recorded despite the
release of healthy 1999 corporate
earnings results by a score of blue chip
stocks, among which is Jordan Cement
Factories (up 73%).

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money MattersUncategorized

newsbrief issue 12

by Executive Contributor April 7, 2000
written by Executive Contributor

The Messiah?

Chafic Muharram, former vice governor
of the central bank, has been asked to
take over the helm of the faltering Banque
Libanaise pour le Commerce (BLC) by the
bank’s general assembly. As chairman and
general manager, it is hoped that he will
steer the financial institution out of what has
been an almost unending series of troubles.

First came the nasty break-up of the
Byblos Bank–BLC merger. Then, what
seemed like a flawless marriage between
BLC and the United Bank of Lebanon
turned into a disaster when the central
bank demanded that Safi Harb, the bank’s
new chairman and the mastermind behind
the merger, get the boot after he was implicated
in illegal money lending.

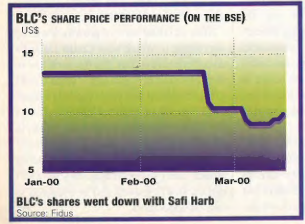
Confidence has been waning on BLC, a
listed bank on both the GDR market and
the Beirut Stock Exchange (BSE). This comes not only
from the botched mergers. Analysts have
also become disgruntled over the BLC’s tardiness
in reporting its yearly results. They
claim that the bank lacks transparency,
with very little in the way of public access
to the consolidated financial statements for
the recent merger.

According to one analyst, “The appointment of Muharram is what
BLC needs today. He has experience in
the central bank, is conservative and the
bank needs stability. This may bring confidence
back to the bank.” He adds that the
major shareholders were put to the test:
The central bank requested a $40 million
raise in capital and a $50 million subordinated
loan to the central bank, and they complied.

But, throughout the Harb fiasco,
the performance of the bank’s shares has
been dismal, with stocks plummeting 27%
on the BSE and 28% on the GDR market so
far this year.

Holding on

The only closed-end investment fund listed
on the Beirut Stock Exchange suffered
a second disappointing year in 1999. The
value of Lebanon Holding’s portfolio
dropped 13%, from $45.8 million in 1998 to
$39.7 million last year. It started at $50 million
when it was launched in August 1997. Its net
asset value fell from $9.16 to $7.99.

The fund, which invests strictly in local
companies, got hurt the most by its stake in
two industries. Liban Beton, a leading
ready-mix cement company, has been hit
hard by the paralysis in the construction
sector and has suffered heavy losses.
Lebanon Holding also had to write off its
$4.4 million investment in the pipe maker
Eternit, which is filing bankruptcy after
several years of losses.

The bulk of the fund’s portfolio is in listed
banks – such as Banque Audi, Byblos Bank
and Banque du Liban et d’Outre-Mer. But,
despite their solid fundamentals, the banks’
shares, like the remainder of Lebanese
stocks, have been performing poorly.

Lebanon Holding is trying to buck the downturn. In the fourth
quarter, the company increased its stake in
Société des Grands Hotels du Liban
(SOHL), owner of Vendome and Phoenicia
Hotels, and First National Bank. Phoenicia
just opened last month, and, says Khalil
El-Khoury of Lebanon Holding, “It is the only
five-star hotel with five-star service in Lebanon. It
will have excellent cash
flow in the future, and its
stocks will probably
surge.”

But the future of the
fund and its shares, which
dropped 21% in 1999,
remain doubtful. According to one analyst,
“It can only see brighter
days when there is peace.”

A new Bou

Bou Khalil Markets (BKM) will be
adding a fifth supermarket to its chain,
this one in Ras Beirut. The new store –
smaller than the others at 2,800 m² –
is the second
to open in the last five months, following
the opening of a 4,000 m² Bou Khalil in
Tripoli last October. More are planned during
the next five years.

Sales, in the meantime, have been on the
rise for the supermarket chain, increasing to
$15.47 million by June 1999, 17.25%
above sales figures for the same time in
1998. But earnings have been declining,
dropping to $602,000 during the first half of
1999, 17.3% below earnings for the first
half of 1998.

“The chain is undergoing
heavy expansion, bigger than expected,”
says Walid El Khalil, head of the investment
firm Tulip Investments, who helped take
Bou Khalil public when he worked for
Banque Libanaise pour le Commerce’s
capital markets division. “Expenses shoot
up more than revenues during expansion.”

Bou Khalil’s shares have also suffered in
1999, down 17.6%.

A quick and

efficient IDAL,

hopefully

The Investment Development
Authority of Lebanon (IDAL) is trying
to make Lebanon a little more
investor-friendly. The organization has
opened a special office called “One-Stop
Shop,” which will assist investors in
getting through what is seen by many as a
maze of bureaucratic procedures.

IDAL is also planning to set up an
“Investors and Business Information
Center” to provide statistics, economic
data and relevant information for starting
a business in Lebanon.

“It’s a great idea because it will
reduce a lot of the bureaucratic difficulties
and red tape that investors have to go
through in order to invest in Lebanon,”
says Nassib Ghobriel, a Lebanon Invest
research analyst. “The real question,
however, is whether they will be able to
follow through with their intentions.”

IDAL recently announced that the long
delayed Linord project to rehabilitate
Metn’s northern coastal highway, from
Antelias to the Beirut port, will be relaunched
by summer. The project
requires the reclamation of 2.4 million
m² of land, the construction of a new
sewage plant, the development of an oil
storage facility, a marina and a small harbor
at an estimated cost of $550 million.

Last year, when the project was first proposed,
IDAL had trouble finding
investors. It remains to be seen if any of
them have changed their minds.

Top of Form

Gobbled up

Bank of Lebanon and Kuwait SAL
(BLK) may have a new owner.
Jordan’s Al-Ahli Bank, which has five
branches in Lebanon and has been operating
here for 39 years, signed an agreement
to acquire an 85% stake in the financial
institution for $22 million.

The deal, part of
the bank’s strategy to expand in Lebanon,
Jordan, and throughout the Arab world,
will create a medium-size bank with 11
branches, total assets of $250 million and
customer deposits of $200 million.

“When
a foreign bank wants to expand in
Lebanon, the best way is through acquisition;
they won’t be allowed to get a license for more than two branches a year,”
says an analyst at Lebanon Invest.

The
owners were looking to sell at a time Al-Ahli
was shopping around. “After studies
were done, we chose BLK because it’s a
clean bank, with a clean loan portfolio and
high capital,” says Rafic Aramouni, Al-Ahli’s
general manager. “Based on the
bank’s ratios we don’t expect any surprises,
unlike many other banks, and the size of
its staff and the number of branches were
appropriate.”

The bank’s aim, Aramouni
adds, is to become one of the larger financial
institutions in the country. The central
bank has given its preliminary approval to
the purchase and final approval is expected
within weeks.

Bottom of Form

Canning them

kindly

When your business starts suffering
losses, the first thing to do is cut
costs. That often means making the tough
decision to let go of workers. Société des
Ciment Libanais, Lebanon’s largest cement
producer, had plans to lay off 300 employees
after the company’s net income fell
from $14 million in 1995 to a net loss of 1.1
million in 1998.

The news, obviously, was
not greeted kindly by the company’s labor
union, which promptly intervened to try
and stop the move. After a six-hour meeting,
a compromise was reached between SCL’s
management and staff. Instead of layoffs, the
company would offer a cushy early retirement
package to hundreds of its employees,
giving them 36 months’ salaries in addition
to end-of-service indemnities they would
receive from social security.

“There are already nearly 100 people who accepted
the offer,” says Antoun Antoun, head of the
SCL employees’ union.

SCL invested in a
$165 million furnace before discovering
that demand for cement was below expectations.
With construction grinding to a
halt, demand for cement nose-dived, with
deliveries dropping 25%, from 4 million tons
in 1995 to 3 million in 1999. Insiders feel
that the company’s losses in 1999 will be
much higher.

Cyber trading

A new online trading website called
myTrack.com was recently introduced
in the Middle East by Dot-LB, the
agent of Net2Phone. The company is marketing
myTrack in 9 countries: Lebanon,
Syria, Jordan, Kuwait, Egypt, the United
Arab Emirates, Saudi Arabia, Cyprus and
Turkey.

The website requires users to download
special software (5 MB) and open a
minimum cash account of $500. Non-US
citizens are exempt from a tax on profits, but
they are required to open an account at
the Bank of New York for trading on
Nasdaq and over-the-counter (OTC).

Commissions will cost $15.95, and customers
will have to choose between three service
plans ranging in price between $20 and $80
a month. According to marketing manager
Ibrahim Choueiry, Dot-LB’s revenue
will depend on the number of clients it signs
up. So far, the company’s client base has
grown to 200 in 50 days, mostly Lebanese
and Lebanese expatriates in Arab countries.

“We expect to break even in about five to six
months,” says Choueiry.

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Proving to be a threat

by Peter willems April 7, 2000
written by Peter willems

Not a bad start.

Only two

years after the

central bank let Credit

Libanais loose in the

market – followed by a

complete restructuring

program (see “Back to

life,” December 1999)it

outshone the leading

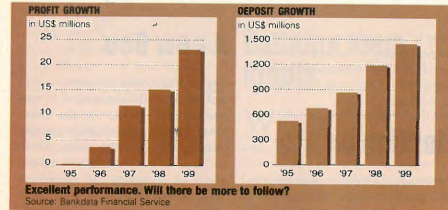
banks. Net income

jumped 52.5%, from

$15.l million in 1998

to $23.1 million last

year, while average

profits of the top-tier

banks dropped 3.7%

(Bankdata Financial

Services). Bank of

Beirut came in second,

up 27.6%. Credit

Libanais’ strategy is to

become a strong retail

bank, and results are

coming through. It led

its competitors in

deposit growth and non-interest income increased over 10%,

above the two leaders in retail banking,

Banque Audi and Byblos Bank.

But questions are beginning to surface. Is

Credit Lihanais a threat to the top retai I

banks? Leaping into the market with a

splash soon after Saudi entrepreneur

Khaled Ben Mahfouz bought the bank is

one thing; maintaining healthy returns in the

years to come is another. “The test is not

today,” says Ziad Maalouf, vice president at Middle East Capital Group. “The test is

this year and the next few years to come.”

According to Spiro Youakirn, senior

manager of corporate and project finance at

Schroders, Credit Libanais is well positioned

to compete in retail business. It has

a far-reaching branch network with 49

outlets and is highly liquid – 69% of liquid

assets to total assets. Youakim argue~ that

in the long term, “Retail banking revolves around retail lending, and once economic

conditions improve, Credit Libanais will be

able to he a major lender.”

Credit Libanais has already taken a step

forward in lending. Last year its loan portfolio

shot up 43%, “Most of our loan

growth has been in small consumer lending,”

says Andrew Stephens, head of retail

banking. “What we tried to do is speed up

the decision process so the customers enjoy coming to us,

rather than taking a

week or more to get a

loan. For small loans,

we can virtually agree

on the spot.” It also

cleaned up the faulty

loan portfolio inherited

from other banks it

acquired under the central

bank’s control. By

collecting $4.3 million

and writing off bad

loans, its non-performing

loans to gross loans

dropped from 26% in

1998 to 11.8% last

year, which is around

the average for the

leading banks.

Audi is still considered

the leader in producing

products and services:

“It always pays for

Audi to be the innovator

and to be the first in the

market,” says one analyst.

But Credit

Libanais is not far

behind, having already developed insurance,

leasing, phone banking, free Internet and ecommerce

facilities. Already the leader in

credit cards, its number of cards issued and

points of sale through businesses increased

20% last year.

Will it whip out more products this year?

“Enough is enough for now,” says

Stephens. “Customers can only take so

much. They mostly want fast, efficient and

value for money services. They don’t like you to mess around with their money too

much.” Instead, the bank will focus mostly

on cross selling existing products, which

fits in with its restructuring program to be

more sales oriented, turning its outlets into

points of sale.

Credit Libanais is also looking into

acquiring the American Express outlet in

Lebanon, which has over $80 million in

assets, within the next few months. “It’s a

good small bank that has a small portfolio

with prime, high net worth customers,”

says Credit Libanais’ chairman and general

manager Joseph Torbey. The bank knows

American Express well: It has an exclusive

partnership with the American bank as the

service provider for it~ cards, accepted only

through Credit Libanais’ network.

But some analysts see a weakness Credit

Libanais bas to work on to be a real competitor

in retailing and maintaining steady

growth. “The new upper management that

was acquired recently is high caliber, but

human resources and services at the outlets

have to improve,” says one analyst. “If you

want to establish yourself as a retail bank, it’s

the service and the quality of staff behind it.

Credit Libanais is slower in tenns of training

and improving the quality of service,

especially compared to Banque Audi.”

Stephens replies: “We’ve recognized it and

we’re doing something about it. Training

began 12 months ago, and it will go on and

on.” Another issue is cost control. Its costto-

income ratio came out at 60.5% in 1999,

higher than Banque du Liban et d’Outre-Mer

(44.3%), Byblos (52.8%) and Audi

(56.2%). But with increasing efficiency

being a part of the restructuring program,

Credit Libanais’ cost-to-income dropped

7 .2 % from 1998, the largest decrease

among the top-tier banks.

After an initial burst of growth, it will be

interesting to watch how Credit Libanais

does from here on out. But the bank has an

idea of where it is heading. “What Credit

Libanais started two years ago was a statement

that we’re open for business,” says

Stephens. “We’ve put the building blocks in

place and we’ve done some good business.

We’re going to build on those building

blocks, and I see no reason why we can’t

sustain steady growth and be prepared to

take on opposition.”

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Streamline to the bottom line

by Peter willems April 7, 2000
written by Peter willems

Expectations for most industries are
fairly routine. When sales sink in
the middle of an economic slowdown,
earnings should follow suit. Not so
at Uniceramic, Lebanon’s leading ceramic
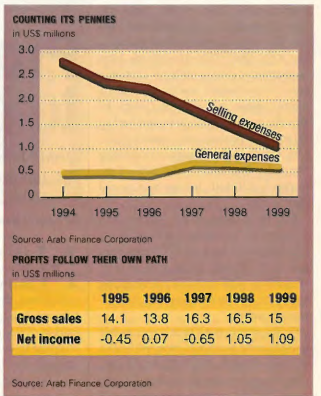
tile manufacturer, whose sales dropped 9%
in 1999. Surprisingly, its sour sales performance
did not drag down profit growth;
instead, net income inched up 4.3%, from
$1.05 million in 1998 to $1.09 million.

Uniceramic’s formula was simple. With
revenue boxed in, the manufacturer has
been going through a major overhaul to
reduce costs across the board. A restructuring
program began in 1998 with the help of
Consulting & Development Services
(working with other big names, such as
Société Nationale d’Assurances and Obegi
Consumer Products) and Dr Christoph
Ackermann, a German expert who has 40
years of experience in tile manufacturing
and now sits on the board of directors. The
program pinpoints every aspect of the
company’s activities to raise efficiency and
enhance productivity (see “Back in the
black,” May 1999).

The results of the makeover have come
through. Cost of goods sold per m²
dropped from $3.65 in 1997 to $3.32 last
year, while general expenses declined from
$744,000 in 1998 to $689,000, down
7.4%. On the selling side, Uniceramic
changed its strategy from being mostly an
exporter in the early 90s to focusing on the
domestic market. In 1994, business abroad
took up 70% of sales. Last year local sales
accounted for 88%, which helped decrease
cost of sales by 24.6%. Its workforce was
also streamlined, down from 340 to 300.

“Sales going down and profits on the rise is
a rare occurrence,” says Fadlo Choueiri,
Arab Finance Corporation’s (AFC) project
officer. “Sales in tiles are directly correlated
with the performance of construction and
real estate. It’s cyclical. Had Uniceramic not
implemented a restructuring program, it
would have really suffered. But since they
did it, they have performed well, working
against the tide.”

What will Uniceramic do to continue
improving as Lebanon moves into another
year with little sign of economic recovery?
For one, the restructuring program isn’t
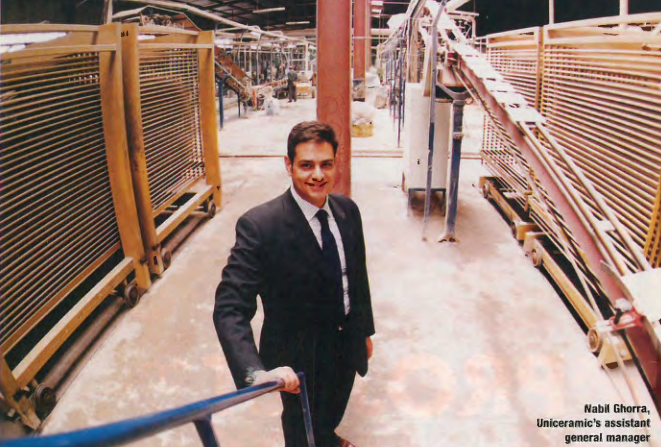
finished, according to Nabil Ghorra,
Uniceramic’s assistant general manager.
“Thirty percent of restructuring will be
implemented this year,” he says. This will
include additional cost reduction in
administration, financing and production.
“We haven’t seen all the benefits yet,”
adds Ghorra.

On the sales side, with costs down, some
prices will be lowered. But one objective has
been to take advantage of better quality and
more variety in tiles. With a broader range
of value-added products coming out,
Uniceramic will slap on a higher price tag,
increasing its margins. AFC predicts that the
firm’s average selling price will move up
from $5.78 per m² to
$6.1 per m² this year.

In the bigger scheme of things, trouble-shooting
to enhance efficiency and production
will be a never-ending process. (More proof
of Uniceramic’s drive to improve: To
interview Ghorra, EXECUTIVE had to call
him in Fontainebleau, France, where he is in
an international executive program at
INSEAD, a famous business school.)

To buffer itself against the difficulties of
the local market, Uniceramic is looking
abroad again. Its goal: move exports up
50% in 2000, from 12% to 18% of total
sales, aiming to reach 30% by the end of
2001. It plans to increase sales in markets it’s
familiar with, like Saudi Arabia and France,
and move into the US market for the first
time. Uniceramic is also working with the
United Nations to finalize a deal to export to
Iraq this year.

In the short term, exporting will not be a
tool to generate far greater earnings. With
higher cost of sales and stiff price
competition overseas, exporting goods will
put a squeeze on margins, and as Ghorra
says, exports will initially break even.
Uniceramic’s strategy is to increase its
presence in other markets and help offset the
chance of a further downturn in the local
market, keeping production at current levels
or increasing (cost savings by economies of
scale) and selling off excess inventory.

News announced last month could give a
boost to exports. Tiles were left out of the
Lebanese-Syrian free trade agreement when
it went into effect on Jan. 1, 1999. This left
Uniceramic and Lecico to face 130% tariffs
in moving their products next door. The two
countries agreed in mid-March to make up
lost ground on reducing tariffs 25% each
year applied to other products. Custom
duties were dropped 50% and will reach
zero in 2002.

Although Uniceramic has been waiting for
this, it will take time to see real results. The
tax on tiles this year is still a hefty 65%.
Even though Uniceramic’s quality should
stand out in the Syrian market, it will be
asking for a premium. It’s estimated that its
prices will be 15% higher than tiles produced
in Syria, and Syrians are notorious for being
price-sensitive consumers. Nonetheless,
Uniceramic does see Syria as a market full of
potential. In about four years, “The Syrian
market could absorb 25% to 30% of our
maximum production,” says Ghorra.

Uniceramic has weathered the storm, but
it has other challenges to face. It’s no
longer alone in making changes to deal
with harsh conditions. Lebanon’s only
other tile maker, Lecico, invested nearly
$900,000 in new modern equipment last
year (see “The right flush?” February
2000). Also a producer of sanitary ware,
Lecico holds about 15% of the tile market
compared to Uniceramic’s 33%. Georges
Ghorayeb, Lecico’s general manager,
predicts that the investment will reduce
costs in manufacturing tiles around 18% to
20% this year.

But Uniceramic appears to have the
upper hand. It has a wider range of tile
designs and sizes and it began focusing on
efficiency earlier than Lecico. Ghorayeb
says that tile sales showed losses last year.
(Lecico broke even on overall sales, of
which sanitary ware accounts for 70%.)

“Uniceramic was really smart in having
planned ahead of time to better reshape its
position in the economy,” says Choueiri.
“We can see what happened to Lecico –
losing money on tiles because it waited to
start making changes in 1999 with a
chance to see improvements in 2000.”

Ghorayeb is expecting tiles to break
even or see a glimpse of positive returns this
year. But he admits it will not come from
grabbing a larger market share. “With a
reduction in costs making the business
more efficient, we will be more profitable,”
says Ghorayeb. “We used to produce
1 million m² of tiles and we’ll still
make 1 million m² this year.”

More important than Uniceramic’s local
rival is foreign competition. The company
had set a goal of capturing some of the
market from foreign heavies to increase its
share from 30% in 1998 to 50% in 1999.
But products from European manufacturers,
especially in Spain and Italy, are still
Lebanon’s favorite, not to mention an
increase of tile imports from Jordan and
Saudi Arabia. The market share for imports
squeaked down slightly from 1998 to 1999,
while Uniceramic’s moved up to just 33%.

One of the reasons the local manufacturer
had problems capturing more of the market
was keeping its prices constant, according to
Ghorra. Its plan to move some prices lower
and beef up value-added products may make
a difference, aided by a more aggressive
marketing campaign. The goal to take 50%
of the market is still there, but has been
moved back to 2002.

AFC firmly believes that Uniceramic’s
restructuring will allow it to show steady
earnings growth this year. AFC’s projection
is a 16% increase, up to $1.3 million.
“Regardless of the economic conditions, we
anticipate a constant growth in profits,”
says Choueiri.

He also stresses that if there’s an economic
upswing in the near future, there will be a lot
of room to grow. Not only would construction
pick up, but also 50% of the estimated
200,000 unoccupied apartments still
require tiling. Increased sales coupled with
streamlined business would push profits
up considerably.

Investors have shown little interest in
Uniceramic’s stocks, even though it has
braced itself well for the construction market
hitting the dirt. With the Beirut Stock
Exchange dead and attention focused on
Solidere and the banks, Uniceramic’s
shares haven’t budged since July 1999.

Uniceramic cleared its debt with IFC last
year (a $6 million loan issued in 1993),
which will allow the manufacturer to pay
dividends in the future.

Its P/E ratio is on the high side at 19.2, but
is forecast to drop to 16 on AFC’s projected
earnings, based on the current share
price of $1.91. One positive note:
Uniceramic is one of the most transparent
non-bank companies on the BSE. (It
reported last year’s earnings at virtually
the same time as the banks, while the others
take their sweet time.)

It’s anyone’s guess when the economy
will recover to help boost Uniceramic’s
sales. But one thing is certain: Uniceramic
has shown that revamping operations and
cutting costs can lead to selling less and
making more.

Top of Form

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Games people play

by Peter willems April 7, 2000
written by Peter willems

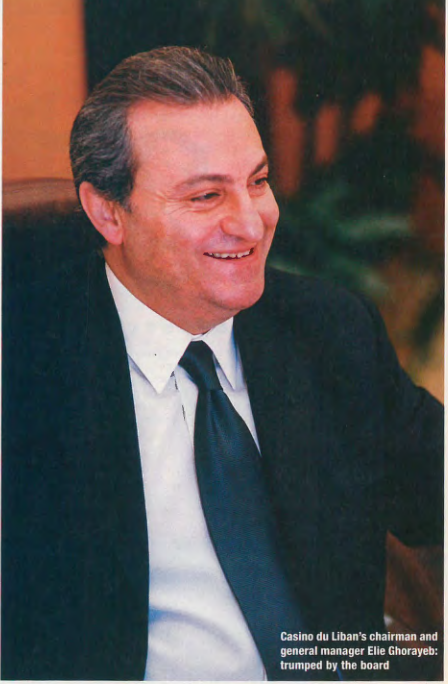
“It was a real mess,” describes Elie
Ghorayeb on what he saw when he
first came in as Casino du Liban’s
chairman and general manager in March
1999. His objective: do a clean-up job. He
concentrated heavily on cost cutting that
included reducing the casino’s bloated
workforce to 1,270, laying off 65 employees.

He also took a look at a number of contracts,
dealing with services such as cleaning
and maintenance, renegotiating seven and
canceling three. It is estimated that changing
the contract structure will help the casino save
about $3.5 million every year, with the overall
spending cuts adding up to savings
between $5 million and $6 million annually.

Ghorayeb acted quickly on the gambling
parlor’s debt as well. Two-and-a-half years
before the deadline, the casino paid back
$15 million, the remainder of a $50 million
syndicated loan used to rebuild the casino
after the war, which left the institution in the
clear. Ghorayeb was also wary of some of
the staff’s behavior. He implemented a
strict policy to make sure everybody
showed up for work, threatening to let go of
those not following through, and helped
the government uncover five employees
involved in embezzling funds.

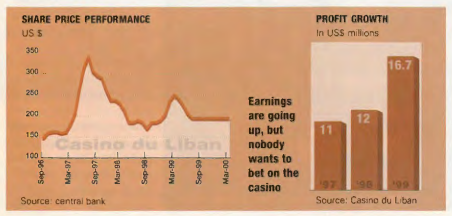
The casino’s earnings last year were
impressive. Pre-tax profits jumped 50%,
from $13 million in 1998 to $19.5 million.
The casino estimates net income at $16.7
million, close to a 40% increase from $12
million the year before. Not a bad job,
right? Wrong, according to the board of
directors. Early last month, the board threw
a punch and knocked down the chairman’s
powers. He can no longer sign or tamper
with contracts or recruit new employees
without the board’s approval.

According to board members, it’s not
exactly what the chairman did, but more the
way he did it. They complain that
Ghorayeb was operating as a loner, keeping
a distance from the board and leaving them
out in the cold as to where he was heading.

“At the beginning we delegated some powers
to the chairman, but after one year we
discovered things that were not properly
administered in a diplomatic way,” says
Majid Joumblatt, a board member. “The
board does support reducing costs where
feasible. He reduced contracts but changed
them without consulting the members of the
board. He would only tell us something
very briefly during our meetings and didn’t
give any information whatsoever, only bits
and pieces. The information was not systematic,
informative or documented.”

Some at the casino see what prompted the
board to jump on Ghorayeb differently.
One source claims that at the start the
chairman was given the right to make decisions
and implement them on his own. “He
was supposed to present his plans broadly,
not specifically. Now they want to get into
every detail.”

Sources at the casino believe that some of
Ghorayeb’s moves irritated members on the
board. They suggest that some board members
may have had ties with those involved with
the contracts that were renegotiated or canceled
and that Ghorayeb stripped several members of
their second jobs working for the casino,
which is not allowed.

It is also believed that what brought the
struggle between the alienated parties to a
head was a particular contract that
Ghorayeb really wants to change. Abela
Tourism Development Company (ATDC),
a joint venture between Abela Group and
London Clubs International, was brought in
for technical management when the casino
was back in operation a little over three
years ago. Within the ten-year contract,
ATDC is responsible for looking over a full
range of activities, including gaming, theaters
and restaurants.

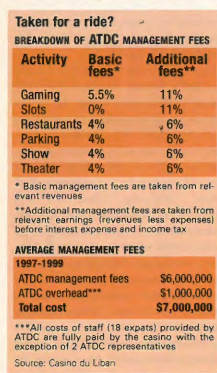
The payment structure for ATDC (percentages
of different revenues and earnings before interest expenses
and income tax) has been calculated as a
yearly average of $6 million (see table).
The casino also pays $1 million each year for
18 employees working for ATDC.

“It’s a big problem paying $6–7 million for
a counterpart doing I don’t know what,”
says Ghorayeb. A major beef, according to
one official, is that ATDC is not providing
enough services for the amount paid. He
cites only two employees working under
ATDC, outside the 18 on the casino’s payroll.
London Clubs is not being aggressive in
bringing in big foreign players and ATDC is
only giving advice that doesn’t offer
enough support.

Ghorayeb’s target is to bring ATDC’s income
down to reasonable terms. Including the $1
million payroll, it should be reduced to
between $1.5 million and $2 million,
allowing the casino to save around $5
million a year.

But some argue that, even though the
price looks high, it’s hard to estimate what
it should be. Abela Group is well known as
a multi-purpose contract company, especially
in working with restaurants and
catering. It has 33,000 employees in 40
different countries, covering territories
from North America to Southeast Asia. As
for London Clubs, it is famous internationally
for running gaming. According to a
financial analyst, whether it’s doing the best
job or not, it’s important just having the
name attached to the casino. “The casino
can’t lose London Clubs.”

Hacham Tabbara, another board member
and a regional manager for Abela Group,
goes further. He claims that Ghorayeb
doesn’t listen to suggestions given by ATDC.
“We submitted to him a written study that
ATDC is able to increase turnover by 20%
in 2000, with an additional cost of $1
million for renovations, such as tables,
increasing surface for slot machines, and
so forth,” he says.

It is estimated that revenue decreased
slightly from 1998 to 1999, which should
give credit to cost reductions increasing
earnings. Increasing turnover coupled with cost control
could push profits higher. “But he
refused,” says Tabbara. “He wouldn’t even
discuss it.”

From one source at the casino, Ghorayeb
will not let up; he plans to go on pressing the
issue to renegotiate the ATDC contract.
Talks between Ghorayeb and Abela are far
from inviting. And if there is no agreement,
Ghorayeb could take the case to an arbitrator,
which would take years and be costly.

Along with infighting, intrigue and uncertainties
(sex, lies and videotape extraordinaire),
there is also an ongoing question
about whether the casino can do better.
It’s obviously a money machine but has potential
to be a booming cash cow.

To help feed its revenue stream, the government gave the
casino a monopoly on gambling until 2026 in
return for 30% of gaming revenue (excluding
slot machines) in the first ten years, 40% in the
next ten years and up to 50% for the last ten.
It has little competition in the region — one in
Palestine and clubs in Egyptian hotels are the
best-known competitors.

But it has obstacles. Auditing firm
Deloitte & Touche estimates that the casino
can run on 1,150 employees, still 120 less
than what it has. Although Ghorayeb
claims that there has been no political pressure
preventing him from cutting the workforce,
the previous chairman, Habib
Letayf, once confessed that he was forced
to hire up to 300 employees.

In 1998 the ex-chairman was beaten up by armed marauders,
assumed to be operating for a political
power group, forcing the hiring of its own
people. This year Ghorayeb is considering a 5% reduction in staff.
But even then, the number of employees will be above
Deloitte & Touche’s benchmark.

Another weakness is its marketing campaign.
Thirty percent of the customers are
foreigners, but with little competition in the
region, the casino could push foreign
clients higher. This brings infighting back
into play.

The board claims that it established
a committee to study marketing
abroad four or five months ago. “I don’t
think Ghorayeb was able to listen at all. He
neglected everything,” says one board
member. “We could be involved in promotions
overseas much more and raise foreign customers much higher than 30%.
This is one of the most important tourist
institutions in Lebanon.”

But some argue that there’s a risk factor
attached to attracting tourists to a land still
at war. “It’s not easy to promote tourism
with no peace,” says Ghassan Matar, once
an independent consultant for the ministry
of tourism. “Israeli planes still provide fear
and you can lose tourists.”

On the service side, others argue that the
casino is hindering its progress by not following
the Las Vegas model. The key is that
non-gaming revenue is not where money is
made (about 95% of the casino’s revenue
comes from gaming); it’s only to attract customers
to gamble their money away.

“A hotel, a helicopter taking a gambler from the
airport to the hotel, cheap dinners, free
drinks — all this is crucial for the casino,”
says Nicolas Sawan, head of trading at
Lebanon Invest.

Some say that due to its monopoly and lack
of competition, the casino can get away
without pampering clients with food and
drink, but they are adamant that a hotel is
essential. In its contract with the government,
it’s supposed to build a hotel by 2001.
The casino hasn’t taken one step in that direction.

For the sake of survival (the casino would
have to pay hefty penalties and eventually
lose the contract), the ministry of finance
granted the institution a two-year extension,
according to Tabbara. Yet, putting together
any plans is still on the back burner.

Even though the casino is making
money, financial analysts don’t want to
come near its shares traded on the over-the-counter
market (and most don’t want to be
quoted directly, since it is considered a
political animal). One analyst estimates
that its earnings could have easily doubled
by now if it had put in the proper facilities,
moved heavily into marketing and reduced
costs even further.

The Financial Funds Advisers (FFA) report
published in July 1998 projected net income
to reach $29 million in 1999.

Another complaint is that the casino is not
transparent enough. “The way the balance
sheet is constructed raises a few questions,”
says one analyst. “The problem is
that the casino is not open to answering
questions. Detailed information on financials,
operations and management structure
are not readily available.”

More caution comes from the casino being
tied to political meddling. “A lot of politicians
have their fingers in it,” claims an analyst.
Better yet: “Everybody knows the casino is
corrupt,” says one broker.

Its shares reached a high point in July
1997 at $340 (from its starting point at
$148 in September 1996), but worked
their way down to $195 in mid-summer last
year and haven’t moved since. Now that its
debt is paid off, there’s a chance that the
gambling house will dish out dividend
payments in the future.

Could this create movement on the shares?
“It would please the shareholders but not much movement of the shares, because of lack of transparency
and not being as profitable as it
should be,” suggests an analyst.

The unanimous recommendation among analysts
questioned: gamble at the casino, but
don’t bet on it.

It’s also difficult to bet on
who is going to win in the
boxing arena. Many were
surprised that Ghorayeb
didn’t resign when the
board took away some of
his authority. But as one
analyst says, “He is clean
and he did a good job by
reducing costs, paying off
the debt and bringing up
profits.”

Ghorayeb faced a
mess when he first arrived, but
he has a bigger mess to
deal with now.

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Feature

Back in Iraq

by Robert Tuttle April 7, 2000
written by Robert Tuttle

August 1990, Iraq invades Kuwait. Within days, Iraq is encircled in one of the most extensive economic blockades ever imposed on a country. Almost overnight, Lebanon loses what had traditionally been one of its most lucrative markets for manufactured goods. Iraq absorbed more than a quarter of Lebanese exports in the early 1970s and as much as 75% of transit exports. Even during the war, though statistics are not available, it continued to be an important destination for locally produced goods.

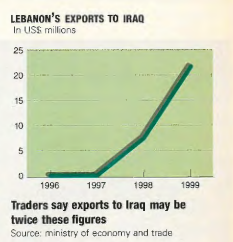
Four years after the Gulf War, relations between Beirut and Baghdad sank to a new low. When some Iraqi opposition members were assassinated in Beirut, the Lebanese government blamed Iraqi intelligence agents and promptly severed all diplomatic ties. With sanctions still intact, Lebanon sent a paltry $1,278 worth of textiles, probably donations of clothes, out of the more than $733 million in total exports, to Iraq in 1996.

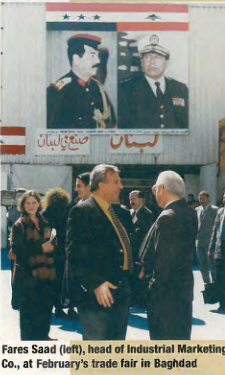
Fast forward to February 2000. Nasser Saidi, minister of economy and trade, accompanies a delegation of more than 93 Lebanese businesses and 250 businessmen to Baghdad, where he and his Iraqi counterpart, Mohammed Mehdi Saleh, open an exhibition of Lebanese industrial products. It’s the sixth exhibition in Baghdad involving Lebanese business in two and a half years and Saidi is the fourth Lebanese minister to visit.

The port of Tripoli has been designated by the Iraqi government as a receiving station for an order of sugar exports to Iraq. Lebanese exports to Iraq are up to $22 million for 1999, making it the 12th most important export destination. But most businesspeople feel that these figures are underestimated and that much of the trade is not recorded on official statistics because it passes via a third country. The real number is probably double that figure and many expect it could double again by the end of this year.

Nearly two dozen Lebanese companies have opened offices in the Iraqi capital and warming relations have led to the restoration of diplomatic ties and the reopening of both countries’ embassies.

What happened? In the last few years, regional political developments have smiled kindly on Lebanese-Iraqi relations. Mounting sympathy in the Arab world toward Iraq’s plight and a sense that the time had come for the sanctions to be lifted has encouraged Arab states to reestablish trade links with Baghdad. For the first time in 15 years, Syria’s relations with Iraq have warmed and a common border for trade was opened, a move that no doubt gave Lebanon a green light to repair its own relations with Iraq. And, perhaps most significantly, growing international concern for the suffering of the Iraqi people prompted the United Nations (UN), in 1996, to start allowing Iraq to export a limited amount of oil in exchange for humanitarian goods.

By 1996, some of Lebanon’s business leaders were looking towards their eastern neighbor. Within one year, the first contracts were being signed and the first delegation of nearly 180 businessmen boarded buses and headed out across the Syrian desert to participate in the Baghdad International Trade Fair 1997. The rest is history.

Iraq is still under UN sanctions, and it must purchase the bulk of its imports using revenues generated from the yearly $11 billion in oil exports allowed under the oil for food program. Only $8 billion of that amount can be used to buy goods. But it is also a market of 22 million consumers with very few functioning industries of its own. Once again, Iraq is partly open for business and Lebanon’s struggling industries want a piece of the action.

Obegi Consumer Products, producers of such popular brands as Persil and Al-Wadi Al-Akhdar, is selling detergents there. Cosmaline Industries has been busy selling toiletries, while Uniceramic, Lebanon’s largest tile manufacturer, has struck its own deals.

Georges Ghorayeb, general manager of Lecico, manufacturers of sanitary ware and tiles, sees the Iraqi market as a salvation for his struggling business. He has seen profits shrink to zero in the last few years. Sales on the sluggish domestic market are down about 17% of what they were three years ago and a flood of cheap imports has resulted in a 40% drop in exports to his number one market – the Gulf. Just last month he signed his first contract with Iraq in over ten years to supply 10,000 pieces of sanitary ware – toilets, sinks and bidets – for about $250,000. Ghorayeb believes he could sell double that amount by the end of the year.

Before the invasion of Kuwait, Iraq accounted for about 30% of Lecico’s total revenues. If sanctions were lifted, he says, “I expect that the Iraqi market can absorb 1.2 million to 1.5 million sanitary pieces a year. We could get one fifth of that volume.”

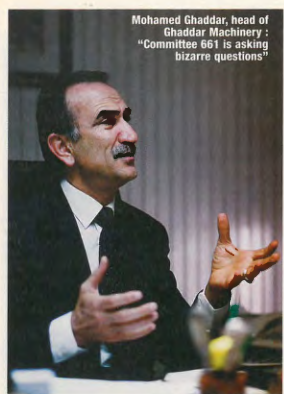
Mohamed Ghaddar, managing director of Ghaddar Machinery, one of the country’s leading generator manufacturers, credits the Iraqi market for helping to turn around a rapid decline in sales. In 1994, while the local economy was booming, Ghaddar’s revenues were around $15 million. Facing a slump in local demand, revenues nosedived to $10 million in 1995 and down to $8 million the next year.

With the local market saturated with generators, Ghaddar looked for ways to beef up exports. He found salvation in Iraq. In 1997, he signed a $1 million contract with the Iraqi government and delivered the goods one year later. Last year, he sold $4 million worth of generators. His revenues shot up to $9 million in 1997, $12 million in 1998 and last year were back at $15 million. Ghaddar’s exports have increased from 5% of revenues in 1994 up to 60% in 1999. Iraq represents his largest foreign market, absorbing about 35% of exports. Next year, he aims to sell $10 million to $15 million worth of goods to Iraq.

But as good as it may seem, there are problems. Ghorayeb complains that margins are often as low as operating at cost. Ghaddar isn’t happy because of the bureaucratic barriers. All his deals have been with the Iraqi public sector. Since Iraq is still under sanctions, the contracts must be approved by committee 661 of the UN Security Council, whose job it is to ensure that what enters Iraq is truly for humanitarian purposes.

“They [committee 661] are asking bizarre questions. For example, they ask us why this engine has a nozzle. There are no diesel engines in the world that do not have a nozzle,” says Ghaddar. Contracts that should take three weeks for approval are taking months. Ghaddar says that more than $4 million of his contracts have been put on hold, one for more than a year and a half. Others complain of similar problems.

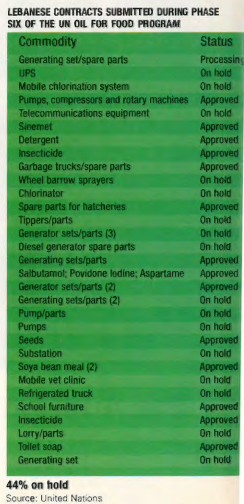
Last year Lebanese businesses submitted more than $70 million worth of contracts to the UN, according to Ghazi Yehia, secretary general of the Lebanese Industrialists’ Association. “But only $35 million actually went through, the rest got held. They didn’t get approved by committee 661,” he says. A list of contracts, submitted during phase six of the UN oil for food program, which started in May of last year and ended in November, showed that only 44% of 36 contracts from Lebanon had been approved. Most of the rest – including a number of generators – were put on hold. By contrast, for Egypt, 69% were approved. Repeated attempts to contact both the Dutch and US representatives of committee 661 for a response to these complaints proved unsuccessful.

But faults within the UN system are not the only problem. Certain industries have benefited from the Iraqi market more than others. Lebanese generators are selling briskly in Baghdad – representing as much as one third of exports – because they are in high demand and competitive with generators from other countries, says Ghaddar. But his generators are sold there with margins as low as 5%.

But for less value-added products, where factors like transportation and labor costs make a difference, local manufacturers are finding Iraq to be as tough a market to compete in as any. “Exporting to Iraq is very difficult. Prices are becoming competitive. Everyone is going to Iraq,” says Ziad Bekdache, general manager of Oriental Paper Products, who only recently started to look seriously at the Iraqi market. Prices are so low that if he starts trading with Iraq it will be at cost.

Countries neighboring Iraq have other advantages. Under the oil for food program, all Iraq’s petroleum exports must go through Turkey via a pipeline. But Jordan, the number one exporter to Iraq, has a protocol which allows traders there to barter goods directly for discounted oil, bypassing committee 661. There is also rampant smuggling of oil via Turkey and Iran. Lebanese companies do not have the privilege of accepting oil. “We cannot sell for oil because Syria would not allow it to go through,” says Abdul Wadoud Nsouli, president of Nsouli Trading Company.

Jordan also benefits from having a committee 661 office on the ground, says Fares Saad, general manager of the Industrial Marketing Company. That makes processing contracts much easier and quicker. Some Lebanese have exported to Iraq via Jordan for that reason, but the cost of shipping is higher: $2,500 to send a truck with 25 tons of goods compared with $1,500 to send a truck through Syria. For Bekdache that is too much to export paper.

He has plans to participate in an upcoming tender with the Iraqi government for 5,000 tons of notebooks. But with prices so competitive, he has no illusions about making money even if he wins contracts. “I am willing to sell at cost just to have a presence there,” he says.

That is prompting many to enter the market now. This year Lebanese business will submit more than $100 million worth of contracts to committee 661 for approval, says Yehia. Assuming that just half that amount is exported, Iraq will fall into Lebanon’s top four export markets. Last year, Saudi Arabia bought $71 million worth of Lebanese goods; the UAE bought $54 million, France $52 million and Switzerland $45 million.

But traders say that if sanctions were lifted, Iraq could absorb up to $250 million per year in Lebanese goods – close to 40% of total exports. “If sanctions are lifted we’d have a bigger share of the market and quicker procedures in fulfilling the contracts,” says Ghaddar. But the issue of sanctions will have to wait for regional political developments to smile kindly on Lebanon.

Breaking new ground

Fares Saad, general manager of the Industrial Marketing Company, could be called a trading
pioneer. If one person can be credited with opening Iraq in the last few years, it is him.

In 1996, when Iraq might as well have been the moon as far as most local traders were concerned,
Saad struck up a conversation with a delegation
of Iraqi businessmen at a foodstuff trade fair in Tripoli. “We
sent a letter to the Iraqi minister of commerce, saying that
we would like to participate in a trade exhibition in
Baghdad and see the return of relations,” he says.

One year later, in October of 1997, he organized and led
the first local delegation of traders to Iraq to participate in
the Baghdad International Trade Fair. “Ninety-one companies
participated and about 25 sold products at the
exposition. The Iraqi market was thirsty for goods.”

He has since organized the participation of Lebanese delegations
in five more trade fairs in Baghdad, three of them special
Lebanese trade exhibitions. It wasn’t easy. “At the time,
those in authority did not encourage us in regard to this
idea because Lebanon had cut relations, because of the
sanctions and because exports were tough and no one
could do it,” says Saad.

But the trade fairs have been one of the keys to the Iraqi
market in the last few years. Saad now has three goals:
the return of commerce between the two countries, the
restoration of Lebanese industry to its previous position
in the Iraqi market and an end to sanctions. “It’s not possible
to allow the Iraqis to live in such conditions,” he says.

He feels that he has achieved his goals. “Relations between
Lebanon and Iraq have been restored, the embassy has reopened, Lebanese industry
has returned to the Iraqi market and many contracts have been completed. And thirdly,
many Lebanese have gone to Iraq to protest against the sanctions,” he says. “Now the sanctions
have started to collapse.”

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
Uncategorized

A bloody mess

by Kirsten Vance April 7, 2000
written by Kirsten Vance

Who would ever imagine that
sifting through someone else’s
garbage might create a ruckus.
But that’s exactly what happened <mark style=”background-color:#fff59d”>when</mark>
EXECUTIVE toured Saida’s medical facilities.
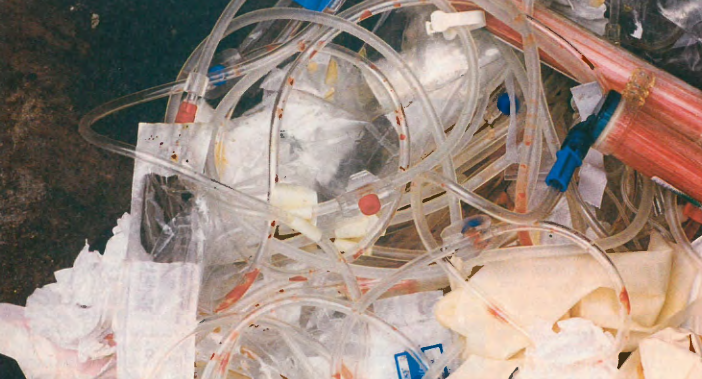
Syringes, used blood bags, tubes and IVs lay
loose and in untied bags in the bin behind
Dalaa Hospital. At Labib Medical Center,
syringes and medical gloves littered the
ground, while needles poked out of bags
inside the bin in the parking lot across the
road. There, after just one photo, hospital
security <mark style=”background-color:#fff59d”>showed</mark> up and a scuffle ensued
over the camera. After extracting the security
from the car door, the photographer and driver sped away, while this reporter ran
behind. A third, Hammoud Hospital, transported
its own waste to the city dump.

Strikingly, one of the scavengers who
inhabit Saida’s dump found the contents of
those bags too much to stomach.

Unfortunately, this is an all too common
example of how medical refuse is dealt with
in Lebanon. In the absence of any proper
national policy or waste management system,
hospitals are left to do what they will or can
within their own means. Of Lebanon’s
160 hospitals about 80% are private, with the
majority relatively small in size. That fact
alone could make enforcing a certain code of
conduct difficult. A full 75% of hospitals do
not even know how much waste they generate,
according to a nationwide survey carried
out by Dr Rita Karam, who has a PhD in
hospital waste management. Hospital risk
waste, which requires separate treatment,
includes such things as body parts, infected
materials, syringes, chemicals, radioactive
material and pharmaceuticals. Issa
Consulting and UK-based Environmental
Resource Management (ERM), <mark style=”background-color:#fff59d”>who</mark> are
working as consultants for the government,
estimate that out of a total 20,000 tons of hospital
refuse a year, about one-fifth can be considered
risk waste. That’s tiny compared to the overall daily volume of 3,000 to 3,500
tons of municipal waste. “It’s not the
amount, but the way that it’s handled and
treated that’s dangerous,” says Alissar
Chaker, environmental specialist with Issa.
“The problem is that when [the risk waste]
isn’t segregated it contaminates other waste
streams.” Some 73% of hospitals surveyed by
Karam responded that they do segregate risk
waste, while Dr Faouzi Adaimi, president of
the Syndicate of Hospitals of Lebanon,
claims that all practice segregation. “But still
you need to know if the segregation is done
properly,” says Karam. “Even if hospitals do
practice segregation, they don’t have an ideal method of disposal.” Segregation
should be practiced at each stage of storage,
transportation and treatment as well as
involve proper packaging and labeling.
Some hospitals don’t even have a budget or
waste officer responsible to follow the issue.

Currently <mark style=”background-color:#fff59d”>there</mark> is no regulation governing
how hospitals should manage their waste,
says Naji Kodeih, toxicology specialist
with the ministry of environment. “The
hospitals do what they want. In some
instances there is partial good practice,” he
says, naming the American University
Hospital and Hotel Dieu as examples.
“Partial good practice, but not complete.
This is not bad considering the prevailing
conditions in Lebanon.” But for some that is
simply not acceptable. Zeina Al-Hajj, who
heads the Lebanon chapter of Greenpeace,
refers to the situation as “complete chaos.”

When the old state-owned incinerators
were shut down in 1997, most medical
centers were no longer able to dispose of
their waste in this way. Meantime Sukleen,
which covers greater Beirut and Mount
Lebanon, refuses to collect medical waste
as it is only equipped to handle domestic
waste. “Instead of <mark style=”background-color:#fff59d”>hospitals</mark> investing in
clean technology since then, they have
continued with the same technology,” says
Al-Hajj. Some hospitals have their own
incinerators, but the conditions of those
are questionable due to the lack of control
and their location in residential areas. AUH
acknowledges that its current incinerator is
not suitable, but considers it the lesser of
several evils.

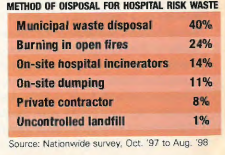
Karam’s survey found that just 14% of
hospitals incinerate their risk waste (see
chart). A large portion is disposed of
through the municipal waste system or by
burning in open fires. Illegal dumping has
been a problem, as has disposal through private
contractors. In many cases it is anybody’s
guess exactly where the waste ends
up. Some claim that medical waste also
finds its way into Sukleen bins regardless of
the company’s stance. “There’s no way we
should accept that medical waste is mixed
with domestic waste in the streets of Beirut
or Lebanon,” says Sarni Rizk, director general
of Rizk Hospital. But according to
Adaimi, most hospitals do sterilize <mark style=”background-color:#fff59d”>their</mark>
waste before disposal, as the equipment is already available for operating rooms. “It’s
not sufficient, I admit, but it’s not the monstrosity
that it’s made out to be,” he says.

In her study, Karam found that “with some
exceptions, the hospital waste management
situation in Lebanon is very far from being
satisfactory and needs to be reconsidered.”
That’s very similar to the findings of a wide-ranging
report on the state of the Lebanese
environment that was published by the ERM
in 1995. Despite its age, the report is still widely
referred to because of its comprehensiveness
and a general consensus that the situation
has not improved. At the time, ERM noted
that “most of the [hospital] waste generated
is collected and disposed of by municipal collection
systems, carrying serious risk of epidemic
and infection.” Indeed infection can be
spread through medical waste, but the source
of a disease is often difficult to determine.

While acknowledging that preventative
measures would be ideal, Dr Walid Amar,
director general of the ministry of health,
plays down the gravity of the situation. He believes there is unnecessary panic due to the
attention the issue has received, while
Adaimi talks of “psychological pollution”
because of the nature of hospital waste.
“Hospital waste accounts for barely 1% of
hazardous waste,” says Adaimi, pointing to
other sources of waste, such as industrial and
slaughterhouse waste. “It’s exaggerated.”

Regardless, due to its potentially risky
nature, management of medical waste
shouldn’t be left to happenstance. In fact the
issue has been on the table since the early
1990s. About four years ago, the Council for
Development and Reconstruction (CDR)
estimated that implementing a solid waste
management system, including hospital,
would cost $135 million. The ERM-Issa
study on hospital waste was completed in
February 1999. And now the CDR is looking
at implementing separate projects for medical,
slaughterhouse and industrial waste.
The medical waste management project, the
more advanced of the three, will encompass
hospitals, dental offices, pharmacies
and other refuse of a similar nature, according
to Sarni Ferghali, the CDR’s program
coordinator for solid waste management.

The ERM-Issa study proposed a central
incinerator with a capital cost of $8.53 million
and annual operating costs at
$903,000, or $676 a ton. The other option
is thermal disinfection, which would
require a small incinerator for certain
waste. The capital cost is estimated at
$5.58 million, with annual operating costs
at $757,000, or $485 a ton. The creation of
a proper sorting, collection and transportation
system would bump those figures up
higher. The estimated cost to hospitals is $3
to $5 a day per occupied bed, which in all
likelihood would be passed on to the individual.
Adaimi argues that waste management
should be a service covered by the
municipal taxes that hospitals already pay
and that the patient should not be made to
bear the cost. Government officials, however,
counter that convention is for the user
to pay for waste management and that
those generating hazardous waste must be
responsible for its elimination.

But before worrying about the amount of
funding required and who should foot the
bill, the problem will be in building a consensus
between the various parties
involved in the decision-making process.
Though the study concentrated on incineration,
at the request of the CDR, it is still not
clear that it will be the chosen option. The
three parties involved in the decision are at
odds. The ministry of environment wants an
incinerator that burns at a higher degree than
the one proposed, while the ministry of health favors thermal disinfection.

Proponents of the latter say it makes dealing
with risk waste possible at the hospital
level with smaller equipment, eliminating
the need for a separate collection system and
the air pollution associated with incinerators.
On the other side of the fence, Kodeih
points to the fact that <mark style=”background-color:#fff59d”>thermal</mark> disinfection is not sufficient for about 6% to 8% of risk
waste, which must be incinerated.

Incineration is generally viewed as the
more tried and tested technology, which
has been made cleaner today. But Al-Hajj
criticizes the government’s entire waste
management policy for being based on
incinerators and landfills, whereas the current
world trend is to reduce and recycle
where possible.

Amidst the controversy, some hospitals
have decided to find their own solution. Last
year Rizk Hospital replaced its 40-year-old
incinerator and has begun implementing
waste management protocols in line with
ISO standards in hopes of being certified in
2001. “The idea for a centralized system is
great, but the major hospitals can’t wait
for the government,” says Sarni Rizk, the
hospital’s director general. He’s not alone.
AUH is having a new <mark style=”background-color:#fff59d”>incinerator</mark> assembled
that will meet the standards of the US-based
Environmental Protection Agency.

The hospital had tried to implement thermal
disinfection, but found such small-scale
equipment of the new technology unsatisfactory.
The major hospitals are considering a joint investment to use thermal <mark style=”background-color:#fff59d”>disinfection</mark>
on a larger scale as a temporary measure
until the government plan is implemented,
says Azmi Imad, the director of AUB’s
environmental health and safety.

Eventually the Lebanese authorities will
have to come up with a national solution, as
many hospitals won’t find the funds or the
will to make such investments. Ferghali
says that waste management is a priority
and the CDR is pushing for the three parties
to come to an agreement. “It’s not
always easy because of the NIMBY effect.
People say ‘that’s good, but not in my
back yard.’ But things have started evolving
in the right direction,” he says. Once an
option is agreed upon and financing
secured, Ferghali estimates that the system
will take about 18 months to two years to
implement. In other words, hospital risk
waste will continue to be mismanaged at
least until 2002, and then only if a decision
is made quickly and proper implementation
and control follow. The Lebanese authorities
don’t have a good track record in fixing
what ails this country. So, don’t expect
a miracle cure.

Such a waste

Perhaps the only thing that has saved Lebanon from
being turned into an environmental disaster is the fact
that it’s not a highly industrialized country. It certainly
couldn’t be put down to sound management strategies on
the part of the government or individual diligence and care
by all industries. Both of those are sadly lacking. The fact is
that unless polluting industries are forced to stringently abide
by specific regulations, more often than not they won’t.

Discussions on dealing with industrial waste are still ongoing
between the ministries of environment (MOE) and industry,
the municipalities and the Lebanese Industrialists’
Association (LIA), despite the number of reports produced
since the mid 1990s. The ministry of industry and petroleum
produced its own in 1994, ERM followed suit in 1995, while a
massive report was prepared by Dar Al-Handasah and
another by a Dutch consulting firm a couple of years ago.

Anwar Berberi, president of the LIA’s environmental division,
contends that the reports were a waste of time and money as
they were conducted by non-experts and based on some inaccurate
data. Berberi, who has patented his own liquid waste
management system, is angry that this government hasn’t
involved the industrialists or the local experts in the process.

Hazardous waste was estimated at about 18,500 tons a
year in 1994 and projected to increase to 64,500 by 2020, according to the Dar Al-Handasah report. The largest
quantity is forecast for Mount Lebanon (see chart). ” In
Lebanon the quantity is small and the degree of toxicity low,
but there are some compounds in enough quantity to
represent a potential risk for serious pollution,” says Naji
Kodeih, toxicology specialist at the MOE, who estimates
hazardous waste at 10,000 to 15,000 tons.

In general, industries discharge waste with little – if any –
treatment into rivers, lakes, the sea, ground or sewage system,
though Kodeih notes that some of the big industries
do have their own treatment facilities. Berberi agrees, saying
that both liquid waste and hazardous solid waste are
“extremely mismanaged.” Many point to the tanneries as
the worst offenders, because of the heavy metals produced.

Kodeih says the government is working with large
enterprises such as the Lebanese Chemical Company and
Eternit, which still uses asbestos. Cimenterie Nationale
alone has spent $12 million to become more environmentally
sound. There is also a unit within the ministry that is
working on eliminating CFC emissions.

But finding the right fix across the board will not be easy.
Berj Hajian, the MOE’s director general, declined to meet with
EXECUTIVE to discuss delays in finding and implementing a
solution. One problem is the disorganization and distribution
of industry in Lebanon, says Kodeih. “It’s a question of
zoning. You have small industries in residential areas, and a
low awareness among the general population, industrialists
and decision-makers about the hazards of some waste produced.”

Currently there are some 22,000 industrial units scattered
around the country. It is estimated that over 70% are
backyard industries employing less than five people, while
just 2% are considered to be large, employing over 250. The
highest concentration of industry is in Mount Lebanon (see chart). And many industrial units are located outside
designated industrial
zones. There is a proposal
to cluster each type of
industry together so that
they can share the same
infrastructure, including
waste treatment, and
benefit from economies
of scale. But that is still
controversial. According
to Berberi, it’s a question of so many different parties wanting to take control. To
date, nothing has been decided. There are also few recycling
facilities as many have been forced to shut down due to economic
difficulties.

Many raise concerns about the level of pollution in certain
areas. But so far there has been no serious study on the effects
of industrial pollution on the environment or public
health. There is a high level of bronchitis and respiratory
diseases in Chekka and the population is affected immediately
around the plants in Zouk and Sibline, according to
Mutasem El-Fadel, professor of environmental and water
resource engineering at American University of Beirut.

The Dar Al-Handasah report proposed three alternatives
for managing each industrial wastewater, solid waste and air pollution.
It estimated the
national cost at $0.24
per cubic meter of
wastewater and $16.5
per ton of solid waste,
while preferring pre-treatment
of liquid
waste and segregation
of hazardous waste at
the factory. “The problem
in reality is not whether we have standards or not but
the means of implementation, this is the real problem,” says
Kodeih. One problem is financing: The MOE has one of the
lowest budgets of all ministries – it has been allocated just
$2 million this year. But it must be strengthened to act. Until
then, any plans or legislation will just continue to collect dust.

April 7, 2000 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 699
  • 700
  • 701
  • 702
  • 703
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE