• Donate
  • Our Purpose
  • Contact Us
Executive Magazine
  • ISSUES
    • Current Issue
    • Past issues
  • BUSINESS
  • ECONOMICS & POLICY
  • OPINION
  • SPECIAL REPORTS
  • EXECUTIVE TALKS
  • MOVEMENTS
    • Change the image
    • Cannes lions
    • Transparency & accountability
    • ECONOMIC ROADMAP
    • Say No to Corruption
    • The Lebanon media development initiative
    • LPSN Policy Asks
    • Advocating the preservation of deposits
  • JOIN US
    • Join our movement
    • Attend our events
    • Receive updates
    • Connect with us
  • DONATE
Tech Knowledge

The race to cyber autobahn

by Carl Gebeily July 10, 2000
written by Carl Gebeily

The Internet is a well-stocked stream
if you’re fishing for information,
but a common phone line and a dial-up
modem make for slow trolling. That’s
why avid computer users have longed for a
way to cut the time spent idling, waiting for
the CNN website to appear on their screens
or their eBay bids to be recorded.

In terms of access, all roads lead to the
Information Superhighway, it’s simply a
matter of how much of a hurry you’re in to get
there. There is the way of the masses: the well-beaten
path whereby you, along with countless
others, are connected to the web with a
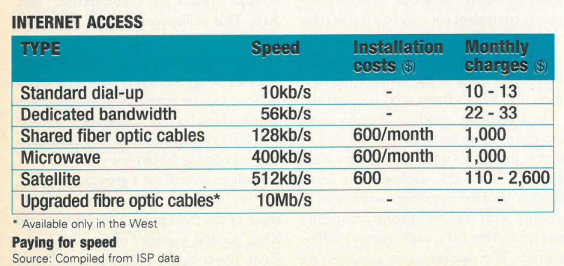
common phone line. At an average of 10 kb/s
(the rate is as much a function of the number
of users online as it is of your modem
speed), dial-up access is,
without a doubt, the slowest way to
surf. It’s also the cheapest, with monthly
charges for unlimited access ranging from
Terranet’s $9.99 to Cyberia’s $12.99.

Most local ISPs also market business-oriented
packages that are essentially dedicated
bandwidth connections (no one else is allowed on
your e-path) that are leased for an average
of $22 to $33 a month and provide download
speeds of 56kb/s, or more than five
times the pace of a regular line.

If you want to move off the path altogether
and onto motorway access, the high-speed via
internetica, then you’ll need to adopt a costlier
technology. In cable-modem systems,
which are well established in the West, top
speeds can be more than 45 times what the best
dial-up connection provides. In Lebanon,
with the absence of a cable network, surfers
have to resort to more expensive microwave
or satellite connections to acquire similar
high speeds. “Faster is always better, if you
have the means,” says Ranya El-Asmar of
Data Management, a local ISP that provides
package deals for both super-fast microwave
and satellite services. For example, downloading
a 1Mb file (about 37 pages of text)
takes 16 seconds via microwave or satellite
compared to about ten minutes by phone.

However, the price of
microwave modems remains
exorbitantly high, and has discouraged
all but big corporate subscribers who need a
reliable point-to-multipoint system. Clients
must have a receiver/transmitter, leased by the
ISP for $600 a month, before they can make
a great leap forward in speed for a further
$1,000 a month.

Satellite systems are marginally cheaper
with rates around $600 for installation and the
cost of a dish, as well as a monthly fee
depending on the amount of information to
be downloaded, $110 for 230Mb, $2,600 for
10Gb. Connection speeds via satellite are on
par with microwaves with throughput
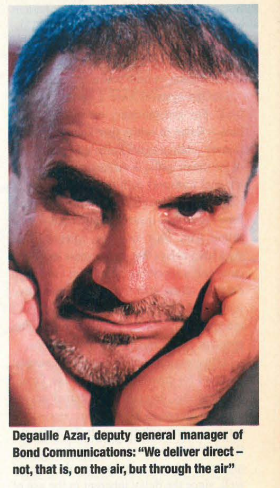
speeds that top out at about 512 kb/s. “We
deliver direct, not, that is, on the air, but
through the air,” says Degaulle Azar, deputy
general manager of Bond Communications,
whose Direct-PC satellite program has 25
customers in Lebanon. “There is a growing
client base that is more interested in quality
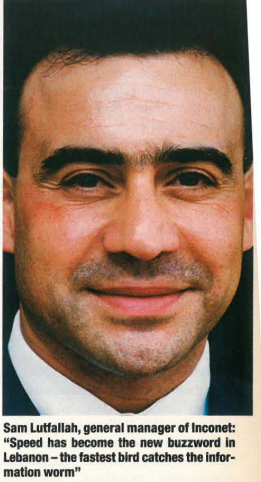
and speed than in the price of a service.” Sam
Lutfallah, general manager of Inconet,
agrees. Since the launch of its satellite service
in April, the ISP has attracted 20 customers
ranging from small businesses to hospitals
and universities. “Speed has become the
new buzzword in Lebanon, the fastest bird
catches the information worm.”

Once connected, the high speeds of
microwave or satellite open up a world where
the Internet’s treasure trove of news, information
and entertainment is as handy as a
phonebook and as vivid as television.

However, speeds do fluctuate. In the case of microwaves, the ultra-fast connection hastens
only a portion of your trip to and from the
Internet. You’ll still have to share the lines from
your provider to the Internet, and from the
Internet to the website you’re trying to view.

Satellite systems have a different drawback.
For geostationary earth orbit satellites,
those in orbits that keep them stationary
relative to the Earth’s surface, one
of the major issues is the latency inherent in
a signal transport path that’s 22,300 miles
long in each direction. That translates into a
time lag of one-quarter of a second for the
round trip, plus framing, queuing and
switching delays that can increase the latency
to half a second or more, far too long a
delay to allow effective use of interactive
real-time applications. And there isn’t
much that can be done about the propagation
speed of electromagnetic transmissions.

Software compatibility is another essential
standard for enterprise satellite use. Given
the booming demand for Internet access
and the growing reliance on networks,
satellite compatibility with TCP/IP (the
standard Internet protocols) is particularly
important. Latency plays a role here as
well, since the delay inherent in the use of
geostationary satellites is long enough to disrupt
the acknowledgement handshaking
that is at the core of the packet transmission
system. To ensure usability, vendors are
scrambling to deploy solutions that include
data compression, packet spoofing (fooling
the sending TCP/IP system into continuing
to transmit data before acknowledgements
are received), and caching frequently
accessed Web data close to the requesting
systems. That way, delays in accessing that
data will be lessened.
In Lebanon, though, the most important
disadvantage to satellite systems is that
they are asymmetric, that is, given the
monopoly of the ministry of post and
telecommunications (MPT) on outgoing
traffic, you can download directly off
cyberspace, but you have to go through a
local ISP to upload. This turns into a key
selling point for microwaves as this technology
lets users stay constantly connected
to the Internet without tying up a phone line.
But given that the current cost for both
microwave and satellite is more than 50
times the monthly charges for standard
dial-up connections, only about 150 subscribers,
all corporate accounts, have
been able to afford the luxury of supersonic
speed. That’s paltry potatoes compared
with the nationwide rollouts of broadband
services that have about 85,000 customers
for dial-up connections.

Arab Finance Corporation (AFC), an
investment house, has been a heavy user of
microwave technology for almost two
years. According to project officer Fadlo
Choueiri, the microwave system carries
heavy data traffic between AFC’s office in
Gefinor and the world’s stock exchanges.
“That traffic includes trading transactions
and daily capital market activity, which
even on a dedicated land line would take too
long,” he says. “Microwaves have turned out
to be a more cost-effective technology than
any of the land-based alternatives.” Also,
many distributors in this security-conscious
age have firewalls that won’t easily allow the
broadband signal through, not an issue
when it’s delivered by microwave using a
secure dedicated connection.

The insurance company, Medgulf, is similarly
satisfied with the extra fleetness
brought on by their switch to microwaves. It
chose microwave technology because it’s the
most cost-effective way to get its bandwidth-
intensive programming out to the
field and in the words of IT manager, Walid
Sayyad, “because there’s no pipeline I
have to deal with. I don’t get clogged up.”

Microwave and satellite systems offer
businesses a number of other advantages.
“Deployment and cost-of-ownership comparisons
between terrestrial and satellite or
wireless carriers are difficult to make, particularly
in a country where infrastructure
issues are thorny,” says Azar. “A satellite service
is equivalent not only to a frame relay
access device but to the associated routers as
well.” Thus, the satellite services vendor
handles far more of the network management
than will its frame relay counterpart.

As a corollary, satellite systems come
close to offering the single point of contact
that is the Holy Grail of wide-area management.
In the US, satellites have found
success because customers were tired of
dealing with regional phone companies
and landlubber ISPs, each charging different
rates. With satellite access, customers are required to deal with only one provider.

“We’re still far from the US model,” concedes
Lutfallah. “We need to be able to cut
out the local loop, to upload and download
with equal ease over a long-distance carrier.
Dealing with just one provider would also
bring down the magnitude of the charges.”

But why use satellites in this age of redundant
terrestrial broadband capacity and near-commodity
pricing? “We looked at delivering
terrestrially versus satellites and quickly realized
that in going point-to-multipoint, satellite
is more efficient and cost-effective,” says
Azar. That realization is music to satellite
vendors’ ears, but it has been slow in coming.
First envisioned as a way to bring data and
voice telephony services to parts of the world
difficult to wire terrestrially, geostationary
satellites have become a component of many
WANs (Wide Area Networks) and distribution
networks during the last few years.

Satellites overall are a growing business,
but they’re starting from an “insignificant”
share of the market, says Naveed Ahmad
Khan general manager of Satco (Middle
East). The company is the agent for Fortec Communications, a US company with an
estimated 30% of the total market share of the
satellite industry. “The fact that local ISPs are
turning to wireless shows a certain maturity
in the Lebanese market,” says Khan.

But the fact remains that satellite and
microwave services have yet to capture a
substantial portion of the otherwise skyrocketing
digital transmission market.
However, these technologies enjoy a loyal
customer base when it comes to point-to-
multipoint applications. Satellite data transmission
can’t compete on price with terrestrial
systems for individual point-to-point
connections, and few say that will change in
the foreseeable future. In the developed
world, satellite’s strength is in delivering digital
content to large numbers of geographically
dispersed recipients or in collecting
inventory, point-of-sale or credit-card validation
data from multiple locations.

Nonetheless, even in the West, satellites are
rarely the easy choice for enterprise data or
content transmission. Dedicated lines are
still the safe option. That’s not just out of habit
or concern about new technology, terrestrial
fiber offers faster maximum bi-directional
point-to-point throughput. In North
America, major terrestrial carriers are
already upgrading their fiber-optic backbones
which will be capable of transmitting
data at up to 10 Mb/s, that’s a whopping 20
times faster than satellites and microwaves.
In Lebanon, though, and given tight control
by the MPT, such gains in terrestrial speeds
may be as distant as a decade away.

In global terms, Khan says typical estimates
put satellite traffic at 3% of the communications
market and forecast a 14%
annual growth rate between 2000 and 2005. Those numbers pale compared with
the amount of optical fiber already laid in
conduits, the new fiber backbones scheduled
to be laid in the West by 2005 and the
increase in carrying capacity expected.
Analysts’ projections of the annual growth
in demand for data transport over the next
decade range from 30% to 80%, but supply
is likely to outrun that substantially. These
growth rates are expected to be mirrored in the
local market, albeit in more humble fashion.
Another example of the terrestrial infrastructure
expansion comes with PSINet
Lebanon, whose recent entry into the market
with the purchase of Lynx, offers an alternative
to satellite and microwave with speeds of
16 kb/s to 512kb/s, a guaranteed 64kb/s goes
for a monthly $1,000. It’s currently the only
local ISP with a fiber optic link straight from
Lebanon to North America. And since about
85% of all Internet activities run on the
American backbone, this translates as significant
cuts in delay, typically 53% on the
30kb/s norm of a copper cable. “Ours is
essentially a super-carrier service as we cut out
the intermediate hubs and nodes en route to the
US, which other ISPs face,” says Hugues
Pouillie, IT consultant for PSINet Lebanon.
The main snag with their system is that, in the
absence of fiber connections between the ISP
and the end-user, microwave receiver/transmitters
are de facto required, bringing with it the
monthly microwave charge of $600.

Analysts anticipate that the next generation
of satellites will deliver business users a radically
lower price, exponentially expanding
the market. And Khan predicts that the satellite
pricing will move away from dedicated
bandwidth to a shared model that would further
reduce the cost to the end-user.

In the final analysis, the future of high-
speed Internet may be a contest between double-
quick microwaves/satellites and runaway
fiber optics. In such an e-landscape, it will be
hard to tell the tortoise from the hare. And even
if capacity upgrades in the cable systems
become so impressive as to leave satellites in
the dust, the cable-free service should continue
to thrive in rural areas or, as in the case of
Lebanon, where high-speed wire line services
will take some years to develop.

El-Asmar is confident that, with Data
Management’s new satellite service, the
firm will be up to the job of moving around
big bursts of digitized data, thereby providing
the technology for surfing the web as close to
real time as possible.

The initial customers for Internet via satellite
tend to be veteran internauts. But both El-Asmar
and Azar predict that the packaged
content provided by companies like theirs will
become increasingly important as more
inexperienced users sign up for high-speed
service and that, given the choice, few will opt
for the steamboat when there are regular
flights to the Internet world.
July 10, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Global research Highlights

by Executive Contributor July 10, 2000
written by Executive Contributor

Economic focus

United States

• The economy’s performance is shifting from truly spectacular to
merely good. Mounting evidence points to a slowdown in growth.
The latest sign was declining retail sales figures for a second consecutive
month; another was the drop in housing starts for May.
Looking further ahead, we are becoming increasingly convinced
that the current tightening cycle is at an end.

• As we have pointed out in the past, the equity market tends to do
well once the Fed finishes tightening. After the last three Fed tightening
cycles, the S&P 500 was up by an average of 14% after a year.
The healthcare, consumer-staples, and financial sectors outperformed
the overall market on those occasions. The tech sector had
a mixed performance.

• Whether the tech sector outperforms the overall equity market
seems to depend on whether it is growing faster than the overall
economy. During the second half of the 1980s, tech spending as
a share of GDP held steady, and the tech sector underperformed the
overall equity market.

• Things changed dramatically after that. Since 1991, the tech share
of GDP has risen steadily. During that period, including the year
that immediately followed the end of the mid-1990s Fed tightening
cycle, the tech sector outperformed the overall equity market
by a wide margin.

Global view

• Is the US current account deficit, which could be as much as 4.2%
of GDP this year, a good or a bad thing? What about Japan’s projected
current account surplus of 2.5% of GDP? We recently examined
those questions and reached the following conclusions:

• The US current account deficit reflects robust investment spending,
not excessive consumption and a declining savings rate. The
composition of US investment spending shows that most of the new
capital associated with the current account deficit has been used
to fund business fixed investments; the bulk of that has been directed
toward producers’ durable equipment, a category that includes
high-tech goods such as computer systems and software.

• Because the US current account deficit is financing productivity-
improving investment activity, it should, in essence, “pay for itself.”
With that in mind, it ought to be clear that the deficit is hardly the
Achilles heel of the current US expansion, as some market participants
maintain. As we see it, it would take decades for US deficits,
at their current share of GDP, to push foreign liabilities to a dangerous
level. There is little risk of a “dollar crisis,” in our judgment.

• It is possible that foreign sentiment about America’s growth
prospects could turn negative, making overseas investors less willing
to provide capital to the US economy. That would raise the risk
premium on US assets, effectively tightening credit conditions and
slowing the pace of investment spending. Even so, it is more likely
that a more moderate rate of economic growth in the US will gradually
reduce the economy’s reliance on inflows of foreign capital.

• We believe that the tech share of the US economy will continue
to expand during the next couple of years. Companies everywhere
are in the midst of what is probably the most rapid change in corporate
business models in history: they must successfully harness
the Internet or wither away.

• The advance of technology is primarily responsible for the
remarkable acceleration in productivity growth that is evident in the
economy. In a speech that some market participants dismissed as
being devoid of policy significance, Fed Chairman Alan
Greenspan ascribed more than half of the acceleration of productivity
during the past seven years to the spread of technology. He
asserted that most of the productivity pickup is structural, not cyclical,
and therefore won’t fade away, and he explained why the broadest
measure of US productivity, as good as it looks, almost certainly
understates actual productivity growth. We heartily concur.

• Ultimately, it’s the improvement in productivity that enables the
economy to expand rapidly without inflation, accompanied by
strong corporate earnings growth and rising real wages. Because
tech spending remains so strong, we believe that productivity will
continue to grow rapidly. If it does, inflation will probably
remain a no-show while corporate earnings continue to rise,
albeit more slowly.

Bruce Steinberg, chief economist

• The experience of Australia and Canada, two countries that have traditionally
relied on foreign capital to support investment spending, provides
some perspective on the US situation. Even if the US were to run
large current account deficits through 2010, the resulting net foreign-liability/
GDP ratio would be only somewhat above the level in Canada
today and well below the level in Australia. Both countries have
attracted the capital inflows needed to finance their current account
deficits without major currency-market disruptions.

• The Canadian and Australian examples also make clear that there
are long-term risks associated with large current account deficits:
the currencies of both countries have been weakening on a secular
basis. If the US current account deficit remains near current levels,
the dollar may eventually weaken too.

• The situation is much different in Japan. That country’s current-account
surplus is a product of unattractive domestic-investment
opportunities. Japan’s savings surplus is rising, and much of it
is being mopped up by public-works spending. When government

Top of Form

Strategy focus

United States

• Is the stock market vulnerable to good news? Although we
believe that it is too soon to determine if the Federal Reserve has
successfully engineered a soft landing for the US economy, the
macroeconomic news so far in June has been encouraging. As a
result, we think that the relief rally in equities, marked by the NASDAQ’s
recent one-week advance of 19%, could persist if
investors increasingly believe that the Fed has completed its tightening
campaign. That stance is in sharp contrast to investors’
extremely risk-averse position at the end of May.

• We suspect that the Fed may need more data to become convinced
that growth is slowing. From an investment-strategy perspective,
we think that a significant downturn in consumer confidence is needed
to confirm that the labor market has indeed softened. That said,
the probability of a soft landing appears to have increased, and that
has improved the prospects for US financial assets. Accordingly,
we have shifted 5% of our Institutional Tactical Assets Allocation
(ITAA) portfolio out of international equities and into US equities.
Another consideration was the deterioration in international markets:
there has been growing uncertainty about the Japanese recovery
and speculation about a Bank of Japan tightening before the end
of the year; in addition, the recent rally in the euro and a stronger-than-
expected rate increase by the European Central Bank point to
a tighter monetary policy in Europe.

• Furthermore, we have become less cautious about US financial
assets than when we launched the ITAA (and the ML Investment
Clock) early in March. At that time, estimates of growth and inflation
were being upgraded, short rates were set to rise further, and the
strongest worldwide synchronized industrial upswing since 1994
was taking place. Those conditions, which were negative for
financial markets, are not what they were.

• The other significant change that we have made to our ITAA model
is that we have closed out our 5% exposure to commodities and shifted
that allocation to bonds. A number of factors suggest that the environment
for bonds will be better than for commodities during the second
half of 2000, provided that inflation remains subdued as cyclical
productivity gains unwind. For example, evidence is growing that

Technical focus

United States

• The stock market’s recent hesitation may be a consolidation of its
previous gains that will lead to a further recovery in the next months.

• The stock market has had a shallow pullback after a fairly strong
rebound. The rebound pushed most short-term momentum indicators
into moderate overbought territory, but left most intermediate-
term measures in neutral-to-oversold positions, leaving room for an
extension of the recovery. Looking further ahead, the market’s recovery
from its spring lows has not yet shown any evidence of the strong
investment spending declines, the upward pressures on Japan’s current
account balance and the yen may intensify.

Michael Hartnett, senior international economist
Matthew Higgins, international Economist

the global business cycle will peak during the third quarter; key cyclical
indicators have started to turn down; the OECD leading indicator
for April shows a further slowdown in the year-to-year rate of
growth; the pricing component of the NAPM survey showed a sharp
decline for May; the inventory-to-shipment ratio in Japan has
stopped improving; and consensus forecasts for industrial production
for 2000 and 2001 have stopped being upgraded.

• Our assets-allocation shift has implications for our US sector rotation.
First, the prospective peak in global growth in the third quarter
means that the window for outperformance by the basic-industries
sector is closing fast; we have thus reduced the sector’s
overweight. However, we remain positive on energy.

• Second, we have increased our exposure to bond-sensitive and defensive-
growth sectors. The economy may be facing a soft landing, but
a decline in GDP growth from 5.4% for the first quarter of 2000 to
3-to-3.5%, which we think the Fed would prefer, is likely to have some
braking effect on prospective earnings. Historically, downturns in the
NAPM survey have coincided with declines in I/B/E/S prospective
earnings growth.

• Finally, we remain selective toward the technology sector. As
Steven Milunovich, global coordinator of our technology
research, observes, “An economic slowdown is not good for technology,
given a positive correlation between capital spending and
technology outlays.” However, he sees two mitigating factors:
when corporate profit margins narrow, tech spending tends to do
well; and he also thinks that spending on Internet infrastructure
is unlikely to slow in a soft landing. In addition to the defensive
computer-services group, we think that some areas should
escape the worst of any slowdown. As we see it, for example, the
optical fiber build-out should continue, growth in ecommerce
applications ought to remain strong; Internet infrastructure
should continue to develop, and storage demand seems to be insatiable.
We think that semiconductor stocks could perform fairly
well in a modest slowdown because of the current undercapacity
in that sector. •

David Bowers, chief investment strategist
Cheryl Rowan and Lisa Cullen, investment strategists

breadth momentum that would be an indication that a long-lasting
advance has started. Even so, some long-term measures are gradually
improving; for example, 54% of NYSE common stocks are
above their 200-day moving averages, suggesting that the majority
of stocks, most of which are mid-to-small-cap issues, are slowly
reversing their post-April 1998 down-trends. That, in turn, suggests
that this year’s expected transition phase from narrow
strength in the technology sector to a broader advance during the next
year or two is still on track.

• Our main concerns about the durability of a recovery, and about subsequent
downside risks, are primarily associated with the state of sentiment
and speculative indicators as well as the recent faltering of
many “value stocks” in the basic-industrial, retailing and consumer-cyclical
areas. The latter condition seems to imply that a significant
economic slowdown may develop, one that could further delay the
next major upturn in this potential long-term leadership area.

• On balance, however, we think that the market still has the potential
to fashion a near-term recovery in which the DJIA and S&P 500 might
approach, or marginally exceed, the peaks they reached earlier this year.
The NASDAQ Composite could regain about half of its March-May
decline, moving it back to the low-4000 area. Beyond those levels, we
still expect the overall market to have bouts of testing or weakness during
the summer-to-fall period. Such tests may be more severe for the
NASDAQ/tech complex than for the NYSE/value area of the market;
they could produce at least further probes of the NASDAQ 3000 level.
If the indicators were to improve substantially during such a setback,
a durable and major advance could emerge late in 2000 or early in 2001.

• Candidates for accumulation on weakness include, in our view, a
number of energy-sector stocks as well as selected stocks in such
improving groups as airlines, brewers, specialty chemicals, computer
services, health care services, primarily hospital management
and managed care, fertilizers, agricultural machinery, gaming,
and some restaurant chain and lodging issues.

Richard McCabe, chief market analyst

Currencies/commodities

• The dollar’s short-term momentum versus the euro is constructive.
However, the greenback’s medium and long-term oscillators have
peaked or are close to peaking, its sentiment measures are overbought,
and the currency has had a breakdown through its post-October
uptrend line. On balance, it is more likely than not that the dollar has
recorded an important top against the euro as well as against other European
currencies. The dollar has already moved into major chart support
at $/euro 0.952-to-0.977.

• The dollar is in much better shape against the yen. Its technical condition
versus the Japanese currency has improved across the board lately,
pointing to better prospects in the weeks ahead. Even so, the greenback
is currently stuck in a multi-month trading range. That range displays
strong first resistance at ¥/$ 109.10-to-110.80; second resistance
begins at 111.70. The dollar will probably have to break out through those
levels to lay the foundation for a sustainable rally.

• Is there a threat of commodity inflation in the air? “No, but …”. A
look at the Dow Jones-AIG Index and its components tells the story.
The index is up by about 14% so far in 2000, but it would be down
if it did not include the 55% jump in its energy component. The
industrial metals area is off by 7% since the beginning of the year,
precious metals have lost 5%, livestock is up by 1%, and soft
coffee, cocoa, sugar and cotton, are more or less unchanged.

Walter G. Murphy, senior international market analyst
William O’Neill, senior commodity strategist

July 10, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

The need to contract out management of social security funds to professional asset managers

by Executive Contributor July 10, 2000
written by Executive Contributor

Arab countries have relatively
large pension and social security
funds by the standards of developing
countries. However, they lag behind
in terms of the efficiency with which they
utilize the long-term financial resources
they mobilize. In several cases, the investment
performance of social security corporations
in Arab countries suffers from
their utilization as captive sources for
financing government expenditure. Given
the right conditions, these corporations can
serve as a countervailing force to banks in
the country, helping to promote financial
innovation, modernize capital markets,
improve transparency and disclosure conditions,
and deepen domestic stock markets.

The long-term feasibility of the social
security institutions’ current investment
policies in the Arab world needs to be reexamined
especially in light of the aging
of the population. In general, Arab
countries have very young populations,
raising little concern over the long-term
sustainability of the systems in place.
However, with the projected rise in the
demographic dependency ratio of the
various Arab countries, pension funds
and social security corporations must be
allowed to pursue the most optimal
investment patterns of the resources they
have, independent of government influence.
This can be achieved by allowing
the pension and social security institutions
to contract out the management of their
funds to professional asset managers.

The importance of pension and social
security funds varies considerably from
one country to another. For the majority
of developing economies, the assets of
these funds amount to less than 20% of
GDP, and often less than 10%. In contrast,
for most European and North American
countries they fall within the 30% to
100% range, while in a limited number of
countries, such as the Netherlands and
Switzerland, they come up to over 100%
of GDP. A number of Arab countries,
particularly Egypt, and to a lesser extent
Jordan and Morocco, have managed to
mobilize a large volume of pension savings.
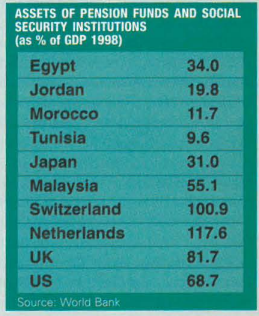
In Egypt, the assets of social security
and pension funds amount to nearly 34%
of GDP. The percentage is less for Jordan
and Morocco, around 20% and 12% of
GDP respectively, while Tunisia lags further
behind at less than 10% of GDP.

In Jordan, the assets held by the Social
Security Corporation are financed by a
15% contribution rate. The system has so far
benefited from a low dependency ratio
(the number of beneficiaries against the
number of contributors), and from a positive,
albeit modest, rate of return. The
higher volume of mobilization of pension
funds in Egypt is partly explained by a
higher contribution rate, 26%, and therefore
substantial annual flows. Similar to
Jordan, the system benefits from a predominantly
young population, but has suffered
from highly negative real returns in the
late ’80s and early ’90s. Social pension
systems in Morocco and Tunisia have
lower contribution rates and are already
under pressure because of limited accumulated
resources.

The role of social security institutions and
pension funds in the development of a
country’s capital market depends on the
allocation of their assets, which varies widely
between countries. In the UK, pension
fund portfolios are heavily biased towards
equities, while in the rest of Europe they are
concentrated in government, corporate
and mortgage bonds and long-term loans.
In many developing countries, social security
funds have failed to provide a direct
stimulus to the development of domestic
securities because of requirements to
invest in non-marketable government
securities, quantitative investment limits or
conservative investment policies.

In Arab countries, social security and
pension funds are subject to direct government
influence, with exceptions. In
Jordan, the influence of the government is
indirect; investments are constricted by
the conservative policies of the Social
Security Corporation. In Egypt, social
security resources are transferred to the
National Investment Bank to be invested in
public projects. Social security institutions
in Tunisia and Morocco must invest in
low-return government notes, low-interest
housing loans, in addition to building low-
rent housing units. Such practices have
kept investment income low.

Social security institutions are also often
restricted from investing in foreign assets by
regulations in the form of either foreign
exchange controls and/or tight prudential
controls. The relaxation of these controls in
some countries has allowed them to build
up large holdings of foreign equities and
bonds, exceeding 20% in Saudi Arabia,
the UAE and other Gulf countries, and contributed
to higher rates of return. The
inclusion of foreign assets in investment
portfolios of social security corporations in
the other Arab countries would increase
returns and reduce the risks of portfolio
funds under management.

July 10, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Regional Markets , Issue 15

by Executive Contributor July 10, 2000
written by Executive Contributor

MOROCCO

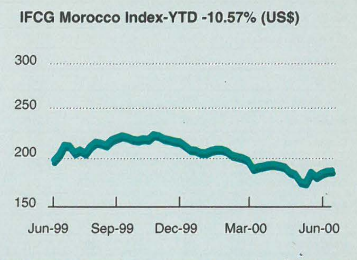
The Casablanca Stock Exchange was almost unchanged
in thin trading marked by narrow movements
in blue-chip stocks. The market continues to lack direction
in the absence of concrete steps to attract dwindling
local and foreign institutional investors. News of
the expected listing of Managem, the mining arm of
conglomerate ONA Group, sparked some enthusiasm
and is expected to ignite interest on the dormant bourse.
Also, healthy corporate earnings for Maroc Telecom,
which is expected to be privatized this year, drew investors’
attention. The telecom company reported a
55% increase in 1999 net profit to $190 million.

EGYPT

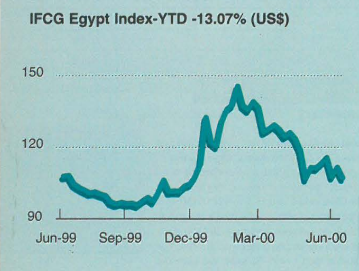
Egyptian equities continued to linger in negative territory,
affected not only by the bearish performance of the
global markets, but also by the continuing liquidity
shortage in the local marketplace. The bourse dropped to
a new year-low as institutional investors remained on the
sidelines. Amid a lack of positive news, retail investors
initiated a selling spree across the board that led to
heavy losses in major blue-chip stocks, notably Media
Production and MobiNil. The selling pressures were the
result of investors’ attempts to liquidate part of their
holdings ahead of an expected IPO in Orascom Telecom.

JORDAN

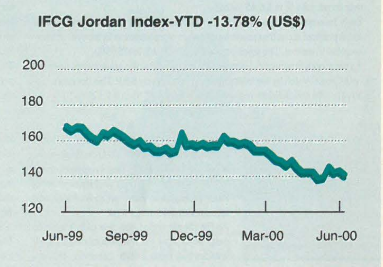
Despite a general mood of optimism following the Israeli
withdrawal from southern Lebanon, Jordanian equities
succumbed to a fall in heavyweight Arab Bank, which
faltered under strong foreign selling pressures. Investors
remain wary of the banking sector in Jordan in light of
Jordan National Bank’s record loss of around $24 million
as a result of hefty provisioning. The economic slowdown
in Jordan has taken its toll on Jordanian banks’ asset
quality, and the aggregate level of non-performing
loans in the Jordanian banking sector has significantly increased
in 1999 and is not likely to improve in 2000.

July 10, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

the numbers , issue # 15

by Executive Contributor July 10, 2000
written by Executive Contributor
July 10, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Sign me up

by Executive Contributor July 10, 2000
written by Executive Contributor

The government demonstrated its creative
inclinations, or that its feet are
not entirely on the ground, when it
launched five-year interest-free T-bills
geared towards the Lebanese expatriate
community. What an altruistic lot those
emigrants must be. They’re apparently
willing to forego possible return-generating
investments in order to lend a helping hand
to the debt-ridden government of their distant
homeland. Sounds more like charity
than a sound investment instrument. “I
don’t think anyone is that generous, especially
the Lebanese,” says one analyst. “It’s
pie in the sky.” And we’re not talking about
chump change, either. Each T-bill will be
sold for $100,000. In real terms, ‘investors’
are guaranteed that upon maturity the T-bills
will be worth less than the purchase price.
The T-bill special was announced at a recent
conference for the Lebanese expatriate business
community held in Beirut. The finance
ministry has set its sights high, hoping to
raise some $10 billion, in other words, find
100,000 Lebanese willing to part with
$100,000, to retire a large chunk of the $22
billion debt. “But expats won’t put money into
the country until they see clear signs of the
government getting its act together,” predicts
the analyst. Even then, they might prefer a
chance, however slim, of making a gain.

Shout it out

The government has given the go-ahead
to continuous trading on the Beirut
Stock Exchange (BSE), a move that might
pump some new life into the stagnant
bourse. Trading will start with fixing, followed
by two hours of an “open outcry” session. There will be a 5% limit to price fluctuations
in both fixed and continuous trading.
The BSE will have the freedom to increase
price limits and trading times in the future.
“We prefer to start with two hours of trading,”
says Fadi Khalaf, the market’s chairman.
“We don’t have enough volume for, let’s
say, four hours of trading. When volume
increases, we can increase trading time to
three, four, five hours, whatever the market
needs.” Computerized continuous trading is
scheduled to start next spring, with technical
assistance from the Paris bourse. But most
analysts are skeptical that continuous trading
is the key to increasing trading volume.
“Continuous trading will have minimal
impact in the near future,” says one analyst.
“What is needed is an economic recovery and
more listings, hopefully done through privatization
first. However, this government is
notorious for being slow. So an increase in
trading on the BSE will probably take time.”

Here I am to save

the day

Lebanon’s industries are
about to get a much-
needed shot of
adrenaline. The
European Union
has signed an
agreement to
extend an 11 million-
Euro grant
of $10 million, to
finance an industrial
modernization
program.

The grant will be
used to modernize
some 200 small and
medium-size businesses
in order to
improve the competitiveness
of the
Lebanese industrial sector.
In addition, the ministry of industry and the
United Nations Industrial Development
Organization have devised a three-year $4.5
million program for the development of local industry. “Every bit of aid is a step forward,”
says Fady Abboud, chairman of the North
Metn Industrialists’ Association. But, he
adds, grants are not enough to make local
industry competitive. Steps must be taken to
reduce the high costs incurred by local industries,
he says.

Borrow some more

The Lebanese government will cover
eurobonds that mature in July with a
$400 million rollover issue. It will be a five-
year dollar bond. Holders of the bonds will
be able to exchange their existing paper for
the new bonds, while it will also be for sale
on a cash basis. The spread is likely to be at
least 300 basis points higher than US
Treasuries. The widening of the spread is
believed by many to be the result of shrinking
investor confidence in Lebanon.

Recently, Standard & Poor’s (S&P) put the
country on CreditWatch and might downgrade
Lebanon in the fourth quarter.
Georges Corm, minister of finance, argues
that S&P’s position had little impact on the
spread. “Because of changes in the US T-bill
rate, spreads are getting thinner. You
have to increase the spread to keep a
similar yield for investors,” says Corm.
He expects the bulk of purchases to
come from local and Gulf banks.

The rollover eurobond is
expected to have a coupon
between 9.25% to 9.5%.

Just in time

Two out of three Lebanese
banks planning to issue
eurobonds have proceeded
with their debt issues. Credit
Libanais issued a three-year
bond worth $55 million. The
paper carries a floating rate
with a yield of 230 basis points above the
three-month Libor rate. Bank of Beirut
issued a three-year eurobond worth $60 million.
It carries a floating rate and offers yields
of 225 basis points above the three-month
Libor rate.

“The purpose is to have a diversification of
resources and stability. The CDs are for three
years while deposits for customers are for 50
days [on average],” says Elie Abimrad, Credit
Libanais’ financial controller. The debt issues
could not have come at a better time. Standard
& Poor’s is threatening to downgrade
Lebanon in the fourth quarter if the government
does not take serious action to reduce its
deficit. If the banks had waited, they might have
paid higher rates on their bonds.

Another bank

bites the dust

The central bank intervened to prop up
the struggling Inaash Bank. The bank
had accumulated $40 million worth of bad debt
that had not been provisioned. A new general
manager for Inaash was appointed by the central
bank, which also asked the family-owned
bank to close at least $20 million in loans that
might violate article 152 of the code of money
and credit concerning lending to members of
the board or related parties.

“It’s typical central bank behavior. They’re
very keen to maintain a decent and clean banking
sector,” says Nicholas Photiades, analyst
with Thomson Financial BankWatch. “But at
the end of the day maybe you need to have a
bank fail to send a signal to the others.”
According to Photiades, Inaash was a small but
aggressive bank that wanted to modernize.
“But I think it bit off more than it could chew,”
he says.

Two of Lebanon’s top ten banks appear to be
interested in acquiring Inaash, which last published
financial results in 1998. At that time, the
bank had about $300 million in assets, loans
worth $115 million and just $31 million in
provisions.

Investor friendly

The Investment Development Authority of
Lebanon (IDAL) has announced that
its recently established one-stop-shop service
has been a resounding success. The
agency claims that it has received applications
for projects worth $300 million.
Furthermore, the agency helped the Hilton get
a license to build a $100 million hotel in the
Beirut Central District, as well as a $11 million
hotel called the Oasis in Soufar and a $6
million residential complex in Aley. “These
projects appear to be genuine,” says Nassib
Ghobril of Lebanon Invest. “Even the sponsors
of the projects concur that IDAL helped
them get licenses.”

Fund having little fun

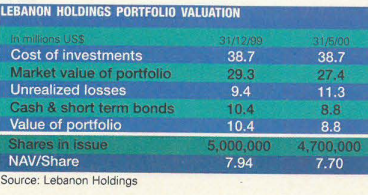
The value of Lebanon Holdings, the only
closed-end fund listed on the Beirut Stock
Exchange (BSE), dropped from $39.7 million
to $36.2 million during the first five months of
this year while the market value of its portfolio
(excluding cash and short-term bonds) fell
from $29.3 million to $27.4 million. The 6.5%
market value drop was not as bad as the BSE’s
13.5% decrease in the same period. To help stabilize
its net asset value per share (NAV),
which slipped from $7.94 to $7.70, the fund
bought back 6% of its shares this year.

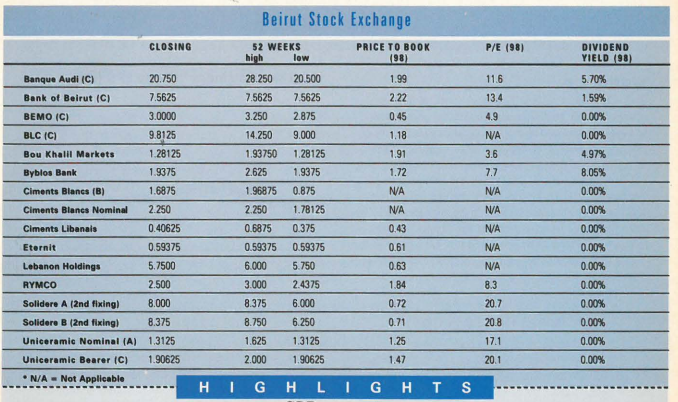
Lebanon Holdings’ shares, which rarely
change hands, are priced at $5.75, 25% below
its NAV. According to Khalil El-Khoury, associate
at Lebanon Invest Asset Management
and the investment advisor for Lebanon
Holdings, Lebanese stocks’ valuations have
become ridiculously low. “We believe that the
market bottomed out,” says El-Khoury, “and we
think that now is the time to buy.” Banque du
Liban et d’Outre-Mer’s P/E ratio, for example,
is six times below last year’s earnings.

Lebanon Holdings’ position in Societe des
Grands Hotels du Liban, which owns
Vendome Hotel and recently opened
Phoenicia, has already gained 10% this year and
the company is expecting to increase its earnings
from $3 million in 1999 to $15 million in
2000. The problem is that the trading volume
for Lebanese stocks has not picked up.
According to analysts, if the BSE is ever going
to pick up, the country will need an economic
boost. Privatization would encourage more
companies to list on the BSE and a comprehensive
peace agreement would increase
interest in Lebanese stocks.

Banking on the South

Good news for banks interested in opening
branches in the newly liberated
South. The central bank has decided to grant
three branch licenses for every commercial
bank planning to open branches in the area.
The standard central bank policy has been to
allow commercial banks to open just two
branches per year, one every six months.

Now, says Marwan Nsouli, vice governor of
the central bank, “as soon as they [banks]
submit requests with proper feasibility studies,
they will immediately receive the licenses.”
He adds that several requests to open
new branches have already been given to the central bank. “You have to
go to your customers, not
wait for them to come to
you,” says Mounir Freiha,
operations manager of the
First National Bank’s
Hamra branch. “The better services you give your
clients, the better deposits you receive.”

July 10, 2000 0 comments
0 FacebookTwitterPinterestEmail
Money Matters

Profits not ensured

by Avo Tavoukdjian July 10, 2000
written by Avo Tavoukdjian

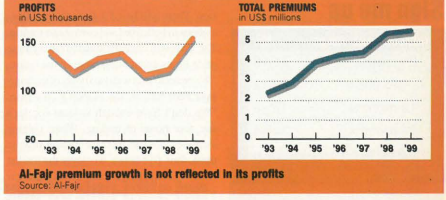
Isn’t turning a good profit on sales the
whole essence of business? Al-Fajr
insurance company, which has a capital
of more than $2.3 million, appears to
march to a different beat. Last year it
ranked 20th in the Lebanese insurance
market in premiums, while turnover
increased to $5.6 million, up 132% from
$2.42 million in 1993. Sounds promising so
far. But despite the growth, profits rose
less than 10% from $142,000 to $156,000,
while its profit-to-sales ratio nose-dived
from 5.8% to 2.8%. Such low returns
make little sense when Middle East
Assurance and Reinsurance Company
(Mearco) is capable of generating profits of
$159,000 with a portfolio of just $1.13 million,
a 13% profit-to-sales ratio.

The strategy of Al-Fajr leans towards survival
by extending its loyal client base on low
margins. But this comes at a cost: tiny profits.
Certain lines of insurance have a tendency
to not generate profits and quite often
result in losses, the biggest culprit being
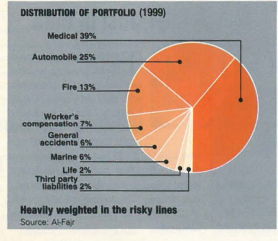
healthcare. Al-Fajr’s medical portfolio was
previously maintained below 20%. Now it
constitutes the largest line of insurance in Al-Fajr’s
portfolio, at 39% or $2.2 million. Not
smart. “Even in the best of circumstances,
medical insurance never generates profits of
more than 10% of the medical premiums collected,”
says Joseph Issa, Mearco’s lawyer
and one of the largest shareholders. The
firm’s chairman, Rached Rached, claims
that the line results in losses more often than
not. Aline Kamakian, general manager of Insurance Investment Consultant (IIC) and a shareholder in Mearco, similarly finds
medical insurance too risky. “We as brokers
have a portfolio of over $8 million in
medical, but rather than keeping the risk, we
pass it on to other underwriters,” she says.
“It’s just not worth the risk.”

Mearco is among the few local underwriters
that stay completely out of medical,
which still accounts for half of non-life
insurance premiums. Fouad Sawaya, Al-Fajr’s
manager, admits that healthcare is
most often a money loser, but views it from
a different perspective. Avoiding it completely
comes at the price of losing potential
clients who wish to get all their insurance
from one company. “We usually try to keep that line below 20%,” he says. “But
when your client purchases other forms of
coverage from you, you can’t refuse to provide
health insurance; the next year they’d take
their business elsewhere.” In fact, according
to Al-Fajr, the main reason behind the
increased medical portfolio is that when it
began providing coverage for the Beirut
port, offering medical to the port’s employees
was part of the package deal.

The next largest line of insurance at Al-Fajr
is auto insurance, which constitutes 25% of
its portfolio. Not as risky and unprofitable as
medical, but not a whole lot better either.
“One of the main reasons behind auto
insurance carrying risk and being generally
unprofitable is the lack of proper regulation,”
says Pierre Salameh, vice president for the
Middle East and North Africa for Caisse
Centrale de Reassurance (CCR). “Rates are
the lowest in the world while the motorists
are not disciplined and their driving history
isn’t taken into account.”

Al-Fajr is also taking some excessive risks.
Even with its sizeable medical portfolio, it still
doesn’t deal with third party administrators
(TPAs). “You need a TPA when your portfolio
starts to get really big on the medical side
and ours grew only just recently,” says Bassel
Hibri, Al-Fajr’s assistant manager. “A TPA
would help reduce unnecessary costs, boosting
profitability, and leave Al-Fajr’s management
free to focus on and develop more
profitable branches.

The company is also taking a risk in collecting.
Some 90% of premiums are collected
within three months, just within the limits of solvency. But the firm gives extended
facilities on some larger policies, up to a year
for some respected clients. “Should an accident
occur, the balance of the payments is
deducted from the settlement. And if the
client defaults on payments, they’re no longer
entitled to a settlement,” says Sawaya.

Leniency in payment terms could cause
liquidity problems for Al-Fajr. The market has
already demonstrated the folly of allowing
such extended payment terms, which caused
the downfall of more than one local insurer. “If
a company cannot count on its larger policies
for solvency,” wonders Joseph Mrad, a manager
at Adir, “what will it rely on, auto insurance
policies?” Others agree with Mrad. “I had
clients with whom I did business of nearly
$250,000,” says Kamakian, “but the most I
would allow was a month.”

But Al-Fajr isn’t leaving everything to
chance. It does have notable strengths, most
importantly its reinsurers, including ERC Frankona,
Swiss Re, Hannover Re, Lloyd’s of
London, Caisse Centrale de Reassurance
(CCR) and AXA. These
reinsurers, most of which
are rated triple A, will only
cover Al-Fajr’s portfolio for
the right price, which is one
of the factors behind the
low profits. Another example
is that it charges some of
the higher rates in the market.
The company is also
hesitant about using brokers.
“We have two or three
we trust, otherwise all business
is done directly
through the company,” says
Bassel Hibri. And potential
clients are closely scrutinized
beforehand, especially when the business
starts to get big. “Since it was established
in 1992, Al-Fajr’s portfolio has grown at
about 20% a year,” says Ghassan Hibri, the
company’s chairman. “But since the company’s
policy has been a selective one, growth
in 1998 and onwards subsided to 8%.”

Clients seeking medical coverage must see
Al-Fajr’s physicians, not a common practice
among local insurers, as well as filling
in questionnaires. Not nearly as effective as
dealing with a TPA, but the risk is still
curbed to a degree. Al-Fajr isn’t worried.
“When your clients are dispersed over several
sectors and you don’t have a TPA, you
can have problems,” says Sawaya. “Ours,
especially the medical portfolio from the
Beirut port, is contained.”

Life is among the smallest of Al-Fajr’s
branches. Only 2% of business is based on
what is considered to be the most profitable
of all insurance lines. Adir, for example, has
over 50% of its portfolio in life. With premiums
not much more than $4 million, Adir
retained profits of nearly $1.5 million in
1999, knocking its profit-to-premiums ratio
out of the ballpark at 35%. “We’ve had the life
license since we started operating,” says
Sawaya. “But life requires an altogether different
setup and a separate company to operate.”

Al-Fajr plans to develop this line soon.
Concerning expansion, Al-Fajr is in the
process of finalizing the establishment of an
insurance company in the Arab world.
Operations should start within two
months, but the company declined to disclose
further details.

Al-Fajr’s tactics are perhaps not the wisest,
but a point in its favor is that in providing
the riskier services to boost sales, it
also maintains a steady client base.

July 10, 2000 0 comments
0 FacebookTwitterPinterestEmail
Cover story

Withdrawal symptoms

by Robert Tuttle, Kirsten Vance & Peter willems June 27, 2000
written by Robert Tuttle, Kirsten Vance & Peter willems

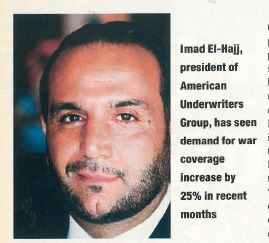
Imad El-Hajj, president of American
Underwriters Group (AUG), probably
never thought of it, but his job is much
like that of a priest. In times of trouble, anxiety,
and worry, people come running to
him. AUG is among a handful of insurance
companies that provide war-on-land
coverage — insurance for damages caused during
a military conflict.

Demand for
these policies increased 25% in recent
months, with tension building prior to the
Israeli withdrawal — not just in the South but
in Beirut and even Jounieh. The price of premiums
shot up by almost a third. Recently,
a professional syndicate requested that its
medical insurance coverage be extended to
include injuries sustained during wartime.

Now the Israelis are gone after 22 years
of occupation. When EXECUTIVE went to
print, there was a sense of victory across the
country. But despite the celebrations, there
remains uncertainty about what will happen
in the weeks and months to come.

Business does not lend itself to an atmosphere
of uncertainty, whether one is a
banana seller, bank manager, importer, or
stockbroker. The withdrawal has perhaps
brought a feeling of greater uneasiness
than during the occupation, which the
Lebanese had grown accustomed to.

“People feel that a scenario will soon be
played out,” says El-Hajj. “What kind of
scenario, they don’t know.”

There are worries that border conflicts
could escalate into far more punishing air
strikes than what has been seen in recent
times. “Nobody is doing anything, just
waiting to see what will happen,” says
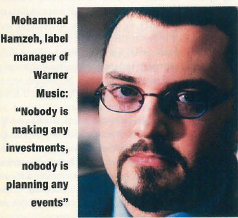
Mohammad Hamzeh, label manager of
Warner Music. “Nobody is making any
investments, nobody is planning any
events.”

At the Riviera Hotel, 20% of this
summer’s bookings are tentative compared
to last year’s near-zero rate. “They don’t
want to commit themselves,” says Nizar
Alouf, managing partner of the hotel.

The uneasiness of the region is affecting
international business circles. “There’s a lot
of indecisiveness from the Americans at this
point, and when you hear the word
Americans, that is business,” says Michael
Dunn, partner at Healey & Baker, a real
estate consultancy firm that helps local — but
primarily foreign — firms with their real estate
needs.

Even prior to Israel’s promises
of withdrawal, the political environment in
Lebanon had impacted its standing in the
investment community. Standard & Poor’s
sovereign rating for the country is BB with
a negative outlook, which is a speculative
grade allowing for political uncertainties.

“The probability of conflict after the
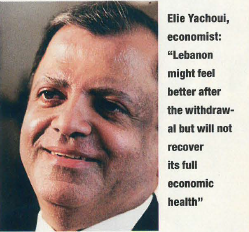
withdrawal is becoming higher,” says Elie
Yachoui, an economist, noting the Shebaa
Farms dispute and other issues. “For the
economy, that means a bad outlook for
investors and more recession.”

Probably the most disturbing murmurs
prior to the withdrawal emanated from
financial circles. In April, for the first time
in almost a year, the central bank was
forced to intervene in order to prop up the
pound. While figures were not disclosed,
analysts estimate that the bank spent
between $400 million and $450 million
over several weeks.

The pressure on the
pound had calmed down by the time of the
withdrawal, but the Lebanese currency’s
vulnerability is a cause for worry.

“If the withdrawal of Israeli troops in
South Lebanon leads to a deterioration of
stability, we will see a flight to foreign currencies,”
warns Navaid Farooq, Standard &
Poor’s sovereign analyst for the Middle
East and North Africa.

Even if the central
bank, in a bid to prevent the currency’s
collapse, hiked interest rates and started
spending its reserves, there could be panic.
“If depositors decide, in a mass hurry, to
switch from Lebanese pounds to US dollars,
then nothing that any commercial or central
bank can do could hold them,” says one
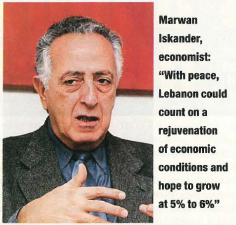
analyst. In the words of economist Marwan
Iskander: “The banking system could be
shaken to its roots.”

Depositors could rush the banks, changing
their pound-based accounts — 61% at the
beginning of 2000 — into dollars. And if that
happens, it could result in calamity.

People’s purchasing power and standard
of living could be reduced overnight. In a
country so dependent on imports, this
would be devastating. “If the pound were to
devalue by 20% or more, the circumstances
would become all that much harder.

Today, we have a difficult situation, and
if compounded further, it could become
explosive,” warns Iskander.

This would
spur high inflation. Many businesses and
individuals would not be able to repay
loans, and the value of Lebanese T-bills,
which represent a substantial portion of
most Lebanese bank assets, would tumble.

The worry isn’t only with local depositors
switching to hard currencies. Capital outflow
is another concern. “If we have confrontation
with Israel, it would be extremely difficult
for Lebanon to maintain the deposits of the
non-Lebanese, which constitute 30% of
total deposits,” says Iskander.

Couple that scenario with the already bad
economy and possibly hundreds of millions
of dollars in infrastructure damage
caused by Israeli air strikes, and it could
cripple the economy. For the cash-strapped
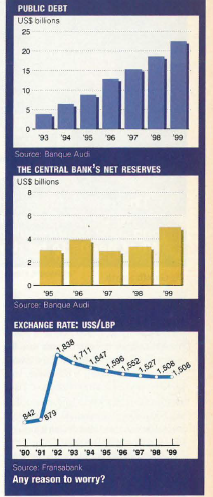
government, already drowning in nearly
$23 billion of debt, devaluation would create
further troubles.

While a weaker pound
would help relieve the domestic debt,
meeting overall debt payments would
become more cumbersome if Lebanon is
destabilized. “In the worst-case scenario,
there would be increased difficulties in collecting
revenues,” says Farooq.

But prophesying the worst might not be
well founded. The last ten years have witnessed
a spate of crises, from large-scale
Israeli bombardments of Lebanon’s infrastructure,
renegade militants in the North, to
a major turn of government. Through it all,
the sky never caved in, the pound remained stable, people
went to work, the kaaki
sellers continued to sell their kaak, and life went on pretty
much as normal.

Whether it is
coming or not now that the
Israelis have gone, conflict
is certainly nothing unusual to
the Lebanese; they have
lived with it through most of
the last three decades.

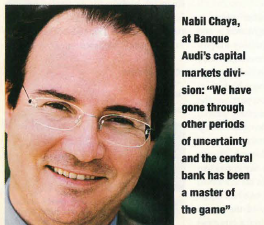
“We have gone through
other periods of uncertainty
over the last few years, and the central bank has been a master
at the game. They know
very well how to contain the pressure,”
says Nabil Chaya, head of the treasury at
Banque Audi’s capital markets
division.

Analysts point to
several key firewalls for the
bank. Foreign investors, who
own less than 10% of
Lebanese T-bills, cannot
directly speculate on the
pound, as they did in Southeast Asian countries during
the economic meltdown in
that region. This will help prevent
a “hot money” problem —
a sudden and massive sell-off
at the first signs of instability.

At the same time, the central
bank’s reserves were about $5
billion at the end of 1999 —
higher than ever since the end
of the civil war. If the bank
needed to step in again to
support the currency, it
should have enough reserves
to last for the short to medium
term.

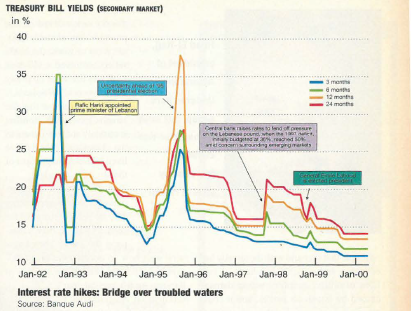
Although it would
choke investment and slow down
the economy further,
interest rates could be hiked to
defend the pound, as they
were during times of uncertainty
in 1992, 1995, and
1997 (see graph).

As a last
line of defense, the bank has
gold reserves estimated to be
worth between $2 billion and
$3 billion.

“Even if things go very badly,
no catastrophe is expected for
the simple reason that even with continuing
pressure, the central bank has huge
reserves,” says Mohieddine Kronfol,
financial analyst in the capital markets
division of Middle East Capital Group.

But even if there is no conflict in the
wake of the Israeli withdrawal, Lebanon has
plenty of problems to lose sleep over. “My
biggest concern,” says Kronfol, “is
Lebanon getting its house in order.”

The
government is stuck with a budget deficit
that reached 51.8% at the end of the first
quarter of 2000. That’s up from 42.4% at the
end of 1999 and a far cry larger than the
37.3% that was targeted for the end of this
year — anxiety.

The economy regressed by between –1%
and –1.5% last year, according to the Economist
Intelligence Unit and HSBC.

Official GDP growth estimates for this
year are at 1.5% to 2%. But a recent report
by the Bank of Beirut & the Arab
Countries states: “This year looks harder
than last, given the prudence and the wait-and-see
attitude of economic agents.”

According to a study done by the General
Labor Confederation and the International
Labor Organization, an estimated 48% of
the Lebanese population is on the verge of
poverty and 68% live below the middle
class line — anxiety.

Serious administrative reform has yet to
get underway, the government is locked in
disputes with a number of foreign companies,
and there are serious doubts that this government’s
privatization plans will go
through — anxiety.

At the same time, parliamentary
elections are coming up this
summer, and many are forecasting a change
of government — more uncertainty.

“These are the issues that weigh heavily
on Lebanon,” says Kronfol. “If the issues
are not addressed, the government will find
itself, against its current intentions, having
to raise interest rates to keep the depositors
from converting and keep banks participating
in T-bill auctions. This
would exacerbate Lebanon’s
current economic problems.”

Without solutions, the economy
will continue to deteriorate,
which itself could put pressure
on the pound.

What’s more, opinions are
divided about what may come
now that the era of occupation
has ended. The pullout could
usher in an era of stability.

“The problems with the economy
are obvious,” says Paul
Salem, development analyst.
“The only thing that can get us
out is peace and investment.”

And many people feel that the
withdrawal could be the first step towards
a comprehensive peace settlement.

“This
will turn a new page,” says Georges
Ghorayeb, general manager of the tile
manufacturer Lecico. “We don’t know
what’s coming, but I think it’s a step
towards a solution. We’re optimistic. We
still believe that the past of Lebanon was
much more dangerous than the future.”

The advantages of a peace settlement are
obvious: millions of dollars in foreign
investment and foreign aid, a flood of
tourists, possible trade liberalization.

“Lebanon could count on a rejuvenation of
economic conditions and could hope to
grow at 5% to 6% [per year],” says
Iskander.

He adds that the country may see
as much as $2 billion in compensation for
damages sustained during the Israeli occupation,
from the European Union, Japan, and
especially the oil-rich Arab countries.

“As
well, the privatization process would result
in greater receipts due to increased investor
confidence, which would lead to a larger
reduction in the debt stock, and we would
see increased tax revenues,” says Farooq.

Without a settlement, the benefits are
less obvious. Many political problems, such as
the Palestinian issue, would
continue to fester.

But if
the situation remains
calm, there would likely
be a certain increase in tourism revenue, and it
might prompt some
investment, especially in
the South.

This, according
to Iskander, would mostly
come from the Shiite community
that made money in
Africa, estimated to have
about $5 billion in wealth.
He estimates that as much as $500 million could flow into the South.

“That kind of investment in an economy as
small as Lebanon’s would make a significant
change,” he says.

While the economic choke on Lebanon
may be loosened, the country won’t
breathe easily. “If someone is sick and has
a siesta, how will he wake up?” asks
Yachoui. “Lebanon will probably feel better
after the withdrawal of Israeli troops, but
it does not mean that the country will
recover its full economic health.”

One thing is certain — Lebanon’s problems
did not go away with the Israelis.

June 27, 2000 0 comments
0 FacebookTwitterPinterestEmail
Best Sellers

Flat out flat

by Avo Tavoukdjian June 27, 2000
written by Avo Tavoukdjian

You couldn’t pick a worse time to be a
contractor. With the economy at a
standstill and the debt-ridden government
reducing public works expenditures,
construction projects are scarce. Contractors
are fighting over whatever business they can
find, even if that means bidding below cost.

But despite the doom and gloom, Butec, one
of the country’s oldest contracting firms, has
managed to keep its annual revenues around
$100 million for the last five years. “We’re
doing OK,” says Ziad Younes, Butec’s secretary
general, “but the market isn’t doing that
well.”

What is Butec’s antidote for the construction
slump? Specialization. Rather than
devoting its energy to building simple apartment
blocks or office buildings — the sort of
jobs that are the first to be hit when the economy
slows down — Butec concentrates on
technically complex projects that require specific
know-how. For these types of projects,
profits tend to be considerably higher.

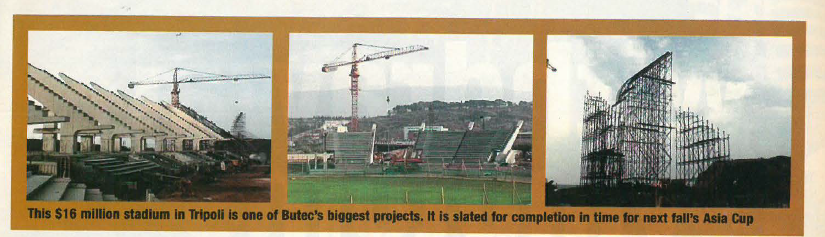
For example, Butec is building a $16 million stadium
in Tripoli. Work started in June 1999, and
the project is slated for completion in time for
next fall’s Asia Cup. Butec is also constructing
a 45-kilometer irrigation system in the
southern Bekaa, worth around $14 million.

Firms capable of handling these projects are
few, meaning less competition and higher
profit margins. “We don’t get involved in
projects where everybody bids, sometimes
below the direct cost of construction,” says
Younes. “Other companies can get a project,
but if they can’t complete it, at worst they
declare bankruptcy.”

Technically difficult projects tend to be
larger, which is another advantage. “The
greater the volume of materials and equipment
you purchase, the better the prices
you are apt to receive,” says Kamal Meine,
an architect. Sometimes, discounts reduce
the price per unit to as low as 50% to 60%
of the original sticker price. Butec manufactures
some of the equipment and materials
it uses itself, reducing costs further.

Because of its specialized nature, Butec
competes with only a handful of other companies.
Consolidated Contractors Company
(CCC), for example, has annual revenues
exceeding $1.5 billion. Along with its
German partner Hochtief, CCC constructed the
new $500 million Beirut International
Airport. Contracting and Trading Company
(C.A.T.), which is projecting a turnover of
$130 million this year, is another big competitor
to Butec.

“With few in the market
capable of taking on such complex projects,
competition is reduced substantially,” says
Ziad Kassis, owner of Unity Group, the company
currently building the Zahrani bridge.

Butec has also been targeting projects outside
Lebanon in order to counter the slowdown
in the domestic market. By doing
business abroad, Butec is able to balance its activities,
keeping itself and its staff operating.

The company teamed up with a local
affiliate to build a $130 million cotton-spinning
plant in Syria. The project was so successful
that, almost immediately, work started
on a second $110 million cotton plant.
Younes expects these two factories to
process between 10% and 20% of the country’s
total cotton exports.

The company was
also involved in the building of a $16 million
sewage plant in Latakia and one in Tartous
for $16.6 million. Butec is building a gas
compression station in Iran, a power plant in
Basra, Iraq, the Dubai Tower in the UAE, and
a pipeline with three substations extending
from Iraq to Jeddah.

Other contracting companies
such as C.A.T., which is working in
the Gulf and Africa — are following a similar
strategy: targeting markets abroad in order to
ride out the recession at home.

Butec has also diversified its services. The
firm, for example, established Butec Property
Management (BPM), which provides building
maintenance, cleaning, and security at facilities
that were built by the parent company.

But before giving Butec a big pat on the back,
consider this: While the company’s strategy of
specialization has kept revenues steady during
the recession, its competitor C.A.T. has
managed to increase its turnover by over
200% in the last four years by focusing on foreign
markets. C.A.T.’s revenues jumped
from $25 million in 1996 to $80 million in
1999.

“Specialization may help Butec hang on
to its turnover,” says Souheil Abou Habib, general
manager of Nassim A. Habib, a local
contracting firm. “But such projects don’t
come along too often and limit growth.”

While specialization has kept Butec alive,
real growth may require the company to look
at new strategies and be a bit less fussy about
the projects it is willing to take on.

June 27, 2000 0 comments
0 FacebookTwitterPinterestEmail
Best Sellers

From nuts ‘n’ bolts to gartersn’ lace

by Tania Avoukdjian June 27, 2000
written by Tania Avoukdjian

Seven years ago, Imad Kreidieh,
founder and majority shareholder of
Allied Distributors, tried to capitalize
on Lebanon’s building boom by selling construction
materials and electrical supplies.
Business was not brisk, though. The company
had barely got off the ground when it
dawned on Kreidieh that he was on a road to
nowhere. Rather than packing up and calling
it quits, he scanned the horizon for new
opportunities.

The building boom was in full
swing, so why not go into real estate? He
decided against it. The tourism business was
beginning to look promising as well, but he
didn’t open a hotel. Used cars? No. Fast
food? Guess again.

Kreidieh found his pot of gold in something
a bit more titillating: lingerie. It’s sexy and
always sought after. So in 1993, when Allied
Distributors came across a faltering company
selling French-made J&Gils men’s
underwear, it wasted no time in scooping it up.

Making the jump between selling something
heavy-duty to soft and sensuous may
seem a bit extreme. But it’s this flexibility
that has made Allied Distributors successful.
Soon after, it invested the limited profits
earned from construction into another
four lines of European-made women’s lingerie:
Alfa, Gizella, Scandale, and
Nicholetta, as well as Boli Blue swimwear.

In 1994, the company was distributing to
12 retailers. Two years later, that number
jumped to 165 and the company had double-digit
revenues of more than $300,000. But in
1997, sales started to sag. Increased competition
and the economic slowdown saw
revenues drop 50% to $150,000. They
remained at that level into 1998.

Rather than hanging up the panties and
going into yet another new line of business,
Allied downsized in an effort to reinvigorate
the company. Some employees were laid off
and the firm moved to a smaller office. At the
same time, the sales team was sent out to do
direct marketing with commission-based,
rather than fixed, salaries. The company
also turned on the marketing machine,
devoting 3% of revenues to advertising.

Those measures helped to push up sales to
$170,000 for 1999. For the first quarter of
this year, sales had already reached
$300,000. “If all goes as planned, we
should make it to $550,000 by the end of
2000,” says Kreidieh. That, while operating
on profit margins of
more than 30%.

But there are hurdles.

Competition is fierce.
“I can tell you who my
competitors are,” jokes
Kreidieh, “everyone
who sells underwear.”
That includes Hispaco,
the distributors of
Princessa and Telleno,
as well as Sindia, the lingerie branch of
Fattal, which sells such
big-name brands as Wonder Bra, Cacharel,
and Calvin Klein.

Kreidieh feels that his
prices, ranging between $25 and $50, are
some of the lowest in the business for mid-range
underwear.

Allied has aggressive plans to take on its
challengers. For the first time, the company is
planning a billboard campaign (see box).
Allied is moving into Internet sales as well,
investing nearly $5,000 in an e-commerce
website. “I can buy planes and cars through the
Net, why not boxer shorts?” asks Kreidieh.
“It’s a marketing operation. I’ll be advertising my
products plus getting e-mails. I am concerned about
the young generation, who spend practically
10% of their time on the Net.”

Maya
Waked, business manager at Sindia, disagrees:
“Internet sales are an option, but it’ll
be difficult for lingerie,” she says. Sindia
dedicates 10% of its budget to advertising,
mostly through magazines and billboards. In
its latest campaign, the company inserted
over 100,000 brochures in daily newspapers
and handed them out in movie theaters.

But Allied has another big plan to inflate
revenues. The company will be forming a
joint venture with Afra, one of its suppliers,
and opening its own manufacturing factory
in Tripoli by 2004. By manufacturing
locally, Allied will avoid paying customs
duties, which are at 40%, and be able to
lower prices. “The one who can control his
costs will win
,” says Kreidieh.

With the
new machinery, Allied will also be able to
add new lines of products to its collection,
such as babydolls, pajamas, and men’s lingerie,
and broaden its selection of colors
and designs. The company even hopes to
export to the United States and Japan.

What’s next on the list? With Allied Distributors,
you never know — and that’s what
makes the company tick. Flexibility is key
in an economy that is as unpredictable as
Lebanon’s. Who knows, before long we
might be able to walk into a supermarket
and buy edible underwear that tastes like
Kamar El-Din, courtesy of Allied.

June 27, 2000 0 comments
0 FacebookTwitterPinterestEmail
  • 1
  • …
  • 693
  • 694
  • 695
  • 696
  • 697
  • …
  • 708

Latest Cover

About us

Since its first edition emerged on the newsstands in 1999, Executive Magazine has been dedicated to providing its readers with the most up-to-date local and regional business news. Executive is a monthly business magazine that offers readers in-depth analyses on the Lebanese world of commerce, covering all the major sectors – from banking, finance, and insurance to technology, tourism, hospitality, media, and retail.

  • Donate
  • Our Purpose
  • Contact Us

Sign up for our newsletter

    • Facebook
    • Twitter
    • Instagram
    • Linkedin
    • Youtube
    Executive Magazine
    • ISSUES
      • Current Issue
      • Past issues
    • BUSINESS
    • ECONOMICS & POLICY
    • OPINION
    • SPECIAL REPORTS
    • EXECUTIVE TALKS
    • MOVEMENTS
      • Change the image
      • Cannes lions
      • Transparency & accountability
      • ECONOMIC ROADMAP
      • Say No to Corruption
      • The Lebanon media development initiative
      • LPSN Policy Asks
      • Advocating the preservation of deposits
    • JOIN US
      • Join our movement
      • Attend our events
      • Receive updates
      • Connect with us
    • DONATE